Meta Can Save $8.5 Billion in 2027 by Using It’s Own MTIA Chips
Meta is betting its entire AI infrastructure strategy on custom silicon it designed in-house, and one major bank has put a very specific dollar figure on what that gamble could be worth by 2027.

Anchor Number: $8.5 Billion
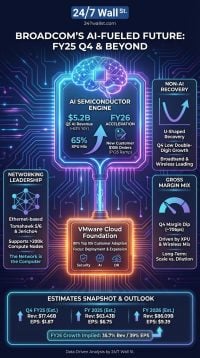
Bank of America estimates that Meta Platforms (NASDAQ:META | META Price Prediction) could save roughly $8.5 billion in 2027 by running AI workloads on its own custom silicon instead of buying third-party chips. That figure is an outside analyst estimate, not company guidance, and it hinges on a specific chip roadmap: Meta plans to deploy its third-generation MTIA 450 chip, code-named Arke, in the first half of 2027, followed by the higher-performance MTIA 500, or Astrid, later in the year. Both are co-developed with Broadcom (NASDAQ:AVGO) and aimed at AI inference workloads.

What It Means for Meta
The $8.5 billion figure only lands with context. BofA models Meta deploying 5 to 6 gigawatts of owned capacity in 2027 at a total cost of roughly $200 billion, assumes chips make up 60% of that spend, and pegs Meta’s custom silicon as about 40% cheaper than third-party equivalents. Multiply those assumptions together and you get the savings number in the headline.
That matters because Meta’s capital budget has moved into a different orbit. FY2026 capex guidance now sits at $130 billion to $145 billion, narrowed from $125 billion to $145 billion, and total expense guidance was raised to $165 billion to $169 billion. Q2 2026 capex alone hit $30.12 billion, up 82.1% year over year, and CFO Susan Li told analysts, “Consequently, our current plans are geared towards maximizing 2026 and 2027 capacity.” Chip cost is the single largest line inside that budget, so a 40% haircut on a majority of it flows straight to operating leverage.
Management has framed the strategic case in its own words. “We have been making strategic investments in areas like our internal custom silicon effort which will provide long term strategic flexibility and supply chain leverage,” Li said on the Q2 call, adding it “will be helpful in driving better returns on those long term investments.” Chief Executive Mark Zuckerberg went further: “We are really a full-stack technology company. We built our own data centers, our own infrastructure, our own chips, our own low-level software.”
Market Reaction
Meta shares have been rebuilding after a rough summer. The stock is up 18.34% over the past month, from $568.97 on August 17, 2026 to $673.34 on September 17, 2026, and up 3.01% over the past week. Year to date, the shares are up just 2.18%, and they remain down 13.29% over the last 12 months. Broadcom, the partner whose custom-silicon franchise Meta is scaling around, has slipped 10.79% over the past month to $350.10.

Bull Case
Meta’s core advertising engine is still expanding while the AI bill balloons. Q2 2026 revenue reached $60.80 billion, up 27.96% year over year, with advertising revenue of $59.36 billion up 27%. Family of Apps daily active people hit 3.60 billion, up 3%, and ad impressions rose 14% while average price per ad climbed 12%. That is the revenue base absorbing infrastructure spend.
The bull thesis on MTIA is that unit economics matter at this scale. Broadcom itself has told investors what custom silicon can do relative to merchant GPUs. “When you co-develop a chip that is optimized for your particular LLM workloads, you will outperform any GPU,” CEO Hock Tan said on the Broadcom call, adding customers can “do all this at half the cost of a GPU.” Tan confirmed the Meta program directly: “Between now and the end of 2027, we will be delivering three generations of MTIA accelerators to Meta,” with line of sight to 3 gigawatts of deployment through 2028 and production shipments of the MTIA accelerator “optimized for inference and recommendation at scale” beginning in fiscal Q4.
Meta is also compute-constrained today. Zuckerberg said the company has “numerous ROI positive places” to put more compute if it had the capacity, and is fielding offers to sell available compute externally “at a meaningful premium” over what it paid. Cheaper in-house chips widen the spread on both internal use and any capacity Meta chooses to monetize. All of that buildout still has to be powered, cooled, and networked by somebody, and we pulled seven of those suppliers into a free AI infrastructure report.
Bottom Line
For long-term holders, the $8.5 billion is a modeled outcome, not a booked one. But the direction of travel is on the record: three MTIA generations through 2027, a partner confirming the deployment cadence, and a management team pointing analysts toward better returns on a capex line running at $130 billion to $145 billion this year. Citi flagged a Meta event next week as a potential catalyst for the stock. If Arke and Astrid ship on schedule, 2027 is when the leverage shows up in the numbers instead of the slide deck.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.