Rocket Lab Is Playing a Much Bigger Game Than Rocket Launches, Eyes 90% Upside
Rocket Lab has spent the past year quietly transforming into something Wall Street has yet to fully price in, and the gap between what investors see and what the company is actually building may be the most important story in…

Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) has spent the last year quietly rewriting its identity. It is no longer just a small-launch specialist. Between the pending Iridium acquisition, the Mynaric and Motiv deals, and a stacked defense pipeline, Rocket Lab is building an end-to-end space power. The 24/7 Wall St. price target reflects that.
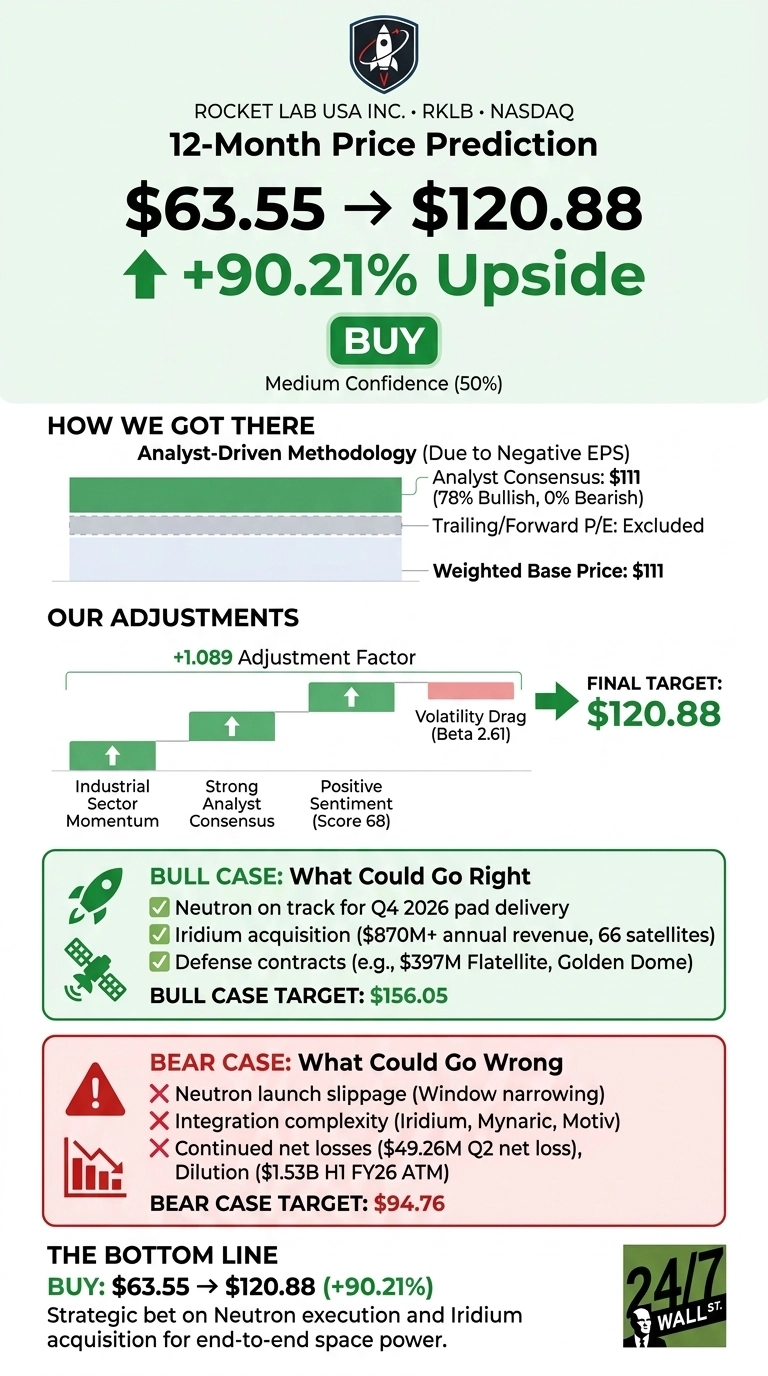
Our 24/7 Wall St. price target for Rocket Lab is $120.88, implying 90.21% upside from the current $63.55 share price. Our recommendation is buy at 50% confidence, a moderate reading that reflects both the size of the opportunity and the execution risk in front of it.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $63.55 |
| 24/7 Wall St. Price Target | $120.88 |
| Upside | 90.21% |
| Recommendation | BUY |
| Confidence Level | 50% |
A Rough Month Masks a Blockbuster Quarter
Rocket Lab shares are down 20.81% over the past month and 8.9% year to date, sitting well below the $151 52-week high. Yet the fundamentals are moving the other way.
Q2 FY26 revenue reached a record $234.07 million, up 62% year over year, with backlog swelling to $2.36 billion, a 137% jump. Management said more than $1 billion in new contracts were already booked in Q3 alone, including a $397 million Flatellite award and a role on the $816 million SDA Tracking Layer Tranche 3 contract.

Why Bulls See a Breakout Ahead
The bull case is straightforward: Rocket Lab is stacking optionality faster than the market can price it. CEO Peter Beck framed the strategy across three verticals of “access to space,” hardware in space, and space applications, adding that “with Iridium, Rocket Lab will have all three of these verticals.”

Iridium brings 66 satellites, 2.5 million subscribers, and more than $870 million in annual revenue. Neutron is on track for a Q4 2026 pad delivery, and selection for the Golden Dome Space Based Interceptor program and the MDA SHIELD program adds long-tail defense revenue. Our bull-case scenario points to $156.05 within a year.

What Could Go Wrong
Neutron slippage is the biggest single risk. Management admitted the “window for an end-of-year launch is narrowing.”
Integration of Mynaric, Motiv, and Iridium is complex, and Rocket Lab remains deeply unprofitable, with a $49.26 million Q2 net loss and heavy dilution: $1.53 billion in H1 FY26 ATM proceeds.
Bulls counter that Q2 GAAP results included $8.58 million in acquisition costs and that non-GAAP gross margin expanded to 41.5%. Still, our bear scenario tags $94.76.
How Rocket Lab Compares to Planet Labs and Intuitive Machines
Planet Labs (NYSE:PL) is the cleanest recurring-revenue comp in space data. It posted Q2 FY27 revenue of $116.05 million, up 58% year over year, with 98% recurring ACV and adjusted EBITDA of $13.93 million.
Planet’s $5.45 billion market cap against Rocket Lab’s $38 billion shows how much investors are already paying for RKLB’s launch plus applications story. That relative premium suggests our 24/7 Wall St. price target is ambitious but not unreasonable if Iridium closes.
Intuitive Machines (NASDAQ:LUNR) is the closest peer on defense and lunar infrastructure. LUNR reported Q2 2026 revenue of $206.17 million and full-year guidance of $900 million to $1 billion at just a $2.23 billion market cap.
On a revenue-multiple basis, LUNR trades at a fraction of RKLB, reinforcing that our 24/7 Wall St. price target embeds a strategic premium for launch ownership and constellation control that neither peer offers.
Rocket Lab Price Prediction 2026-2030
My verdict: Buy, target $120.88, confidence 50%. The 24/7 Wall St. price target is really a bet that Neutron flies and Iridium closes.
Key catalysts to watch: a Neutron pad delivery this quarter would strengthen the bull case, while an Iridium timeline slipping past mid-2027 or accelerating dilution would weaken it.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $77.68 |
| 2027 | $137.34 |
| 2028 | $210.99 |
| 2029 | $255.80 |
| 2030 | $330.15 |
These projections assume Neutron enters commercial service on schedule and Iridium closes as planned. Significant upside or downside could come from orbital data-center adoption or Golden Dome program funding shifts.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.