Because Broadcom Monetizes Alphabet, Meta, and OpenAI at Scale I Buy Again and Again
Hock Tan built something rare in tech: a tollbooth that the biggest AI spenders on the planet have no choice but to pay. Here is why that changes where my next dollar goes.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
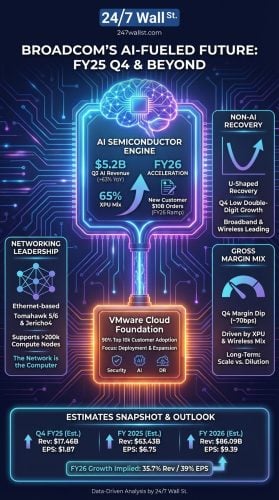
I keep hitting the buy button on Broadcom (NASDAQ:AVGO | AVGO Price Prediction) because Hock Tan has quietly built the toll road that Alphabet, Meta, OpenAI, and Anthropic must drive down to reach their AI ambitions. Every custom accelerator these frontier labs deploy sends a fresh check to San Jose, and the checks are getting larger every quarter.
Hyperscaler Tollbooth in Plain Numbers
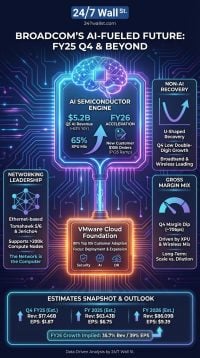
Broadcom’s fiscal Q3 2026 posted revenue of $29.59B, up 85.5% year over year, with AI semiconductor revenue of $16.70B, up 221% YoY and 54% sequentially. Guidance for Q4 calls for AI chip revenue of roughly $21.7B, up 236% YoY. Hock Tan told the call, “Q3 demand was simply hot and we’re just getting started.”
The customer roster is where my conviction hardens. Broadcom serves six XPU customers, and management laid out the deployment map on September 2: multi-tens of billions of dollars of TPUs annually for Google, one gigawatt of Ironwood in 2026 and another five gigawatts of TPU v8i in 2027 for Anthropic, 1.3 gigawatts of Jalapeno in 2027 for OpenAI with over 5 gigawatts across successor generations in 2028, and three generations of MTIA accelerators to Meta through 2027. Tan said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028” against an AI revenue outlook of $230 billion in fiscal 2028.
Cash Machine Feeding a Rising Dividend
Q3 free cash flow reached $13.67B, or 46% of revenue. That cash funds a dividend I keep reinvesting. The board declared $0.65 per share for Q3, the fifteenth consecutive annual increase since fiscal 2011. The quarterly payout has climbed from $0.07 in December 2010 to today’s rate. The EPS beat streak now sits at 10 quarters, with Q3 non-GAAP EPS of $3.32.
Passing on Nvidia With Fresh Capital
The reflex AI chip pick is NVIDIA (NASDAQ:NVDA), and I own it too. What tilts new dollars toward Broadcom is a line Hock Tan delivered on the September 2 call: “when you co-develop a chip that is optimized for your particular LLM workloads, you will outperform any GPU” at “less than half the cost.” Broadcom said its TPU v8i is comparable to, or surpasses, the Vera Rubin GPU and that Jalapeno outperforms Grace Blackwell for inference workloads. Every hyperscaler that concludes its economics require custom silicon becomes a Broadcom customer for a decade.
Risk I Own With Eyes Open
Customer concentration is real. Six XPU customers, four expected to be particularly large, means any single hyperscaler pulling back would leave a crater. The one-month drawdown of 13.84% shows how quickly sentiment swings on that fear. My answer: these customers are the labs building frontier models, their capex commitments run for years, and management said demand exceeds the current outlook while supply has already been secured for the $115 billion fiscal 2027 and $230 billion fiscal 2028 AI outlooks.
Buy Button Stays Active From Here
The five-year total return sits at 720.39% and the ten-year at 2,849.28%. When the operator collecting the toll compounds cash at 46% of revenue and raises its dividend every year, I keep feeding the meter.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.