DTE Could Be One of the Quiet Winners of the Data Center Boom
DTE Energy has been quietly signing contracts with some of the biggest hyperscalers on the planet, and the numbers behind that pipeline suggest most investors are not yet pricing in what it could mean for earnings growth.

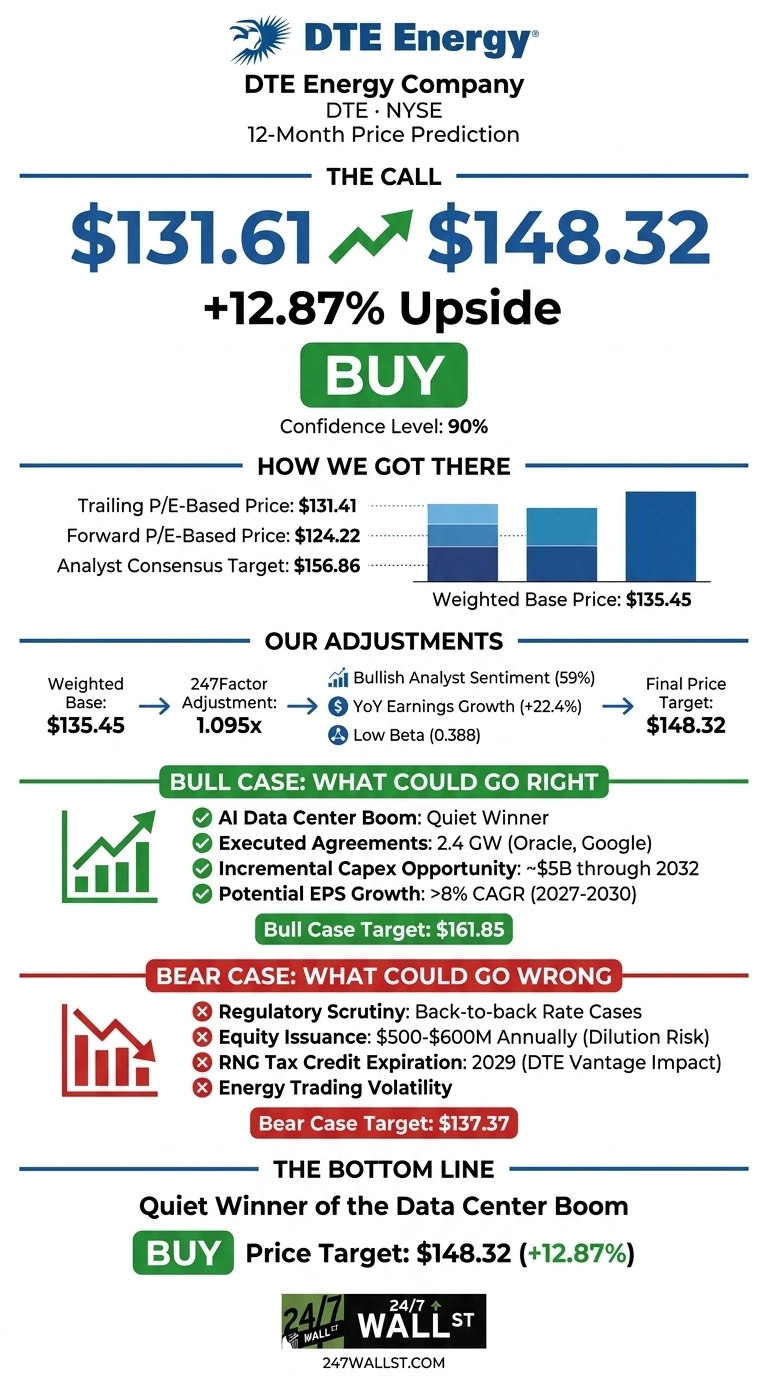
Our 24/7 Wall St. price target for DTE Energy (NYSE:DTE | DTE Price Prediction) is $148.32, roughly 12.87% above the recent quote of $131.61. Our recommendation is buy, with a confidence level of 90%.
The Detroit-based regulated utility is quietly becoming one of the cleanest ways to play the AI power buildout, with signed hyperscaler contracts already in the plan and a multi-gigawatt pipeline that management believes can push earnings growth above its long-term target.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $131.61 |
| 24/7 Wall St. Price Target | $148.32 |
| Upside | 12.87% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Quiet Pullback Into an Improving Story
DTE has slipped 6.76% over the past month and 3.27% in the past week, though shares remain up 3.65% year to date and sit between the $124.25 52-week low and the $155.75 52-week high.
Q1 2026 operating EPS of $1.95 missed the $2.03 consensus, dragged by a $25 million Energy Trading loss, but the core utility earnings rose meaningfully on the February rate order. Management reaffirmed 2026 operating EPS guidance of $7.59 to $7.73, with confidence toward the high end.
Why Bulls See a Breakout Ahead
The bull case is the AI grid. DTE has 2.4 gigawatts of executed agreements, anchored by a 1.4 GW Oracle deal already under construction and a 1 GW Google agreement in Van Buren Township that could unlock roughly $5 billion of incremental capex through 2032.
Behind that sits another five to six gigawatts of pipeline, with two gigawatts in advanced discussions targeting another signed contract by year end. CEO Joi Harris said on the Q2 call, “Momentum remains strong as we continue to execute across our development pipeline.”
Management explicitly stated that three gigawatts gets us eight plus on EPS growth. In a bull scenario, DTE trades toward $161.85, roughly the analyst target of $156.86 plus upside from a third hyperscaler contract.

All of that hyperscaler load has to be powered, cooled, and connected by somebody, which is the whole reason the picks and shovels of the data center buildout keep showing up in our free AI infrastructure report, here.
What Could Go Wrong
The bear case starts with regulatory scrutiny. Back-to-back rate case filings have drawn attention from the Michigan Public Service Commission, and the $36.5 billion five-year capex program requires $500 to $600 million of annual equity issuance through 2028, creating real dilution.
Energy Trading volatility hit Q1 hard, and RNG tax credits at DTE Vantage expire in 2029. That said, the counterfactual matters: the equity raises fund contracted rate base growth, and DTE has structured data center deals with minimum billing demand of 80% and contracts of 10 years or longer to protect against stranded assets. A bear scenario likely holds DTE near $137.37.

How DTE Compares to CMS Energy and Constellation Energy
CMS Energy (NYSE:CMS) is the obvious in-state comparison. It carries a $20.7 billion market cap and has guided 2026 adjusted EPS of $3.83 to $3.90 with the same 6% to 8% long-term growth target. CMS points to a roughly 9 GW economic development pipeline covering data centers and semiconductors.
DTE’s 2.4 GW of signed contracts is currently more advanced than CMS’s disclosed signings, which makes our $148.32 target look reasonable rather than aggressive.
Constellation Energy (NASDAQ:CEG) is the merchant-power counterpoint. CEG has a $92 billion market cap and 2026 adjusted EPS guidance of $11.50 to $12.50 with base EPS growth of 20%+ through 2029.
Investors pay a rich multiple for that nuclear-fueled hyperscaler exposure. DTE offers the same data center theme wrapped in a 3.52% dividend yield and regulated returns, making it the lower-risk expression of the trade.
| Company | Forward P/E | Long-Term EPS Growth |
|---|---|---|
| DTE Energy | 16 | 6-8% (8%+ with data centers) |
| CMS Energy | n/a | 6-8% |
| Constellation Energy | n/a | 20%+ |
I’d Buy It Here
The 24/7 Wall St. price target of $148.32 gets me to a buy at 90% confidence. The tipping factor is signed contracts: DTE has signed contracts and is actively building for the load.
The setup strengthens if the Google deal clears the MPSC and management raises long-term EPS guidance above 8%. The thesis weakens if the pipeline stalls and rate case pushback forces further equity issuance beyond the current plan.
Looking further out, here is where our model projects DTE could trade over the next five years, assuming the data center pipeline continues to convert on schedule.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $148 |
| 2027 | $162 |
| 2028 | $174 |
| 2029 | $186 |
| 2030 | $199 |
These projections assume DTE executes on its $36.5 billion capex plan and hyperscaler load ramps in line with management commentary. Meaningful upside or downside could come from additional signed contracts, regulatory outcomes, or shifts in Michigan’s economic development trajectory.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.