Prediction: Alphabet’s Best Days May Still Be Ahead
Google Cloud is growing at a blistering pace, Gemini is everywhere, and Wall Street is almost universally bullish, yet the stock sits near its lowest valuation in years. Something about that gap does not add up.

Google (NASDAQ:GOOG | GOOG Price Prediction) just delivered one of the loudest AI-era quarters we have seen from a mega-cap. Google Cloud revenue jumped 82% in Q2 2026, backlog swelled to $514 billion, and the Gemini App now touches 950 million monthly active users.
Yet the stock is up just 7.11% year to date. Can Alphabet actually reach $600 per share by 2028?

What’s Holding Alphabet Back Right Now
The market is worried about one thing: capex. Alphabet spent $44.92 billion on capital expenditures in Q2 alone, guided full-year 2026 capex to $175 billion to $185 billion, and posted negative $5.86 billion in free cash flow. Buybacks were suspended in the quarter, and long-term debt climbed sharply to fund the AI buildout.
Shares reflect that anxiety. GOOG is down 1.96% over the past month and essentially flat over the past week (0.04%). With a beta of 1.225, this is not a quiet stock, and investors are demanding proof that the spend converts to durable cloud economics before rerating it.
Wall Street Sees 26% Upside. Our Model Says 50%
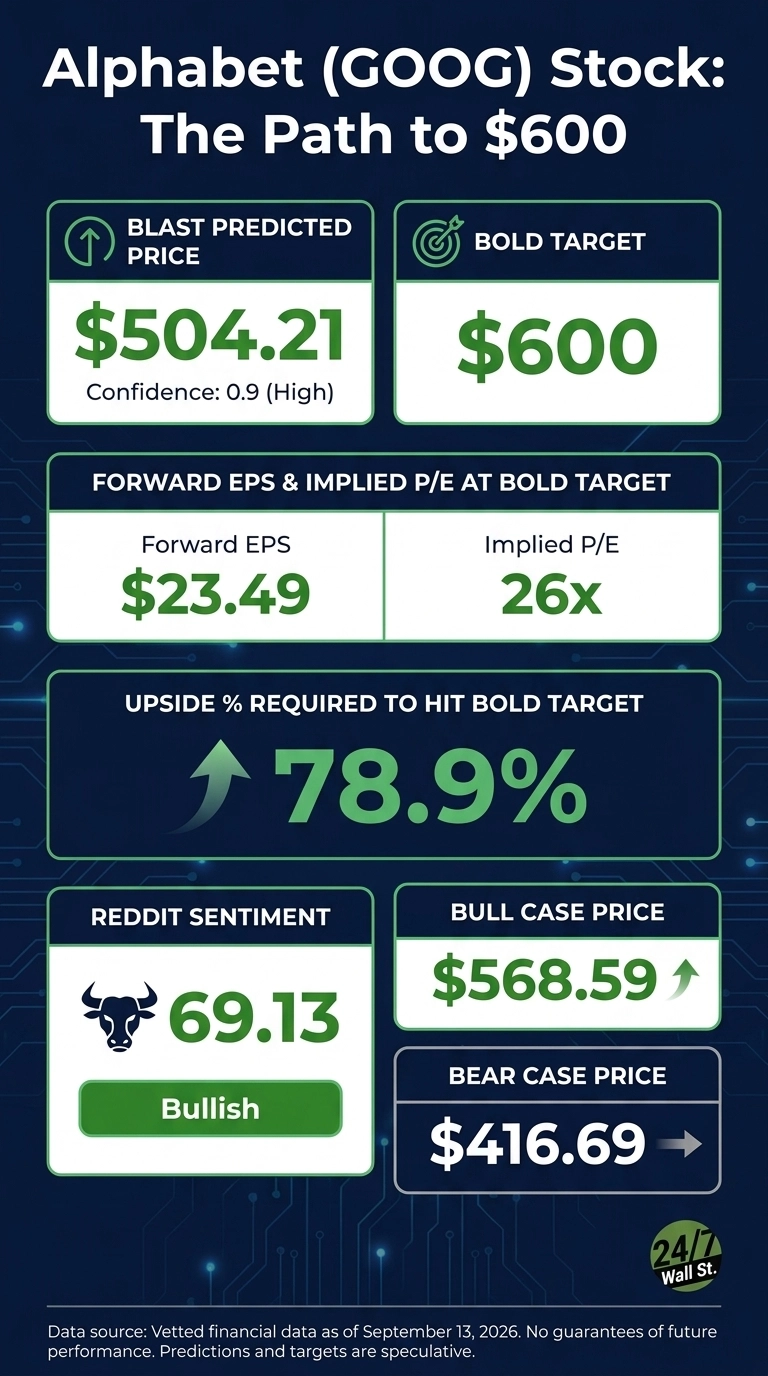
The Street’s consensus target sits at $422.34, backed by 13 strong-buy, 44 buy, and 5 hold ratings, with zero sells. Our own base case is more aggressive at $504.21, implying 50.31% upside, with a bull case of $568.59 and bear case of $416.69. Confidence is rated high (0.9).

My take: consensus is too anchored to trailing multiples. Analyst sentiment is 92% bullish with zero bears, yet the target implies almost no multiple expansion. With Google Cloud compounding at triple-digit-adjacent rates and TPU system revenue set to ramp in 2027, that anchoring looks stale.
Path to $600 Per Share
Reaching $600 from today’s price of $335.45 would require a gain of 78.9%. With forward EPS of $23.49, a price of $600 implies a forward P/E of 26x. Our base case of $504.21 already implies 17x, meaning the bold target requires roughly 9x of additional multiple expansion.
Achievable? Here is why I think it is. Sundar Pichai told analysts, “from ROIC standpoint… over the past year, we’ve gotten more bullish on the opportunities ahead.”
Three catalysts anchor the case: cloud backlog at $514 billion with just over 50% convertible to revenue within 24 months; Gemini Enterprise embedded in nearly 90% of the Fortune 100; and Search still expanding, with AI Mode now past 1 billion monthly active users. If EPS compounds and capex intensity moderates by 2028, P/E expansion follows.

The primary risk: a prolonged period of negative free cash flow if AI monetization lags the infrastructure build.
Where Alphabet Trades Today vs Its Earnings Power
At $335.45, GOOG trades at roughly 14x forward earnings. That is cheap for a business growing revenue 24.23% year over year with a 34% operating margin.
Shares sit between the 52-week high of $403.96 and low of $236.07, and the stock has returned 791.54% over 10 years. Valuation looks reasonable relative to the growth on offer.
Is $600 Realistic? Here’s My Take
Getting to $600 by 2028 requires that 78.9% gain, and it is a stretch. My verdict: realistic but not easy.
Three things need to go right. Cloud must sustain 40%-plus growth as backlog converts. Capex intensity has to peak in 2026 and roll into free cash flow expansion by 2027. Search monetization through AI Mode and AI Max needs to prove additive rather than cannibalistic.
What would derail it: a regulatory shock or evidence that TPU-driven cloud economics cannot scale into positive operating leverage. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Google could reach $600 in 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.