This Could Be the Magnificent 7’s Biggest AI Surprise by 2028
Alphabet just posted monster cloud growth while its stock barely moved, and Wall Street's cautious price targets may be missing something big building quietly beneath the surface.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Alphabet (NASDAQ:GOOG | GOOG Price Prediction) just delivered a quarter that should reset expectations. Revenue hit $119.80B, up 24.2% YoY, and Google Cloud grew 82% to $24.77B.
Yet shares are up only 7.27% this year at $335.95. That gap suggests the market may not have fully priced in Alphabet’s AI upside. Can it reach $600 by the end of 2028?

What’s Holding Alphabet Back Right Now
Cash flow is under pressure: management guided 2026 CapEx to $175 billion to $185 billion, and Q2 spending of $44.92B pushed free cash flow to negative $5.86B. Long-term debt rose from $46.5B to $98.2B, and buybacks were suspended.
Shares gained just 0.29% over the past week and sit 16.8% below the 52-week high. Management flagged pressure on cloud margins from third-party capacity and Wiz integration. With a beta of 1.225, sentiment swings hit this stock harder than the market.
Wall Street Sees 26% Upside, But I Think It’s Too Cautious
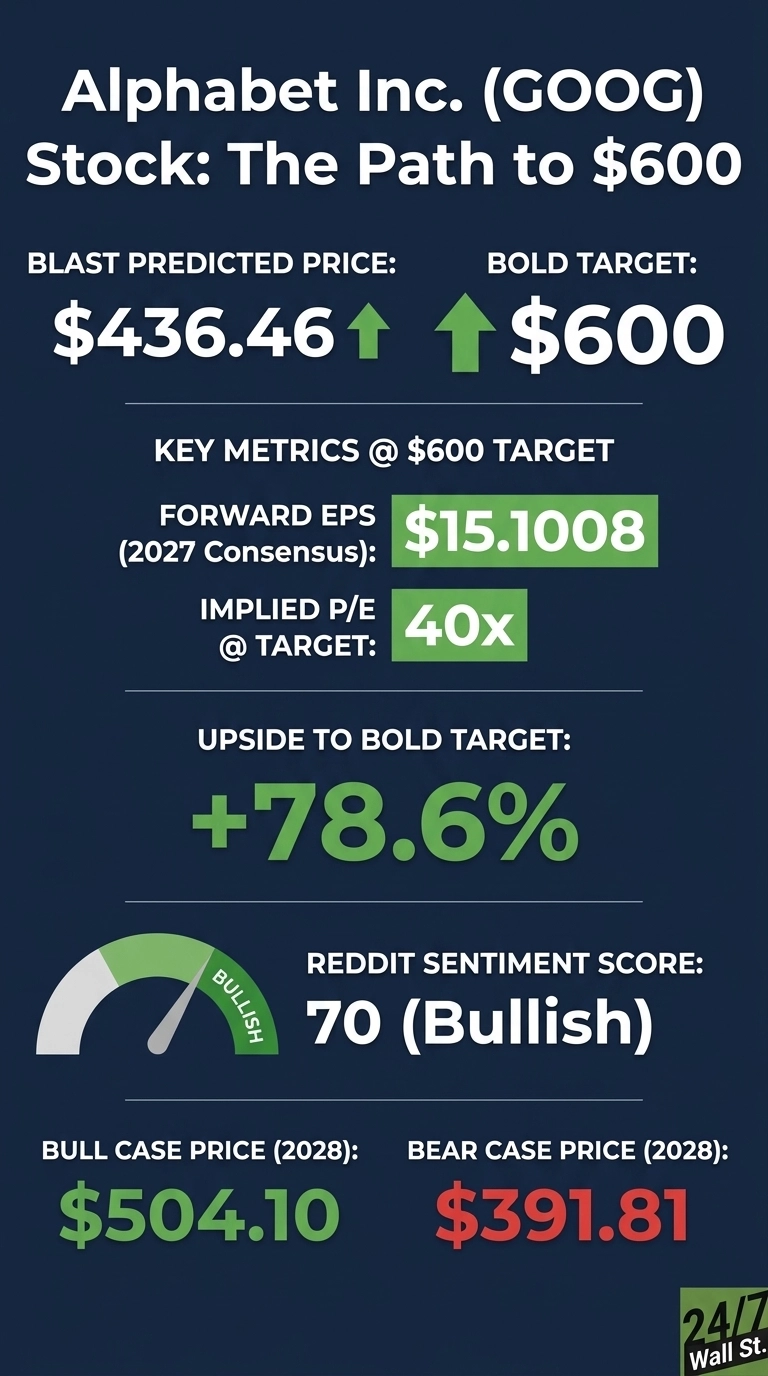
The consensus target is $422.34, about 25.7% above today’s price, backed by 13 Strong Buys, 43 Buys, 5 Holds and zero Sells. Our model’s base case of $436.46 implies 29.9% upside within a one-year range of $369.26 to $453.5, with a confidence score of 0.7.

Analyst targets may lag the fundamentals: sentiment is 92% bullish, and earnings growth added 0.03 to our adjustment on “strong earnings acceleration.” Consensus 2027 EPS has rose from $14.4741 to $15.1008 in 90 days. The 2028 base case sits at $521.31.
Here’s What It Takes for Alphabet to Reach $600
A move to $600 from today’s price of $335.95 would require a gain of 78.6%.
With forward EPS of $15.1008 (2027 consensus), a $600 price implies a forward P/E of 40x. The base case of $436.46 implies 29x, so the bold target needs 11x of additional multiple expansion.
Earnings growth does much of that work. Consensus sees 2027 EPS rising 27.9% from the 2026 estimate of $11.81. By late 2028, investors will price later years’ profits, bringing down the effective multiple.
Cloud backlog reached $514 billion, with just over 50% expected to convert to revenue within 24 months. TPU system sales ramp as 2026 ends, with most revenue landing in 2027. The Gemini app has 950 million monthly users. CEO Sundar Pichai said, “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
The primary risk is that CapEx exceeds returns and keeps free cash flow negative longer than investors will bear. That spending has to be powered, cooled and connected by somebody, which is why we pulled together seven suppliers riding the same AI expansion in a free report.
Where Alphabet Trades Today vs. Its Earnings Power
At $335.95, Alphabet trades at 22x 2027 consensus EPS. The trailing P/E of 17 looks cheaper, but a $99.03B gain on equity securities inflated trailing earnings.
Against expected EPS growth near 28%, 22x is reasonable. Shares sit between a 52-week low of $236.07 and high of $403.96, with 772.65% returns over 10 years.
$600 Is a Stretch, But Here’s Why It’s Possible
A $600 target requires a 78.6% gain. The move is a stretch, but credible over two-plus years. Google Cloud must convert backlog into revenue at healthy margins. Gemini must keep lifting Search monetization.
TPU sales must become a real revenue line in 2027. A sustained Search slowdown as AI competition heats up would undermine the thesis. Keep an eye on Cloud backlog conversion, Search monetization and TPU revenue as the key markers on the path to $600 in 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.