One Magnificent Seven Stock Could Outperform the Rest in 2026
One Magnificent Seven stock is growing its cloud business faster than any rival while trading at a fraction of their valuations, and the gap between where it sits today and where the fundamentals say it belongs is the widest in…

Alphabet (NASDAQ:GOOG | GOOG Price Prediction) has quietly become the most interesting name in the Magnificent Seven heading into the back half of 2026. Google Cloud growth accelerated to 82% in Q2, Gemini adoption is scaling across the Fortune 100, and yet the stock still trades at a P/E multiple in the mid-teens.
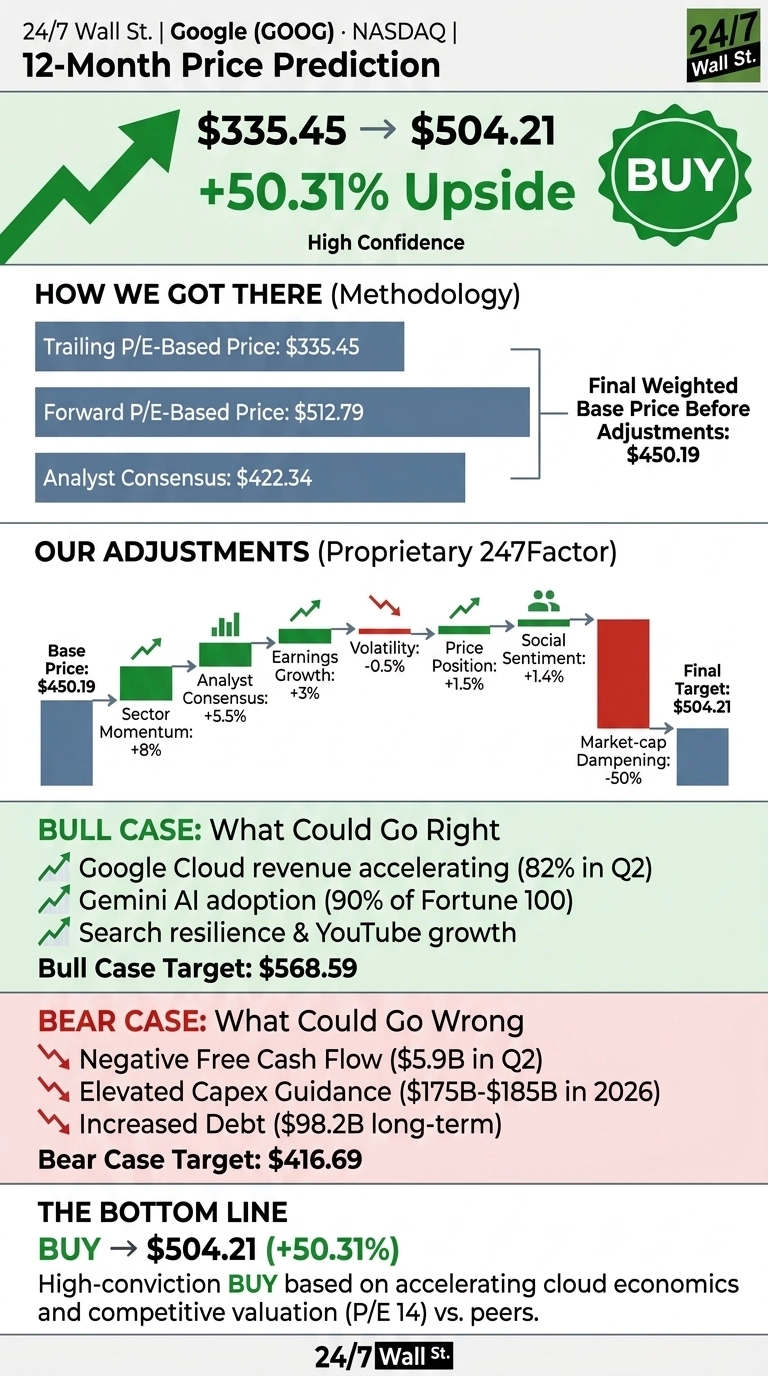
My 24/7 Wall St. price target for Google is $504.21, implying 50.31% upside from the current price of $335.45. That is the widest gap I see in the Mag 7 today.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $335.45 |
| 24/7 Wall St. Price Target | $504.21 |
| Upside | 50.31% |
| Recommendation | BUY |
| Confidence | 90% |

Why Google Is My Top Mag 7 Pick for 2026
Shares are up 7.11% year to date and 39.68% over the past year, but the stock has actually cooled off, slipping 1.96% over the past month against a 52-week high of $403.96. That pullback is what makes today interesting.
Q2 was, in CEO Sundar Pichai’s words, “an amazing quarter”: revenue of $119.8 billion, up 24.23%, with EPS of $9.11 against a $3.0427 estimate. Google Cloud hit $24.77 billion, backlog reached $514 billion, and nearly 90% of Fortune 100 companies now use Gemini Enterprise. Search revenue still grew 17%, killing the AI cannibalization thesis.
Bull Case: $568 and Beyond
Bulls have a clean thesis. Google Cloud has printed 34%, 48%, 63%, and 82% growth in the last four quarters, and the $514 billion backlog is a multi-year revenue runway. TPU system sales to external customers are just beginning to hit the P&L, with the majority of revenue expected in 2027.
Gemini App usage tripled year over year to 950 million monthly active users, and API token throughput jumped from 16 billion to 22 billion per minute in a single quarter. Our bull-case scenario points to $568.59, a 69.5% return.
Analyst distribution supports the tilt: 13 strong buys, 44 buys, 5 holds, zero sells.

What Could Go Wrong
The bear case starts with capex. Alphabet guided $175 billion to $185 billion of 2026 capex, free cash flow turned negative at -$5.86 billion in Q2, long-term debt more than doubled to $98.2 billion, and the buyback was suspended. Insider activity has skewed net selling.
The counterfactual: management has explicitly framed the spend as demand-driven, and cloud operating margin still expanded from 20.7% to 35.6% year over year while capex ramped. Our bear case still lands at $416.69, a 24.22% gain from here.

How Google Compares to Microsoft, Meta, and Amazon
Microsoft (NASDAQ:MSFT) is the cleanest cloud/AI comp. Azure grew 43% in fiscal Q4 and Microsoft 365 Copilot passed 30 million paid seats, but MSFT trades at a P/E of 28, roughly double Google’s 14.
Meta Platforms (NASDAQ:META) is the ad-revenue benchmark. Meta grew ad revenue 27%, yet its Q2 EPS came in below expectations and it carries a P/E of 24.
Amazon (NASDAQ:AMZN) grew AWS 37% at a P/E of 36.
| Company | P/E | Latest Cloud/Ad Growth |
|---|---|---|
| 14 | Cloud +82% | |
| Microsoft | 28 | Azure +43% |
| Meta | 24 | Ads +27% |
| Amazon | 36 | AWS +37% |
Against this field, Google is growing cloud the fastest at the cheapest multiple. That makes our 24/7 Wall St. price target look conservative given the setup.
Google Price Prediction 2026-2030
My verdict is a high-conviction buy with 90% confidence and a 24/7 Wall St. price target of $504.21. The scale tipper is valuation: a P/E of 14 for a business compounding revenue at 24% with accelerating cloud economics is a rare setup.
The setup strengthens if cloud growth holds above 50% into Q3, and weakens if free cash flow stays negative into 2027 without a corresponding backlog conversion.
Looking further ahead, here is where our model projects Google could trade, assuming current trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $366 |
| 2027 | $504 |
| 2028 | $668 |
| 2029 | $804 |
| 2030 | $906 |
These projections assume Google continues executing on Cloud, Gemini, and Search. Meaningful upside or downside could come from AI infrastructure returns, regulatory actions, or the timing of TPU revenue recognition. All of that capex has to be powered, cooled, and networked by somebody, and we profiled seven of those suppliers in a free report on the AI infrastructure buildout.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.