Rocket Lab Poised to Become “Only Viable Alternative” to SpaceX, Says Cantor Fitzgerald
Cantor Fitzgerald just named Rocket Lab the only listed stock that can challenge SpaceX at scale, but the path to a $122 price target runs through an unflown rocket and a multibillion-dollar acquisition still waiting to close.


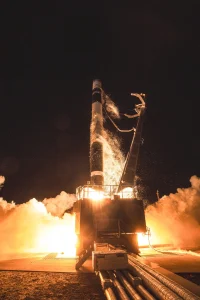
Cantor Fitzgerald analyst Andres Sheppard reiterated an Overweight rating and $122.00 price target on Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction), calling the current level an attractive entry point ahead of the Neutron rocket’s debut. The firm argues Neutron is uniquely positioned to become the only viable alternative and most direct commercial competitor to SpaceX’s Falcon 9 once operational. For long-term investors, the call frames Rocket Lab stock as the clearest listed proxy for the commercial space buildout.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| RKLB | Rocket Lab USA | Cantor Fitzgerald | Reiterated | Overweight | Overweight | $122.00 | $122.00 |
Inside the Cantor Fitzgerald Thesis
Sheppard’s bullish stance follows Rocket Lab’s September 15 announcement of secured funding for the Iridium acquisition. Cantor models the combined company will double annual revenue once the deal closes, cementing an end-to-end space platform spanning launch, satellites and services. On Neutron, management is targeting an average selling price of $50 million to $55 million per launch and up to 20 launches per engine, with first flight targeted for later this year.
Rocket Lab by the Numbers
Q2 FY26 revenue reached a record $234.07 million, up 62.0% year-over-year, with product revenues nearly doubling. Non-GAAP gross margin expanded to 41.5%, and backlog grew 137% to $2.36 billion, including more than 90 launches. CEO Peter Beck highlighted “more than $1 billion in new contracts across launch and space systems already entered into in Q3”, including a $397 million Flatellite award for the U.S. Space Force SB-AMTI program. Guidance calls for Q3 revenue of $250 million to $265 million.

How It Stacks Up Against SpaceX
| Ticker | Company | Rating | Price Target |
|---|---|---|---|
| RKLB | Rocket Lab | Overweight (Cantor) | $122.00 |
| SPCX | SpaceX (NASDAQ:SPCX) | Not analyst-rated peer | N/A |
SpaceX remains the industry benchmark, delivering $7.8 billion in Q2 revenue, up 92%, with Elon Musk noting Falcon carries “80 to 90% of total Earth mass to orbit per year.” Cantor’s point is scarcity value: Rocket Lab is the only listed pure-play credibly building a scaled second source.

Why the Timing Matters
Rocket Lab shares trade at $67.35, off 11.19% over the past month but up 42.75% over one year, with a market cap near $40.3 billion. The 52-week range of $37.57 to $151 underscores the volatility. The Space Force’s FY 2027 budget request of $71.2 billion names Rocket Lab as an NSSL prime contractor, reinforcing the demand backdrop.

What It Means for Your Portfolio
Retirement-focused investors should weigh the upside of a scarce SpaceX alternative against real execution risks: Neutron timeline slippage, integration of Mynaric, Motiv and the pending Iridium acquisition, and continued GAAP losses funded by equity raises. Rocket Lab stock warrants research as a long-duration space infrastructure holding, sized to reflect its beta of 2.612.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.