Warren Buffett’s Succession Triggers Search for His Spiritual Successors
Warren Buffett's step back from Berkshire forces a harder question: which public companies actually run his playbook, and how close do any of them get to the real thing?

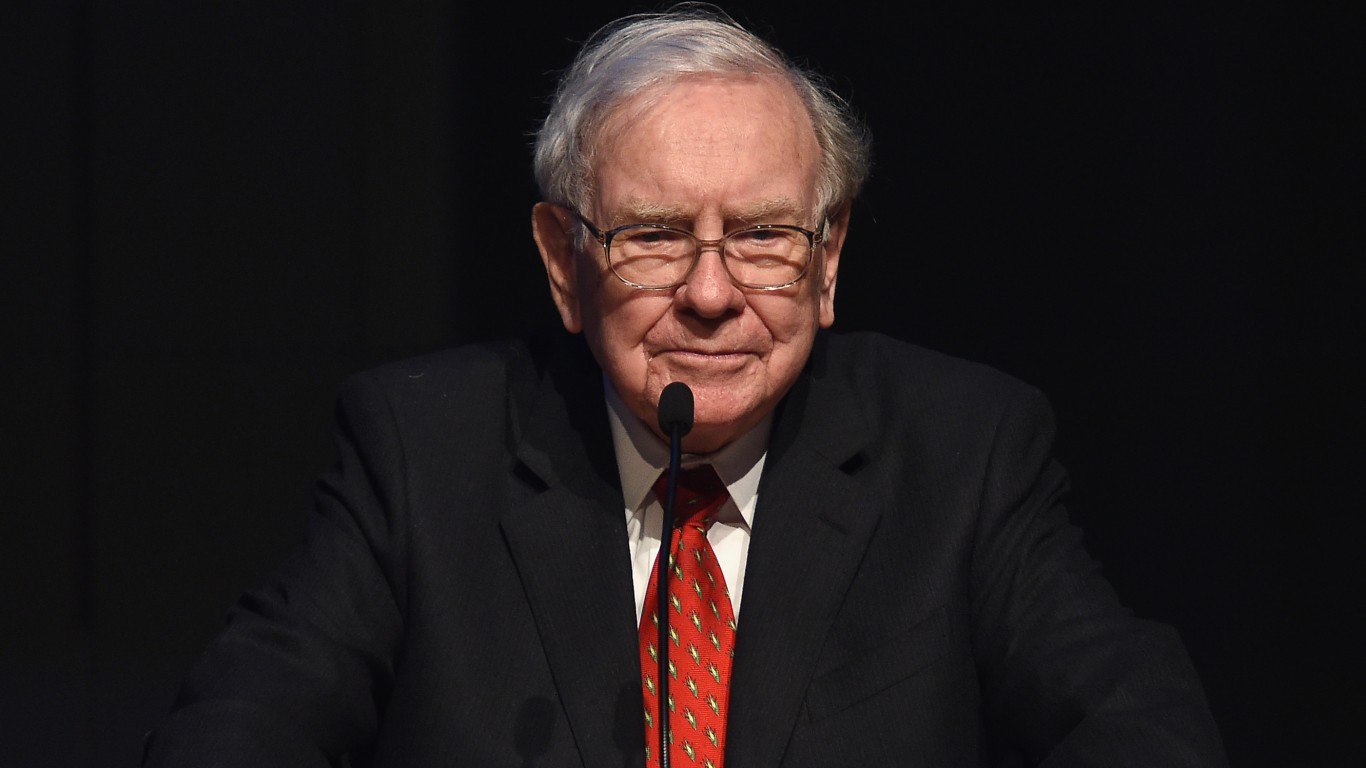
The question of who inherits Warren Buffett’s mantle became more than a parlor game this past weekend. It has been widely reported that Howard Buffett was elected board chair of Berkshire Hathaway as Warren Buffett took another step back. With Greg Abel already running operations, the succession is no longer hypothetical, and investors are once again asking which public companies actually embody Buffett’s playbook: a durable moat, owner-operator alignment, disciplined capital returns, a real margin of safety, and the patience to compound quietly for years.
Below are four public companies that capture Buffett’s discipline, ranked from closest cousin to the benchmark itself.
4. A Broker Buffett Nearly Owned
Berkshire once held a major stake in a potential acquirer of Willis Towers Watson (NASDAQ:WTW | WTW Price Prediction) but ultimately the deal collapsed. Insurance broking is a capital-light, recurring-revenue business with a wide client moat. Q2 FY26 delivered adjusted diluted EPS of $3.35, up 17%, on revenue of $2.466 billion, up 9.1% year over year, with the adjusted operating margin expanding 100 basis points to 19.5%. Management’s “Propel” AI plan targets roughly $625 million in investment for about $350 million in net run-rate savings and a 30% adjusted operating margin by 2028. The board added $1.5 billion to buyback authority, and diluted share count fell from 100 million to 94 million year over year.
Where it breaks the mold: The stock has stumbled lately. Shares are down 5.7% year to date and 6.6% over the past year, and the Newfront integration is dragging GAAP earnings.


3. The Deep-Value Cyclical
Warrior Met Coal (NYSE:HCC) is the unloved commodity name value investors circle when pricing aligns. Q2 FY26 was a breakout: adjusted diluted EPS of $3.35 beat the $3.15 consensus, revenue of $509.69 million rose 71.3% year over year, sales volumes hit a record 3.7 million short tons, and adjusted EBITDA margin expanded to 30.8% from 18.0%. Free cash flow swung to $103.35 million from negative $56.70 million a year earlier as the $1.02 billion Blue Creek mine came fully online. CEO Walt Scheller said: “This second quarter marked the start of the next phase of Warrior’s growth, which is focused on free cash flow generation, balance sheet strength, and long-term stockholder returns.”
Where it breaks the mold: Buffett avoids commodity price-takers. Warrior’s one-year return of 37.8% reflects the volatility Buffett spent a career avoiding.


2. The Florida Land Bank
St. Joe (NYSE:JOE) is the long-duration land play Bruce Berkowitz championed for years. Q2 FY26 was the best in two decades: revenue of $158.8 million was up 23% year over year, net income of $40.5 million was up 37%, and EBITDA of $69.7 million was up 24%. The pipeline includes 25,000-plus homesites, with Park Place East (~2,000 units) newly approved. Capital allocation was 43% buybacks in the quarter, reducing the share count to 56,991,651 — the lowest since 1997. CEO Jorge Gonzalez called it “the highest net income for a second quarter in our history.”
Where it breaks the mold: Buffett avoids single-asset geographic concentration. St. Joe is one weather system and one Florida housing cycle away from a different narrative. Shares are up 22.4% over the past year, but the thesis rests on patience most funds no longer have.


1. The Benchmark Itself
Berkshire Hathaway (NYSE:BRK-B) remains the benchmark. Market cap stands near $1.1 trillion, with a P/E of 13x, P/B of 1.4x, and debt/equity of 0.19. Q2 FY26 operating earnings rose to $12.98 billion from $11.16 billion, and Berkshire became a net buyer of stocks for the first time in over three years, deploying roughly $23.5 billion including a $10 billion private placement in Alphabet, plus about $4.5 billion of its own shares repurchased. The $380 billion cash position as of Q1 is the permanent-capital advantage peers cannot replicate.
Where it breaks the mold: Berkshire is breaking its own mold. With Howard Buffett elected board chair, the company that defined owner-operator alignment for six decades is executing the succession.


How the Buffett Filter Held Up
Willis Towers Watson brings recurring cash flows and buyback discipline; Warrior Met brings low-cost producer economics; St. Joe brings the intrinsic-value gap and share-count shrinkage; and Berkshire brings all of it plus the float. Each breaks from Buffett somewhere concrete. Shares of Berkshire are up 1.4% year to date and 84.2% over five years, a reminder that the original playbook still compounds. (For readers who would rather borrow Buffett’s homework directly, we sorted Berkshire’s own holdings by valuation and pulled the seven cheapest dividend payers into a free report you can grab here.)
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.