We Think Meta Could Keep Soaring Higher and Wells Fargo Agrees
Wells Fargo just handed Meta a dramatically higher price target, and the reasoning behind it points to something bigger than a routine upgrade. Here is why one analyst believes the AI story at Meta is only getting started.

Meta Platforms (NASDAQ:META | META Price Prediction) just got a fresh vote of confidence from Wells Fargo, which raised its price target on Meta Platforms to $796 from $640 and reiterated an Overweight rating.
The firm argues that heading into Meta Connect, product momentum from recent model releases and early traction on the Meta Muse assistant gives the company a genuine AI story to tell.
For long-term investors, the price target raised by Wells Fargo reinforces a bull case that has been quietly rebuilding as Meta stock rallies off its August lows.
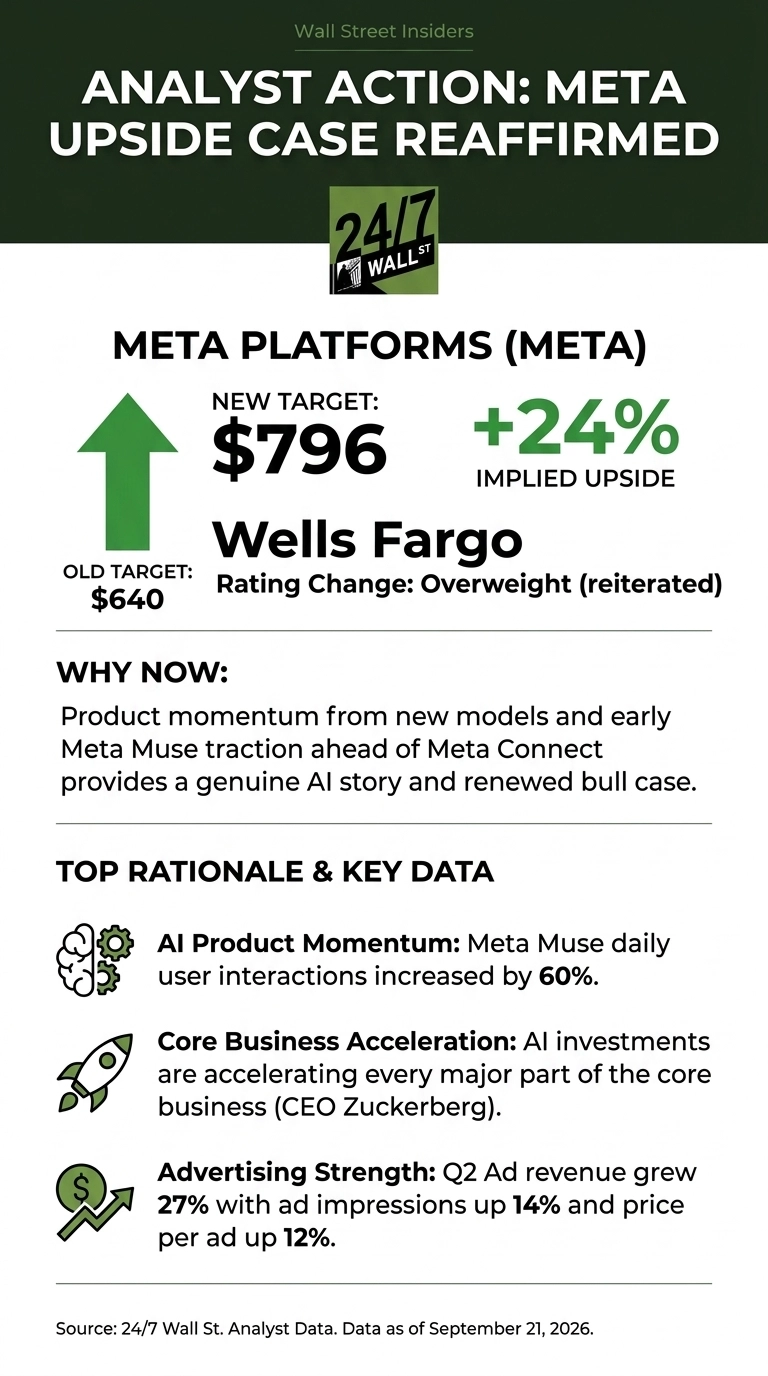

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| META | Meta Platforms | Wells Fargo | Price Target Raised | Overweight | Overweight | $640 | $796 |
Wells Fargo’s Case
Wells Fargo’s thesis centers on product momentum following successful model releases and early traction on the Meta Muse assistant. The firm expects investor attention at Meta Connect to zero in on usage statistics for Muse and Meta’s newer models.
That framing aligns with commentary from CEO Mark Zuckerberg, who told analysts on the Q2 call that “we are now at a point where our investments in AI are accelerating every major part of our core business.”
Since Muse Spark was integrated, Meta reported a 60% increase in daily users interacting with the assistant. Wells Fargo analyst Ken Gawrelski pressed management on the same capacity and model strategy questions now underpinning the higher target.
Company Snapshot
Meta operates the world’s largest advertising franchise across Facebook, Instagram, WhatsApp and Messenger, with a market capitalization of roughly $1.7 trillion.
Q2 2026 revenue rose to $60.80 billion, up 27.96% year over year, though diluted EPS of $6.18 missed the $7.22 consensus as costs climbed 55% on $2.40 billion in legal charges and $1.18 billion in severance.
Advertising revenue grew 27%, with ad impressions up 14% and price per ad up 12%. Management guided Q3 revenue to $61 billion to $64 billion and full-year capex to $130 billion to $145 billion.

Why the Move Matters Now
Meta stock trades around $715.43, up 31.02% over the past month and 10.4% in the past week, yet still 8.01% below year-ago levels.
That gap reinforces the long-term bull case behind Wells Fargo’s target. Shares change hands at a trailing P/E near 25 and a forward P/E of roughly 20, with the Street consensus target sitting at $755.28 across 47 Buy and 8 Strong Buy ratings versus 7 Holds.
The 2027 consensus EPS estimate of $33.94 gives Wells Fargo’s higher target real earnings support if Muse and business agents scale as guided.

What It Means for Your Portfolio
The Wells Fargo call reinforces the bull case for long-term holders even as near-term risks remain.
The near-term risks are real, including a compressed 31% operating margin and free cash flow that fell to $784 million under an 82.1% capex surge.
The next catalyst to watch is Meta Connect, particularly whether it delivers on the Muse usage metrics Wells Fargo expects.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.