This Under-the-Radar Chip Company Could Have a Much Bigger Future
Rambus sits inside nearly every next-generation server memory module yet trades at a fraction of its flashier chip rivals, and its roadmap through 2027 could force the market to finally pay attention.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Memory interface specialist Rambus (NASDAQ:RMBS | RMBS Price Prediction) flies under the radar versus the marquee AI names, yet its silicon sits inside almost every next-generation server memory module. With DDR5 ramping, HBM4E in design at hyperscalers, and PCIe 7 IP licensing kicking in, the setup for the next 12 months looks compelling.
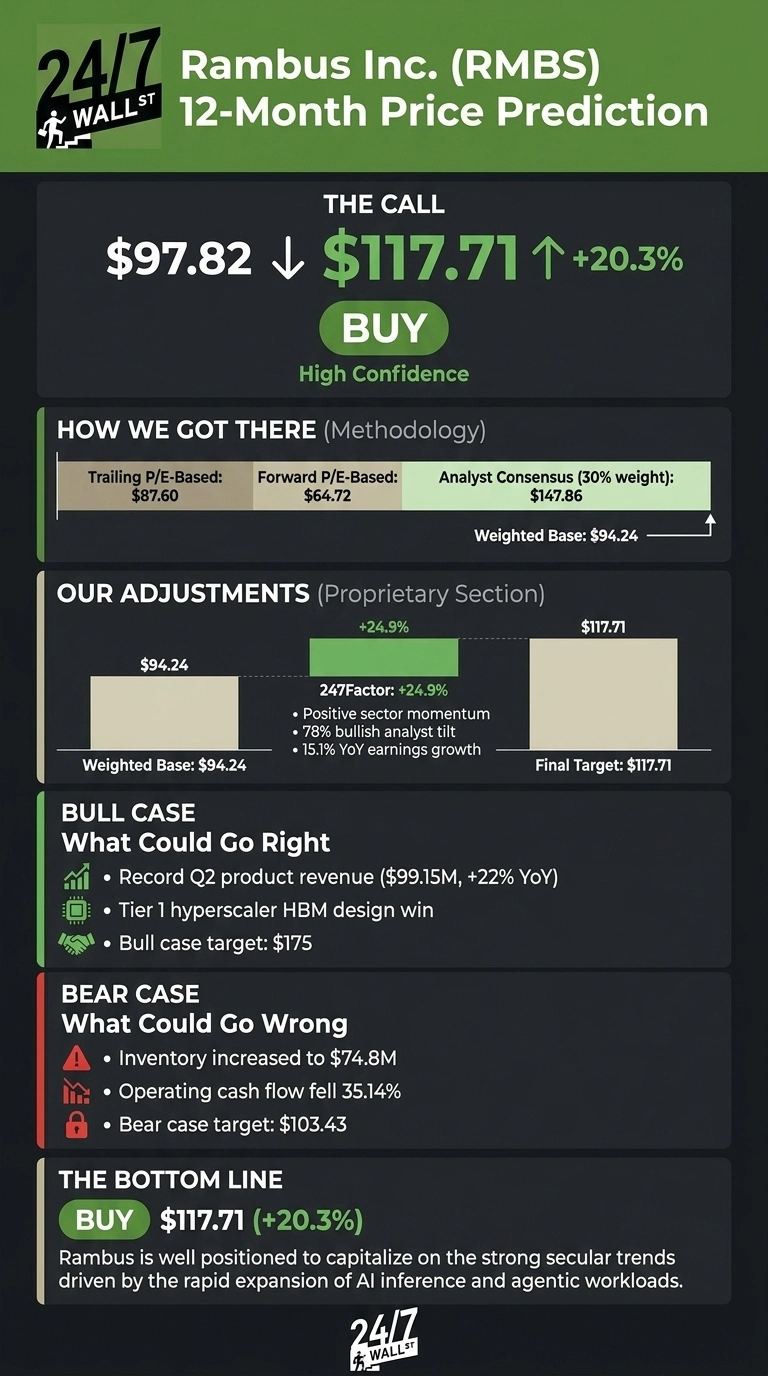
Our 24/7 Wall St. price target for Rambus is $117.71, roughly 20.3% above where shares trade today. We rate the stock a buy with high confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $97.82 |
| 24/7 Wall St. Price Target | $117.71 |
| Implied Upside | 20.3% |
| Recommendation | BUY |
| Confidence | 90% |
Rambus is compounding product revenue at a 20%+ clip while layering in high-margin licensing wins that will not fully show up in the P&L until 2027.
A Sharp Rebound After a Rough Summer
RMBS rose 11.67% in Monday’s session and is up 12.48% over the past week, though still down 8.9% over the last year and well below its 52-week high of $174.10.
The bounce follows strong Q2 FY2026 results. Revenue hit $207.38 million, up 20.4% year over year, beating consensus by 4.58%. Non-GAAP EPS of $0.77 topped estimates by 7.69%. CEO Luc Seraphin noted Rambus is “well positioned to capitalize on the strong secular trends driven by the rapid expansion of AI inference and agentic workloads.”

Why Bulls See a Breakout Above $150
The bull case rests on three legs. Product revenue hit a record $99.15 million in Q2, up 22% YoY, with Q3 guidance of $110M to $116M. Rambus disclosed a design win with a Tier 1 U.S. hyperscaler for next-generation HBM, structured as a licensing deal recognizing revenue before end products ship. Management expects Silicon IP to grow 10% to 15% annually.
The Street’s mean target of $147.86, backed by 7 Buy and 2 Hold ratings, implies a bull scenario near $175 if MRDIMM and PCIe 7 licensing ramp on schedule in 2027.

What Could Go Wrong
Inventory jumped to $74.8 million from $44.1 million at year-end 2025, and operating cash flow fell 35.14%. Forward P/E of 24 looks full for a memory-cycle-exposed business.
However, management said it is “building strategic inventory” for Q3, Q4, and early 2027 ramps. Bear scenario: $103.43.
How Rambus Compares to Marvell, Synopsys, and Lattice
Marvell Technology (NASDAQ:MRVL) trades at a forward P/E of 58 with 36.5% YoY revenue growth. Rambus’s 24 forward P/E looks cheap by comparison.
Synopsys (NASDAQ:SNPS) overlaps the silicon IP business at a forward P/E of 22 on 42.4% revenue growth, validating our target.
Lattice Semiconductor (NASDAQ:LSCC) trades at a richer forward P/E of 35, suggesting the market rewards specialized chip franchises with an AI angle.
| Company | Forward P/E | Rev Growth YoY |
|---|---|---|
| Rambus | 24 | 20.4% |
| Marvell | 58 | 36.5% |
| Synopsys | 22 | 42.4% |
| Lattice | 35 | 62.2% |
Rambus Setup and Verdict
The 24/7 Wall St. price target of $117.71 with 90% confidence is a buy. The bull path holds if MRDIMM adoption ramps into 2027 and the hyperscaler HBM design win seeds broader licensing revenue.
The setup weakens if DRAM tightness cuts product shipments or inventory unwinds without demand pull. The valuation is undemanding and the roadmap is loaded.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $117.71 |
| 2027 | $118.23 |
| 2028 | $139.72 |
| 2029 | $166.44 |
| 2030 | $185.09 |
These projections assume Rambus continues executing on DDR5, HBM4E, and PCIe 7 licensing. Significant upside or downside could result from hyperscaler custom-silicon share shifts or a memory market downturn.
Rambus fits the pattern of specialized chip franchises that compound quietly before the market notices, the same setup we cataloged in a free playbook on spotting the next big semiconductor winner early: here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.