Prediction: Rambus Could Be a Quiet Winner From Exploding AI Demand
Rambus sits far below its 52-week high while AI server builders keep adding racks that depend on its chips. Whether the stock is a overlooked opportunity or a value trap comes down to a few critical revenue milestones in the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
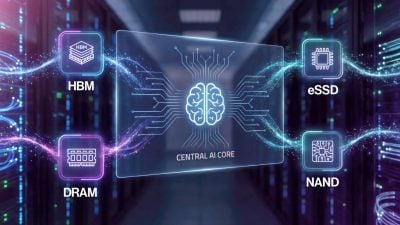
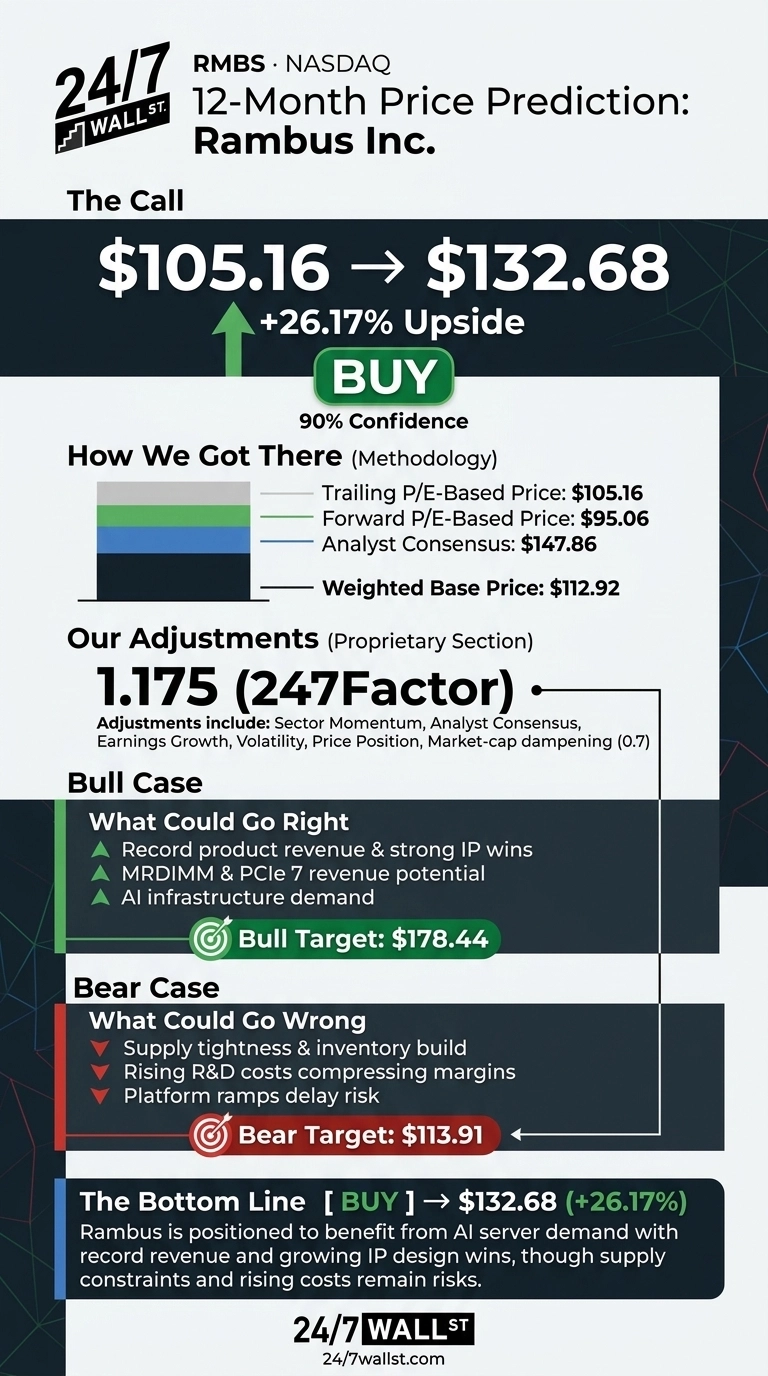
Rambus (NASDAQ:RMBS | RMBS Price Prediction) makes the memory interface chips and silicon IP that keep AI servers supplied with data. The 24/7 Wall St. price target for Rambus is $132.68. That means 26.17% upside from the last close of $105.16.
| Metric | Value |
|---|---|
| Current Price | $105.16 |
| Price Target from 24/7 Wall St. | $132.68 |
| Upside/Downside | 26.17% |
| Recommendation | BUY |
| Confidence Level | 90% |
On Monday the shares fell 4.78% to $100.13. At that price, the upside to our target grows to about 32.5%. The model rates the stock a buy with high confidence. It rests on record product revenue and a business mix that benefits from every new AI server rack.

Record Revenue and a 14% Weekly Rebound Put Rambus Back in Play
Over the past week, Rambus gained 14.3%. It is up 11.22% over the past month and 8.97% year to date. The one-year return is still -0.63%. In mid-June the stock traded at $143.29, and today it stands about 42.5% below its 52-week high of $174.1.
Fiscal Q2 revenue rose 20.43% to $207.38 million, ahead of the $198.30 million estimate. Non-GAAP EPS of $0.77 exceeded the $0.715 expected. Product revenue hit a record $99.15 million. Management also reported “an exciting design win with a Tier 1 US hyperscaler for next-generation HBM in future AI chips.”
Why Bulls See $178 on the Horizon
The bull case depends on growing chip content per server. Rambus launched DDR5 9600 chipsets and expects MRDIMM to become “a material opportunity”, with significant sales starting in 2027. Revenue from PCIe 7 switch IP is expected in the coming quarters, and management sees silicon IP growing 10% to 15% a year.
Rambus is one of the picks-and-shovels names that benefits every time a hyperscaler adds a rack (we profiled seven of these AI infrastructure suppliers, from power to memory interfaces, in a free report you can grab here). Of the analysts covering the stock, 7 rate it a buy and 2 rate it a hold. Our bull scenario reaches $178.44.

Supply Tightness and Rising Costs Could Cap the Rally
Inventory rose to $74.8 million from $44.1 million, and operating cash flow fell 35.14%. Management says the inventory is strategic stock for ramps planned in Q3, Q4 and early next year.
In Q1, R&D rose to $50.23 million and pressured the non-GAAP operating margin to 42%, although that spending funds the roadmap. Management expects supply constraints to last into 2027. Our bear case of $113.91 still stands above today’s price.

Rambus Sits Between Micron’s Bargain Multiple and Marvell’s Premium
The direct read on memory demand is Micron (NASDAQ:MU), because its DDR5 and HBM volumes drive Rambus royalties. It trades at 7 times forward earnings after fiscal Q3 revenue jumped 345.72%. That low multiple reflects cyclical peak earnings, while Rambus’s licensing model is steadier.
Marvell (NASDAQ:MRVL) competes for the same hyperscaler custom silicon spending. It trades at 62 times forward earnings, with data center making up 79% of revenue.
| Company | Forward P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Rambus | 30 | 20.43% |
| Micron | 7 | 345.72% |
| Marvell | 62 | 36.55% |
At about half of Marvell’s multiple, Rambus looks reasonably priced, and the peer group suggests our target is reasonable.
Rambus Price Prediction 2026-2030
The 24/7 Wall St. price target of $132.68 accounts for a buy rating at 90% confidence. Record product revenue coupled with growing IP design wins tips the scale.
I’d turn more constructive if Q3 product revenue lands within the $110 million to $116 million guidance. I’d turn wary should supply limits push MRDIMM ramps past 2027. In my view, the risk-reward favors patient holders.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $111.13 |
| 2027 | $137.62 |
| 2028 | $158.56 |
| 2029 | $174.55 |
| 2030 | $189.69 |
The projections assume Rambus keeps executing on its DDR5 and IP roadmap. A faster HBM licensing ramp could raises them, and a sharp downturn in the DRAM cycle could push them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.