Wall Street’s Palantir Price Targets Tell an Interesting Story
Palantir has gone from ice cold to white hot in a matter of weeks, and Wall Street analysts cannot agree on what that rally is actually worth. The gap between the most bullish and most bearish targets reveals a fundamental…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Palantir is one of Wall Street’s most debated names. The analyst target spread tells the story.
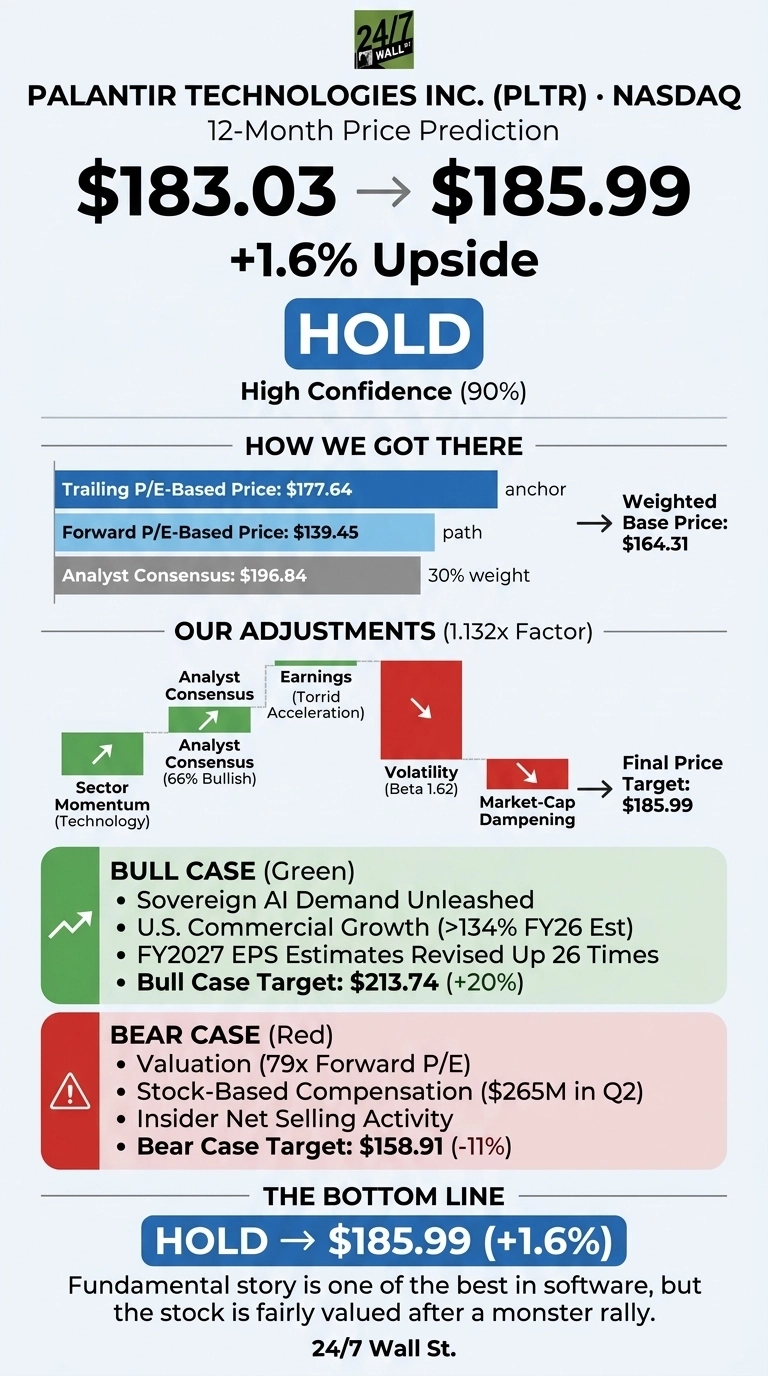
Palantir (NASDAQ:PLTR | PLTR Price Prediction) trades at $183.03 intraday. Our 24/7 Wall St. price target is $185.99 over 12 months, implying 1.6% upside. Recommendation: Hold at 90% confidence. Shares are fairly valued after a monster rally, but the fundamental story remains one of the strongest in software.
 1
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $183.03 |
| 24/7 Wall St. Price Target | $185.99 |
| Upside | 1.6% |
| Recommendation | HOLD |
| Confidence Level | 90% |

From June Lows to a Fresh Melt-Up
PLTR hit a 52-week low of $106.37 before rallying to $207.52. The stock is up 9.45% over the past week and 2.97% year to date.
Jim Cramer noted Palantir was “white hot in late 24 and most of 2025 before getting ice cold for the first half of this year and only recently turned hot again, rallying more than 60% from its June lows.” UBS named PLTR a top tech pick this week.
Q2 FY2026 delivered EPS of $0.41 versus $0.28 consensus, revenue of $1.935 billion up 92.83% year over year, and a Rule of 40 score of 155%. U.S. commercial revenue jumped 149%.
Why Bulls See a Breakout Ahead
The bull case rests on sovereign AI. CEO Alex Karp said “Demand for AI sovereignty has now been unleashed” and committed to “driving the business to grow at a rate equal or above to what we have in U.S. commercial for the next 18 months.”
Total remaining deal value hit $13.1 billion, net dollar retention reached 157%, and adjusted free cash flow ran at 63% margin. FY2027 EPS estimates have been revised up 26 times in 30 days with zero cuts. Bull scenario points to $213.74, roughly 20% above spot.

What Could Go Wrong
Valuation is the obvious risk. PLTR trades at a forward P/E of 79x and trailing P/E of 152x, leaving no margin for a growth stumble. Stock-based comp of $265 million in Q2 dilutes shareholders, and insiders have been net selling.
However, Q2 net income rose 225.01% year over year, and insider selling largely reflects mechanical 10b5-1 activity. Multiple compression toward peers puts the bear scenario at $158.91, or roughly 11% downside.

Palantir Price Prediction 2026-2030
24/7 Wall St. price target for Palantir: $185.99, Hold, 90% confidence. The fundamental story is one of the best in software, but the stock has priced in a very good outcome.
The 200-day sits at $151.75 as a technical reference for margin of safety. Watch for revenue growth decelerating below 60% or the Rule of 40 slipping under 120. For now, the setup favors patience.
Extending the model forward, here is where we project PLTR could trade, assuming the current growth trajectory holds and multiples gradually normalize.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $185.99 |
| 2027 | $186.92 |
| 2028 | $191.42 |
| 2029 | $201.09 |
| 2030 | $220.93 |
These projections assume Palantir continues executing on sovereign AI demand and U.S. commercial expansion. Significant upside or downside could come from federal budget shifts, an AI capex reset, or a re-rating of software multiples.
That buildout also has to be powered, cooled, and networked by somebody, and we pulled together seven suppliers doing exactly that in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.