AMD Joined Nvidia in the Trillion Dollar Club. The Run Isn’t an Accident
AMD just crossed a threshold only one other chip company has ever reached, but the rally into that milestone raises a harder question about what the stock is actually worth from here.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
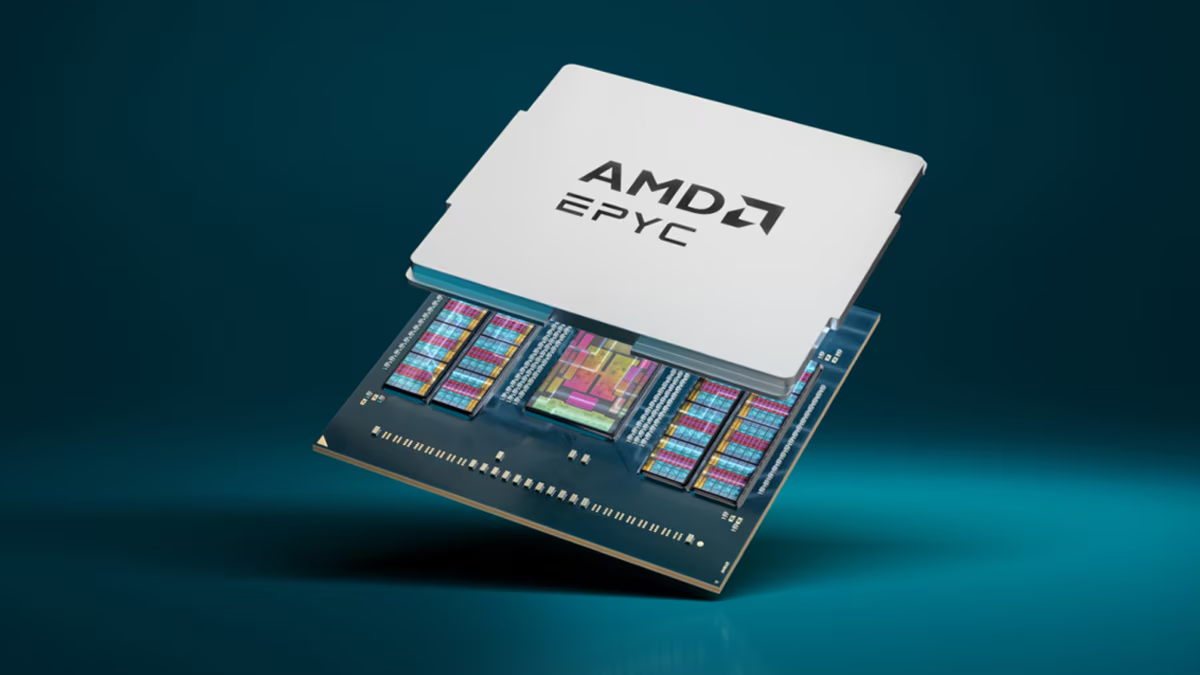
AMD (NASDAQ:AMD | AMD Price Prediction) just punched its ticket into the trillion-dollar club, joining NVIDIA (NASDAQ:NVDA) as the only pure-play AI silicon names above that mark. Shares are $616.69, up 291.82% over the past year.
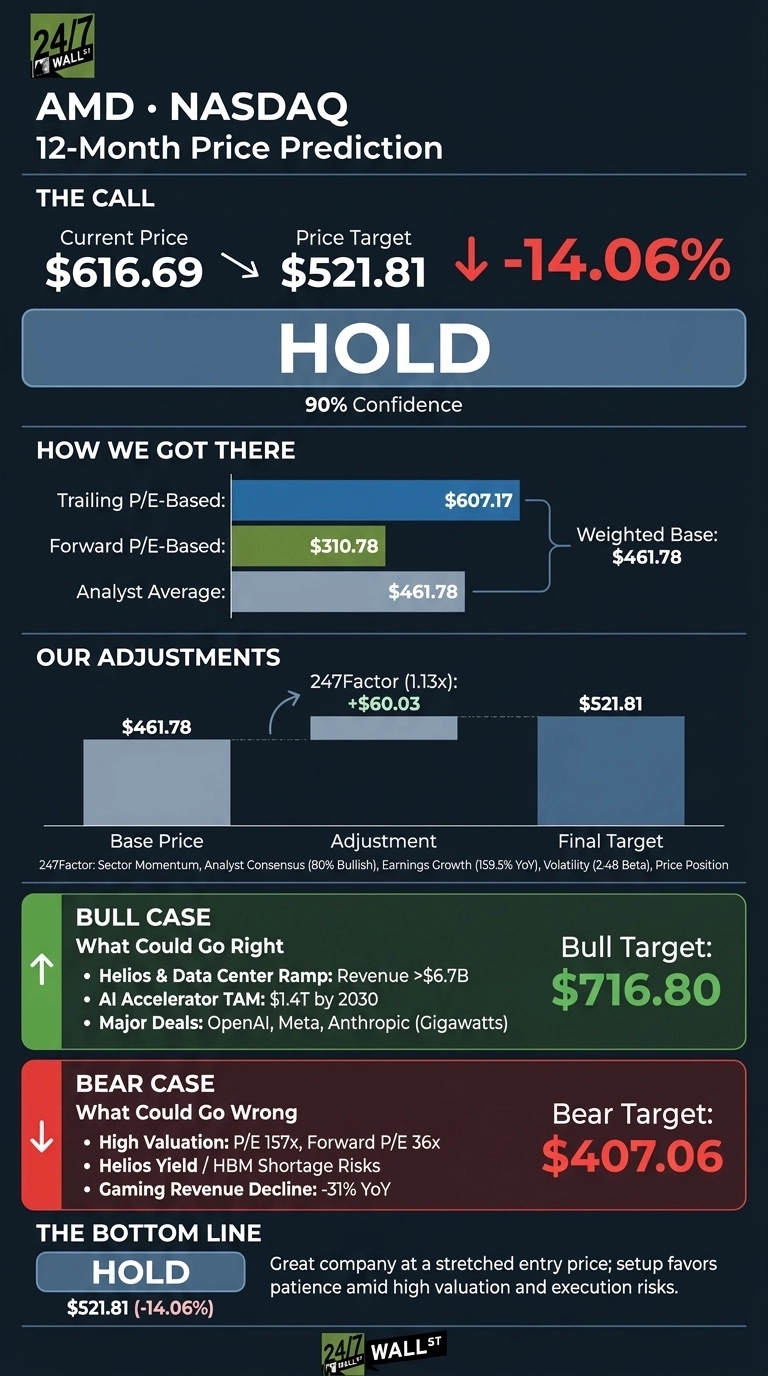
Our 24/7 Wall St. price target for AMD is $521.81, implying 14.06% downside over the next 12 months. The call is hold with 90% model confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $616.69 |
| 24/7 Wall St. Price Target | $521.81 |
| Upside/Downside | -14.06% |
| Recommendation | HOLD |
| Confidence | 90% |
Why We Could Be Wrong
Our 24/7 Wall St. price target sits below the current quote, and we want to be upfront about that.
AMD is one of the most divisive stocks in the market right now, and the gigawatt-scale commitments from OpenAI, Meta, and Anthropic could drive numbers materially above consensus. Treat the target as one datapoint. The bull case below outlines exactly how AMD could blow through it.
A Five-Day Rally Into the Trillion Club
AMD ripped 24.99% in a week and 30.31% in a month, hitting a fresh 52-week high of $616.69.
Q2 FY26 revenue was $11.54 billion, up 50.11% year-over-year, beating the $11.31 billion consensus. Non-GAAP EPS of $1.66 topped estimates by 3.06%. Data Center revenue reached $6.72 billion, up 107%. Management guided Q3 to roughly $13 billion.

Bull Case for $700+
Bulls have a legitimate roadmap. Lisa Su told investors AMD expects server revenue to grow more than 80% year-over-year in the second half of 2026 and the Data Center segment to more than double in 2027. Anthropic will deploy up to two gigawatts of MI450 GPUs in Helios racks starting in the first half of 2027.
Management sees the AI accelerator TAM reaching $1.4 trillion by 2030. If Helios ramps cleanly and forward EPS re-rates toward $12-$14, upside in the $697 to $720 range becomes reasonable (we reverse-engineered what past monster winners looked like early in a free Next Nvidia playbook).

What Could Go Wrong
AMD trades at 157x trailing and 36x forward. Helios yield slip, HBM shortage, or China export restriction could compress the multiple. Gaming revenue fell 31% in Q2.
Insider activity has been net selling. A bearish path lands near $407. Elevated capex reflects the Instinct ramp, and free cash flow grew 129.48% in FY25.

How AMD Compares to NVIDIA and Broadcom
NVIDIA is the direct AI accelerator comp. Nvidia carries a $5.37 trillion market cap on 28x trailing and 25x forward earnings, with a 66.2% operating margin. AMD’s forward multiple of 36x sits at a premium to Nvidia’s despite superior profitability, a headwind for the bull case.
Broadcom (NASDAQ:AVGO) is the closest AI infrastructure valuation comp, sitting at $1.73 trillion on 19x forward earnings with a 54.3% operating margin. Broadcom’s custom silicon franchise trades at roughly half AMD’s forward multiple. That contrast is what pushes our 24/7 Wall St. price target below the current quote. Against this peer set, $521.81 looks fair.
AMD Price Prediction 2026-2030
The setup favors patience: a strong Q3 print and clean Helios yield progression would reinforce the bull case, while stalled forward EPS revisions or tighter China policy would validate caution. The $521.81 target and hold rating reflect a great company at a stretched entry price.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $576.13 |
| 2027 | $487.88 |
| 2028 | $509.49 |
| 2029 | $470.69 |
| 2030 | $473.28 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.