JPMorgan Predicts IREN Will Generate $24 Billion in Annual Revenue by 2030
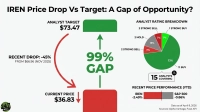
JPMorgan just flipped its IREN rating from Underweight to Overweight and attached a price target that implies the company barely exists yet relative to what it could become, and the math behind that call raises a question every investor in…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

A $24 Billion Forecast That Changes How IREN Looks
$24 billion. That is how much annual revenue JPMorgan (NYSE:JPM | JPM Price Prediction) projects IREN (NASDAQ:IREN) will bring in by 2030. It is an analyst projection. It is not a reported result, and it is not company guidance. For comparison, IREN reported $707.00M in revenue for its full fiscal 2026, which ended in June.
The bank’s model has IREN reaching about 2,065 MW of capacity by the end of the decade. It assumes roughly $13M revenue per MW and EBITDA margins near 65%. The forecast came alongside a double upgrade to Overweight from Underweight and a price target raised to $65.
What JPMorgan’s Math Says About the Business
IREN began as a Bitcoin miner. It is now turning into a vertically integrated AI cloud provider that has its power, land, data centers, GPUs and software. Management expects mining to be effectively decommissioned by the end of December 2026. The new business is already growing fast. AI Cloud Services revenue reached $128.8M for FY26, roughly 8x the prior year. In the June quarter, AI Cloud brought in $70.50M, more than double the previous quarter, and passed Bitcoin mining’s $66.70M.
The company has the physical room to grow. IREN has a data center pipeline of more than 5GW across North America, Spain and Australia (we featured seven of the non-chipmaker companies driving exactly this kind of AI data-center expansion in a free report you can grab here). Co-CEO Daniel Roberts put it this way: “The $4 billion of ARR comes from less than 10% of our five gigawatt-plus portfolio of secured grid connections.” ARR (annualized recurring revenue) is the annual revenue that signed contracts produce once they are running.
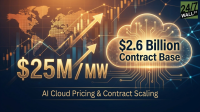
The pricing assumption stands out. Recent three-year contracts pay more than $20M revenue per MW (IT), and management is in active talks at about $25M per MW (IT). JPMorgan’s roughly $13M per MW is well below those figures. Commentary accompanying the note says that using the higher figure on the same megawatt base would point to $50B+ in revenue potential.
Wall Street’s published estimates stop well short of 2030. The average fiscal 2028 revenue estimate is about $7.56 billion, from 16 analysts.
How Shares Traded Around the Research Notes
IREN closed at $44.13 on September 25, 2026. That was a 1-day drop of 4.39% and a one-week decline of 5.47%, as neocloud stocks sold off after a week of research notes. Over longer periods, the stock is up 11.48% over one month and 16.83% year to date. Over one year it is down 4.68%. The 52-week range runs from $28.93 to $76.87, so long-term holders should expect big price swings.
Bull Case: Scarce Power Turning Into Contracted Revenue
The contracts behind the forecast are already signed. IREN had $1.00 billion in ARR as of August 26, 2026, and targets $4.00 billion in ARR by December 31, 2026. Its largest customers include Microsoft (NASDAQ:MSFT), under a $9.7B contract, and NVIDIA (NASDAQ:NVDA), under a $3.4B five-year AI Cloud contract that comes with an NVIDIA investment of up to $2.1B. Cohere, Perplexity, Figure AI and an unnamed leading AI lab have also signed on. As Roberts said, “The most sophisticated buyers of AI infrastructure in the world keep choosing us.”
Customers are also helping pay for the expansion. IREN reports $14.00 billion in committed GPU financing and prepayments. Customer prepayments now cover 45% to 55% of GPU capex, and 100% of its data centers are currently unencumbered, meaning they carry no debt against them.
The costs of this shift are high, and they are already showing up in the numbers. FY27 capex guidance is $25 to $30 billion. The June-quarter net loss was $684.00M, which included a $450.40M non-cash impairment on retired mining hardware. JPMorgan’s number assumes IREN keeps executing on every front.
Bottom Line for Long-Term Holders
Proof comes soon. Horizons 2 through 4, the remaining 50MW Microsoft deployments, are targeted for the December quarter, and IREN aims to deliver 0.8GW (IT) in 2027. If each deployment turns signed ARR into reported revenue on schedule, the path to $24 billion becomes easier to trace one megawatt at a time.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.