IREN Limited Fell by 33% in 2026 But 3 Analysts Believe It Will Nearly Quadruple in Price From Here
A neocloud panic wiped out a third of IREN's value in months, yet every analyst covering the stock refuses to issue a sell rating. The reason comes down to a set of signed contracts that tell a very different story…

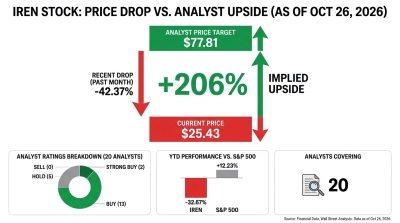
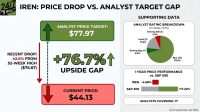
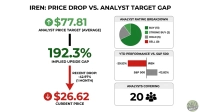
The stock, IREN (NASDAQ:IREN), currently trades at $25.43, while the average analyst price target sits at $77.81. Roughly 206% of upside would follow if Wall Street is right.
IREN runs data centers and is nearly done moving from Bitcoin mining to AI cloud, leasing GPUs to hyperscalers and AI labs. Marquee deals with Microsoft (NASDAQ:MSFT | MSFT Price Prediction) and NVIDIA (NASDAQ:NVDA) include a $9.7B multi-year Microsoft AI Cloud contract and a $3.4B five-year NVIDIA AI Cloud contract plus up to $2.1B of NVIDIA investment.
The top of the target range is even more aggressive. Bernstein’s Gautam Chhugani holds a $100.00 target, and Northland’s Nehal Chokshi and Cantor Fitzgerald’s Brett Knoblauch sit at $99.00 each. Bernstein’s figure points to about 293% of upside, close to a quadruple.
A Neocloud Panic Turned a Rough Year Into a Collapse
The biggest damage came in the past month, when IREN shares fell 42.37% during a sector-wide neocloud selloff. A Gartner report predicted more than 80% of neocloud GPU-rental providers will cease operating as independent businesses by 2030, setting off a multi-session rout. Elon Musk then said more than 200 neoclouds face “guppy-level death”. Year to date, the stock is down 32.67%, a decline past the 30% mark, and it trades about 67% below its 52-week high of $76.87.
Company-specific problems added pressure. A report highlighted infrastructure and disclosure concerns, including storage failures and cooling problems, and shares fell 8.13% that session. Fiscal Q4 results also disappointed. Revenue of $137.2M missed the $140.75M consensus and fell 26.8% year over year, while a $450.4M non-cash impairment on retired mining hardware drove a $684M net loss.
Why No Analyst Rates IREN a Sell After the Crash
Contracted revenue supports the optimistic thesis. Management said $4 billion of ARR is now contracted for our 2026 capacity and $1 billion of that is operating today. Horizons 2 through 4 for Microsoft are targeted for the December quarter, with most of the revenue impact landing in the March quarter. That figure excludes $700 million of ARR from the NVIDIA contract that starts in 2027.
Pricing power forms the second factor. Recent three-year contracts priced above $20 million per megawatt of IT load, with active discussions near $25 million, and management says those deals pay back the compute in about two years. CEO Daniel Roberts put demand bluntly: “There are no idle GPUs.”
Funding is the third. IREN has about $14 billion of cash, committed GPU financing and prepayments against fiscal 2027 capex guidance of $25 billion to $30 billion. Bernstein’s thesis also leans on low-cost power and fast deployment, backed by a power pipeline exceeding 5GW.
The ratings mix stays positive:
- Strong Buy: 2
- Buy: 13
- Hold: 5
- Sell: 0
The skeptic’s point is the funding gap. IREN still targets roughly $8 billion of additional GPU financing and prepayments, and data-center financing remains unannounced.
Riot and Cipher Fell Just as Hard
A broad sector sell-off hit IREN alongside its peers.
Riot Platforms (NASDAQ:RIOT) dropped 45.26% in a month and is down 0.63% year to date. At $12.59 against a $29.84 target, it carries about 137% implied upside. Analysts are 7 Strong Buy, 14 Buy and 1 Hold, but the Street sees less upside here than at IREN.
Cipher Mining (NASDAQ:CIFR) fell 56.51% in a month and is down 47.76% year to date. At $7.71 against a $29.36 target, implied upside is about 281%, with 5 Strong Buy, 15 Buy and 2 Hold ratings.
Cipher shows the largest consensus upside in the group, which places IREN in the middle. Every one of these targets is an estimate that can be cut.
IREN Trails the S&P 500 by a Wide Margin
At $25.43, IREN sits far below the $77.81 consensus target, an implied upside of about 206% across 20 covering analysts. Those targets are one data point.
IREN is down 32.67% year to date and 59.57% over the past year. The S&P 500 is up 12.23% year to date. A beta of 4.271 explains why the moves run so wide in both directions.
A Real Backlog Priced Like a Neocloud Casualty
Optimism builds if Horizons 2 through 4 hit on schedule, ARR passes $4 billion and the data-center financing closes on reasonable terms. That path turns contracted revenue into reported revenue and gives analysts the proof they need to defend the $77.81 consensus.
Pessimism deepens if the infrastructure problems resurface, if credit markets tighten as the Gartner view gains acceptance, or if customer concentration with Microsoft and NVIDIA turns into pricing pressure. Debt-to-equity of 1.87 leaves little room for delays.
The evidence tends positive. Signed contracts with top-tier counterparties make IREN a stronger case than most neoclouds, and confirmed Horizon delivery is the key milestone for the upside case.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.