Intel Is Trying to Reinvent Itself. Here’s Where INTC Stock Could Be in 2027
Intel stock has already surged over 230% this year, yet Wall Street's consensus target still sits below the current price. Whether the turnaround can survive its own momentum and reach $150 by 2027 comes down to a few critical bets…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
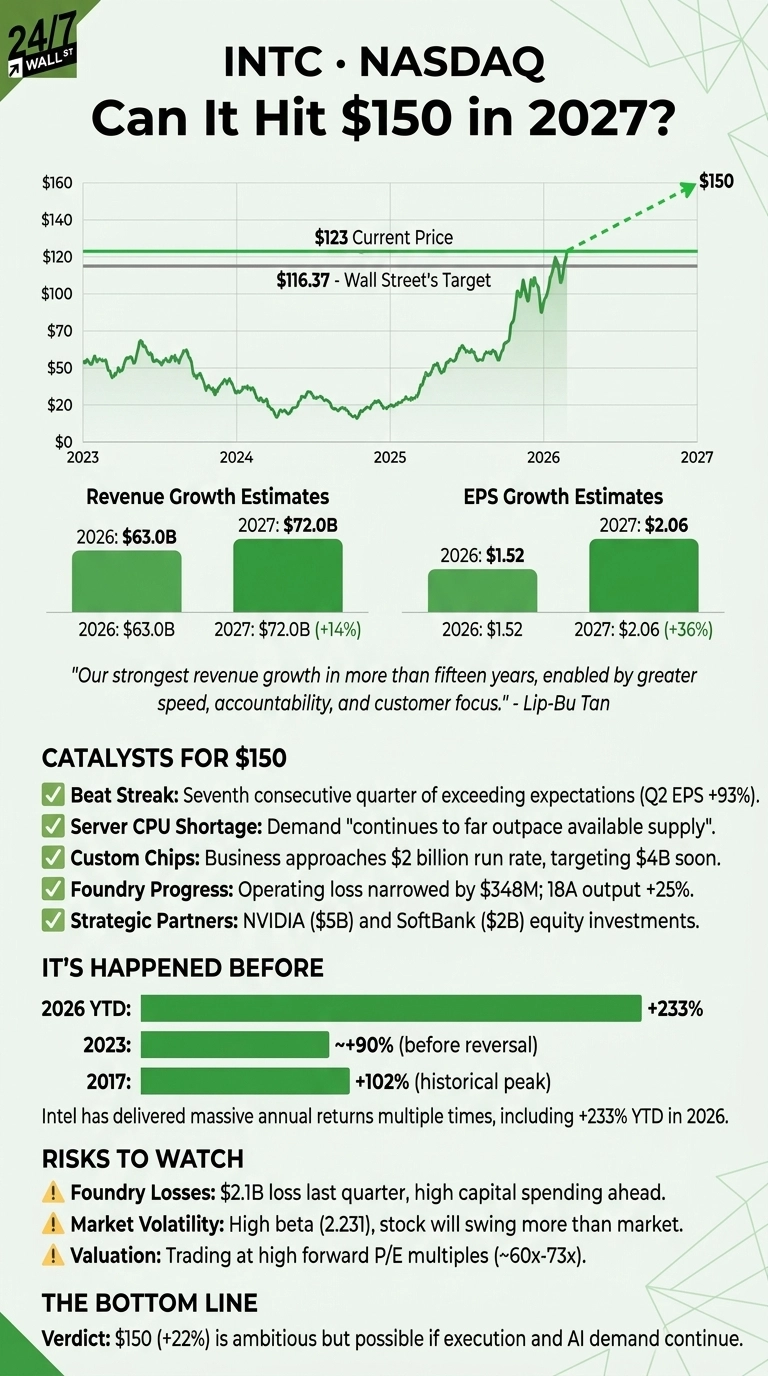
Intel’s turnaround is starting to show up in its financial results. Intel (NASDAQ:INTC | INTC Price Prediction) posted Q2 revenue of $16.13B, up 25.4% year over year. CEO Lip-Bu Tan called it “our strongest revenue growth in more than fifteen years, enabled by greater speed, accountability, and customer focus.”
Intel 18A output came in approximately 25% above target, and management described Xeon 6 as “one of the fastest ramping products in Intel history.”
Shares are up 233.33% year to date to $123. The next question is how much further the stock can go. Here’s what Intel needs to do to hit $150 in 2027.

Wall Street Is Trailing Intel’s Rally, and Estimates Keep Rising
Analysts haven’t caught up with the stock. The consensus price target of $116.37 is about 5% below the current price. 32 analysts rate the stock Hold, compared with 13 Buy and 1 Strong Buy.

Earnings forecasts tell a more bullish story. Consensus 2027 EPS has rose to $2.0621 from $1.5245 90 days ago, an upward revision of roughly 35%. Analysts expect 2027 revenue of $72B, about 14% above the 2026 estimate, with EPS growing roughly 36%.
Can Intel Really Hit $150? Let’s Do the Math
At $123, Intel trades at about 60x consensus 2027 EPS. At $150, that multiple would rise to roughly 73x, far above the S&P 500’s forward multiple of about 21-23x.
The most bullish analyst expects $3.44 in 2027 EPS. At that level, $150 works out to about 44x. Intel keeps beating forecasts, making results near the high end realistic.

What Could Push Intel to $150?
- Beat run: Q2 was Intel’s seventh consecutive quarter of exceeding expectations. Non-GAAP EPS of $0.42 beat the $0.2175 estimate.
- Server CPU shortage: Server CPU demand “continues to far outpace available supply.” Data Center and AI revenue rose 59%, with operating profit at 40% of revenue.
- Custom chips: This business approaches a $2 billion run rate with management expecting $4 billion soon against a market sized at over $100 billion.
- Foundry progress: The foundry operating loss narrowed by $348 million from the prior quarter. Intel 14A risk production is on track for the second half of 2027.
- Strategic partners: NVIDIA (NASDAQ:NVDA) made a $5B equity investment and picked Xeon 6 for its DGX Rubin NVL8 systems. SoftBank added $2B.

Hurdles remain. Intel Foundry lost $2.1 billion last quarter, and 2027 capital spending is expected to be “significantly above the 2026 levels.” With a beta of 2.231, the stock will swing more than the broader market.
Intel’s History Says a 22% Move Is Well Within Range
Reaching $150 requires a gain of about 22%, small next to this year’s 233.33% run. In 2023, shares rose roughly 90% before giving that gain back. Intel also traded as high as $142.35 within the past 52 weeks, not far below the target.
Is $150 Realistic? Here’s My Take
Hitting $150 requires a roughly 22% gain. EPS estimates are rising quickly, Intel keeps beating them, and server demand is ahead of supply. If 18A keeps ramping and custom chip and foundry businesses scale, earnings could rose enough to support a higher price.
That’s the plan for outsized returns in 2027, and the same set of early signs we cataloged in a free playbook on spotting the next Nvidia before the headlines catch on.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.