Nebius’ Strong Signal Is Going to Move Markets in the Coming Days
Nebius just announced a price hike on its most in-demand GPU clusters, but soaring interest costs and a wave of bearish retail sentiment raise real questions about whether that pricing power actually reaches the bottom line.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) warrants a closer look at $231.88. The bullish case rests on a price increase on its AI compute that takes effect October 1, which gives investors hard evidence that GPU capacity still commands pricing power.
Nebius runs a full-stack AI cloud, and its AI business produced 98% of group revenue last quarter. It leases clusters of NVIDIA (NASDAQ:NVDA) chips to AI labs and enterprises. It also holds a $27B five-year agreement with Meta (NASDAQ:META). Shares are up 177.02% year to date but fell 2.3% in the latest session.
Nebius Is Charging More on Every Contract Type
Starting October 1, Nebius is raising on-demand prices across its H100, H200, B200 and B300 family (UsagePricing). The move fits a pattern. The company’s first capacity auction cleared 15% above the highest price we ever charged before, and management said it “could sell today our entire 2027 capacity” on its current terms.
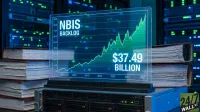
Short-term deals are priced at $40 million to $50 million per megawatt, compared with $20 million to $25 million on core contracts. Second-quarter revenue grew 454% to $582.3M. The adjusted EBITDA margin reached 41%, and remaining performance obligations stand at $37.49B. A PEG ratio of 0.511 suggests the valuation falls behind the company’s growth.
Debt Costs and Dilution Could Absorb the Price Gains
Interest expense rose to $119.1M from $4.8M a year earlier. Convertible debt totals $8.5B, and the company sold 12.7M shares through its at-the-market program. Capex guidance of $20 billion to $25 billion means more fundraising is likely, and it’s a reminder that the same data-center expansion is lifting the power, cooling, and networking names we rounded up in a free report on AI infrastructure suppliers.
Analysts have cut their 2027 EPS estimate to -$5.2292, down from -$2.13 90 days ago. Three customers account for 24%, 21% and 14% of revenue. Retail traders on Reddit have turned sharply negative, with sentiment scores falling as low as 8.
2027 Guidance Will Matter More Than This Week’s Price Change
Management said deals coming online late this year will not significantly affect 2026 guidance. On-demand pricing is only one slice of revenue, and new power capacity takes several months to start producing revenue. Formal 2027 guidance is due later this year. That outlook will show whether higher pricing lifts earnings or gets eaten by interest costs.
Analysts See 22% Upside as Nebius Outpaces the S&P 500
The consensus target of $283.58 implies 22.3% upside. Price targets are forecasts, and the stock can miss them. Seven analysts cover the stock:
- Strong Buy: 1
- Buy: 4
- Hold: 2
Shares trade at 46x forward earnings. Year to date, Nebius has returned 177.02% while the S&P 500 gained 12.26%. Over the past month, Nebius rose 10.85% while the index slipped 0.49%.
Pricing Momentum Underpins the Nebius Thesis at $231.88
At $231.88, Nebius warrants a closer look.
The price increase supports what the auction already showed: demand for compute is exceeding supply, and Nebius kept unsold capacity to capture that premium. As higher-yield contracts ramp from late in the fourth quarter, the third-quarter earnings report and the 2027 guidance should show how quickly pricing turns into margin.
The stock trades well below its 52-week high of $299.86, and bearish retail sentiment means expectations are modest heading into the price change. The investment case falls apart if customers push back on the new pricing, if financing costs rise faster than per-megawatt yields, or if a major customer scales back.
Nebius is raising prices because demand lets it, and at this level investors are paying a discount to that pricing power.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.