Price Prediction: From $40 to $2,000 in a Year. Where is SanDisk Headed Now?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
SanDisk’s ascent on the NASDAQ this year raises a key question: does the AI memory supercycle still have room to run, or has the easy money already been made?
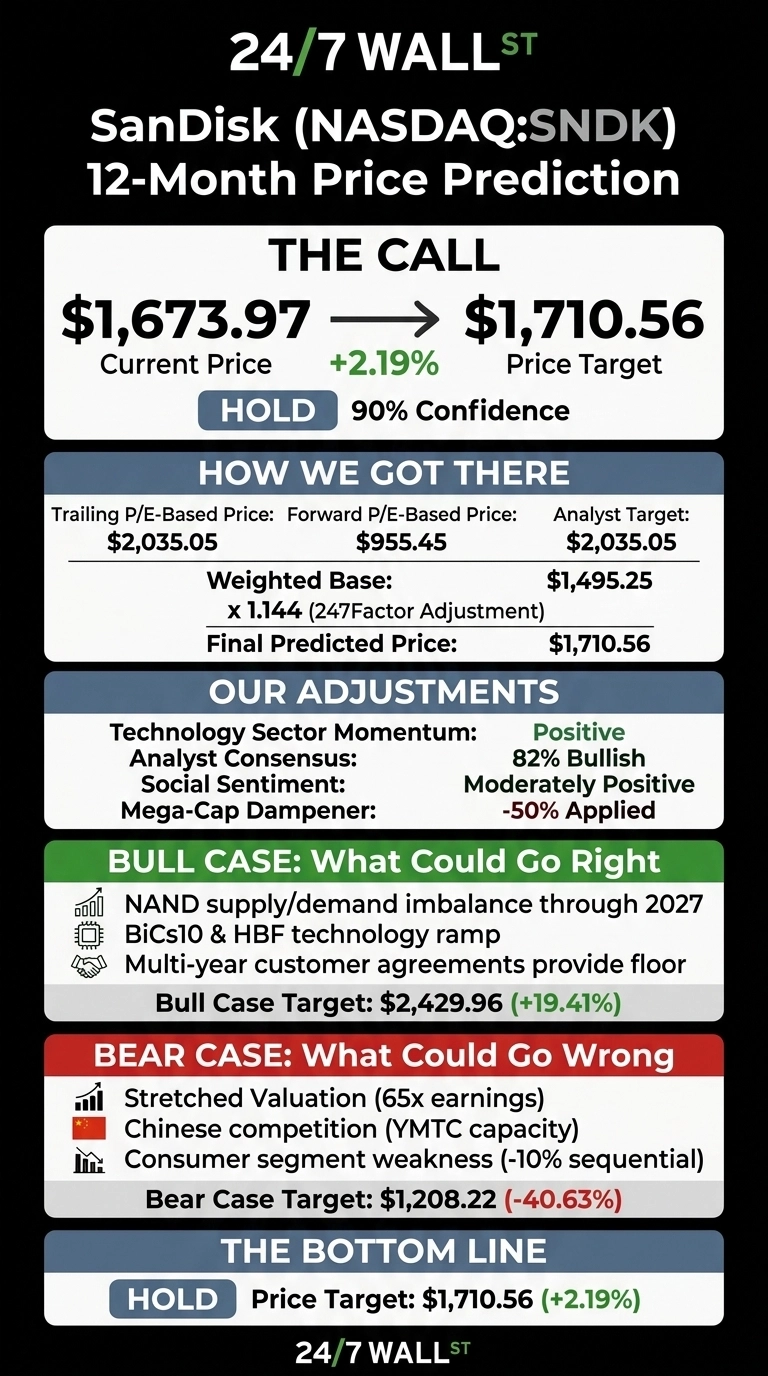
My 24/7 Wall St. price target for SanDisk (NASDAQ:SNDK | SNDK Price Prediction) is $1,710.56 over the next 12 months, against a current price of $1,673.97. That represents roughly 2% upside, meaning the model calls this stock fairly valued. My recommendation is hold with 90% confidence.
| Metric | Value |
|---|---|
| Current Price | $1,673.97 |
| 24/7 Wall St. Price Target | $1,710.56 |
| Upside | 2.19% |
| Recommendation | HOLD |
| Confidence Level | 90% |
From $40 to $2,000 in Under a Year
SNDK is up 605.19% since the December 31 close of $237.38, and 3,531.96% over one year. Recent momentum has softened, with the stock down 15.46% over the past month and 14% below the 52-week high of $2,354.39.
Fundamentals justify much of the re-rating. Q3 FY2026 revenue hit $5.95 billion, up 251.03% year over year, with Non-GAAP EPS of $23.41 against $14.66 consensus. Datacenter revenue surged 645% year over year to $1.467 billion.
Q4 guidance calls for $7.75 billion to $8.25 billion in revenue and Non-GAAP EPS of $30 to $33. Bernstein raised its target to $3,000 and Bank of America to $2,500, though an 8% pullback on July 13 tied to SK Hynix IPO concerns offset some gains.

The Case for $2,400 Plus
The bull case rests on supply dynamics. Bank of America argues the NAND supply/demand imbalance will continue through 2027, and Bernstein’s Mark Newman estimates new multi-year customer agreements provide a floor of 29 cents per gigabyte.
Five NBM agreements have been signed. If Q4 lands at guidance’s top and BiCS10 ramps into 2027, the bull trajectory points to $2,429.96, a 19.41% return. China Renaissance’s $3,169 target sits well above that.
What Could Break the Thesis
The bear case starts with valuation. SNDK trades at 65 times earnings, with forward-P/E math implying fair value nearer $955. Chinese competition from YMTC, a $29 billion SK Hynix listing that could siphon capital, and Consumer segment weakness down 10% sequentially all matter.
Insider selling has been steady, with the CLO selling 600 shares on July 1. Bulls counter that these sales occurred under a Rule 10b5-1 plan and Consumer weakness reflects a deliberate mix shift, not lost demand. The bear-case model lands at $1,208.22, or 40.63% downside.
How SanDisk Stacks Up Against Micron and Seagate
Micron Technology (NASDAQ:MU) is the cleanest comparable, with overlapping NAND exposure and similar AI-driven margin dynamics. Micron posted fiscal Q3 revenue of $41.46 billion (+345.7% YoY) and Non-GAAP EPS of $25.11, with GAAP gross margin at 84.6%. That is a bigger, more diversified memory business trading at a lower multiple, making SanDisk’s premium look aggressive on scale but reasonable on pure-play NAND leverage.
Seagate Technology (NASDAQ:STX) offers the storage counterpoint. Seagate’s fiscal Q3 revenue rose 44.1% to $3.11 billion with Non-GAAP EPS of $4.10, riding HAMR-based Mozaic drives into hyperscaler racks. Seagate proves AI storage demand is broad-based, supporting SanDisk’s floor but capping how much of the AI storage wallet SNDK can capture.
Against these peers, my 24/7 Wall St. price target of $1,710.56 looks reasonable.
SanDisk Price Prediction 2026-2030
My 24/7 Wall St. price target is $1,710.56 with a hold rating and 90% confidence. I’d be a buyer if Q4 lands at guidance’s top and NBM agreements expand past five. I’d stay on the sidelines if China’s YMTC accelerates capacity or Consumer stays negative. For now, risk-reward is balanced.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $1,710.56 |
| 2027 | $1,650.00 |
| 2028 | $1,600.00 |
| 2029 | $1,590.00 |
| 2030 | $1,583.68 |
These projections assume SanDisk executes its datacenter mix shift and NAND pricing holds through 2027. Significant upside or downside could result from a China-led supply shock or accelerated HBF adoption for AI inference.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.