Price Prediction: Tesla Will Trade at $400 on This Date
Tesla is down more than 21% this year and sitting well below a key price level, but two specific dates on the calendar could change everything for retirement investors holding TSLA.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

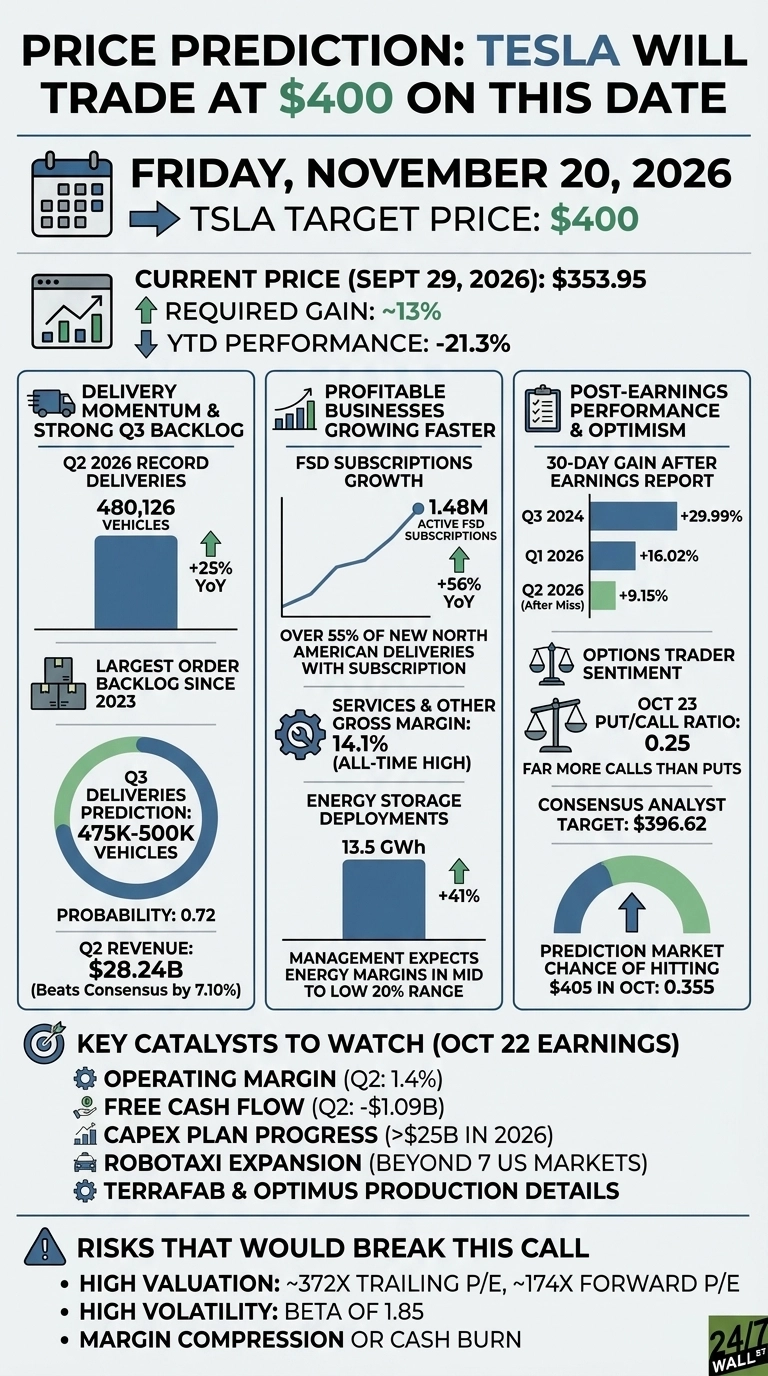
Tesla (NASDAQ:TSLA | TSLA Price Prediction) will close at or above $400 on Friday, November 20, 2026. That is four weeks after its Q3 2026 earnings report, which is expected after the market closes on October 22, 2026.
The stock traded at $353.95 late this morning, so getting to $400 takes a gain of about 13%. It is down 21.3% year to date. Retirement investors should mark two dates: October 22, when the earnings report comes out, and November 20, when this call gets settled.
Delivery Momentum Sets Up a Strong Q3 Report
Tesla delivered a record 480,126 vehicles in Q2, up 25% year over year. It ended the quarter with its largest order backlog since 2023. Prediction market traders put a 0.72 chance on Q3 deliveries landing between 475,000 and 500,000.
Q2 revenue came in at $28.24B, beating consensus by 7.10%. With the backlog this full, Q3 revenue has room to grow on top of that base.

Profitable Businesses Are Growing Faster Than Car Sales
Active FSD subscriptions reached 1.48M, up 56% year over year. More than 55% of new North American deliveries came with a subscription attached. Services and other gross margin rose to 14.1%, an all-time high.
Energy storage deployments hit 13.5 GWh, up 41%. Energy margins in Q2 were weighed down by an approximately $240 million warranty true-up, and management expects them to settle in the mid to low 20% range. If that one-time charge does not repeat, Q3 margins will look better than Q2 on paper.

Tesla’s Post-Earnings Record Points Higher
After Q2’s earnings miss of -38.51%, the stock fell -14.52% on earnings day. It still finished the next 30 days up 9.15%.
After Q1 2026, the 30-day gain was 16.02%. After Q3 2024, it was 29.99%. Options traders lean the same way. The put/call ratio for contracts expiring October 23, the day after earnings, is 0.25.
A ratio that low means far more calls than puts, so traders are mostly prepared for gains. The consensus analyst target is $396.62, and prediction markets give Tesla a 0.355 chance of hitting $405 in October alone.

What to Watch on October 22
- Operating margin, which fell to 1.4% in Q2
- Free cash flow, which was negative $1.09B in Q2
- Progress on the plan to spend more than $25 billion in 2026 capital spending (capex)
- Robotaxi expansion beyond the current seven markets in the US
- Details on TerraFab, Tesla’s planned chip plant, and on the Optimus robot production line
Management has said capex will keep rising for the next two or three years. Tesla has $43.5B in cash and a debt-to-equity ratio of just 0.10, so it can pay for that expansion without stressing the balance sheet. Investors will be looking for signs of that spending turning into revenue.
Risks That Would Break This Call
At 372 times trailing earnings and about 174x forward earnings, Tesla has little room for disappointment. Its beta of 1.85 means it moves much more than the overall market in both directions.
Another quarter of fell margins or a bigger cash burn would keep the stock below $400 on November 20 and extend its losing streak for the year. Record deliveries, fast-growing FSD subscriptions and a reliable 30-day rebound after earnings still make $400 on November 20 the most likely outcome.

Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.