Tesla Stock Has a Potential Catalyst Wall Street Can’t Ignore
Tesla just posted record deliveries and expanded Robotaxi to seven cities, yet the stock sits 20% in the red for the year. Something has to give, and one stacking set of catalysts could force Wall Street to completely rethink its…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Tesla (NASDAQ:TSLA | TSLA Price Prediction | TSLA Price Prediction) just delivered 480,126 vehicles in a single quarter, expanded Robotaxi to seven U.S. metros, and grew active FSD subscriptions to 1.48 million, up 56% year-over-year.
Elon Musk told investors on the July earnings call that “This is going to be a great year for Tesla, I think. One of our best years ever.” Shares tell a different story. TSLA trades at $357.24, down sharply on the year. The question I want to answer: can Tesla realistically reach $550 by 2027?

Why Tesla Shares Are Stuck Despite Record Deliveries
The stock is down for a reason, and I won’t pretend otherwise. TSLA is off 20.56% YTD and 9.77% over the past year, even after a 4.37% bounce over the past month.
The core issue is margin compression. Operating margin collapsed to 1.4% in Q2, operating income fell 56.88% year-over-year, and free cash flow swung to negative $1.092 billion as capex surged 141.81%.
On top of that, Barron’s reported this week that Musk himself has added to the chorus of AI concern, pressuring the stock. With a beta of 1.845, TSLA amplifies every macro wobble. That’s the full picture before we get to the bull case.
Wall Street Sees 9% Upside. I Think They’re Underestimating the Fleet Economics
The Wall Street consensus target is $390.09, with 6 Strong Buys, 16 Buys, 19 Holds, 3 Sells, and 2 Strong Sells. Our own model base case sits at $389.65, a 6.63% upside, with a bull case of $465.72 and a bear case of $351.99. Model confidence is high at 0.9.

Here’s my pushback. Consensus is anchored to auto-margin math while Tesla’s mix is quietly pivoting to software. Services and Other grew 50% year-over-year at a 14% gross margin. Bullish analyst sentiment already sits at 48 versus 11 bearish. If Robotaxi economics land the way management is telegraphing, $390 will look conservative in a hurry.
Path to $550 Per Share: The Math
Reaching $550 from today’s price of $357.24 would require a gain of 54%. With forward EPS of $2.35, a price of $550 implies a forward P/E of 234x. Our base case of $389.65 already implies 210x, meaning the bold target requires roughly 24x of additional multiple expansion.
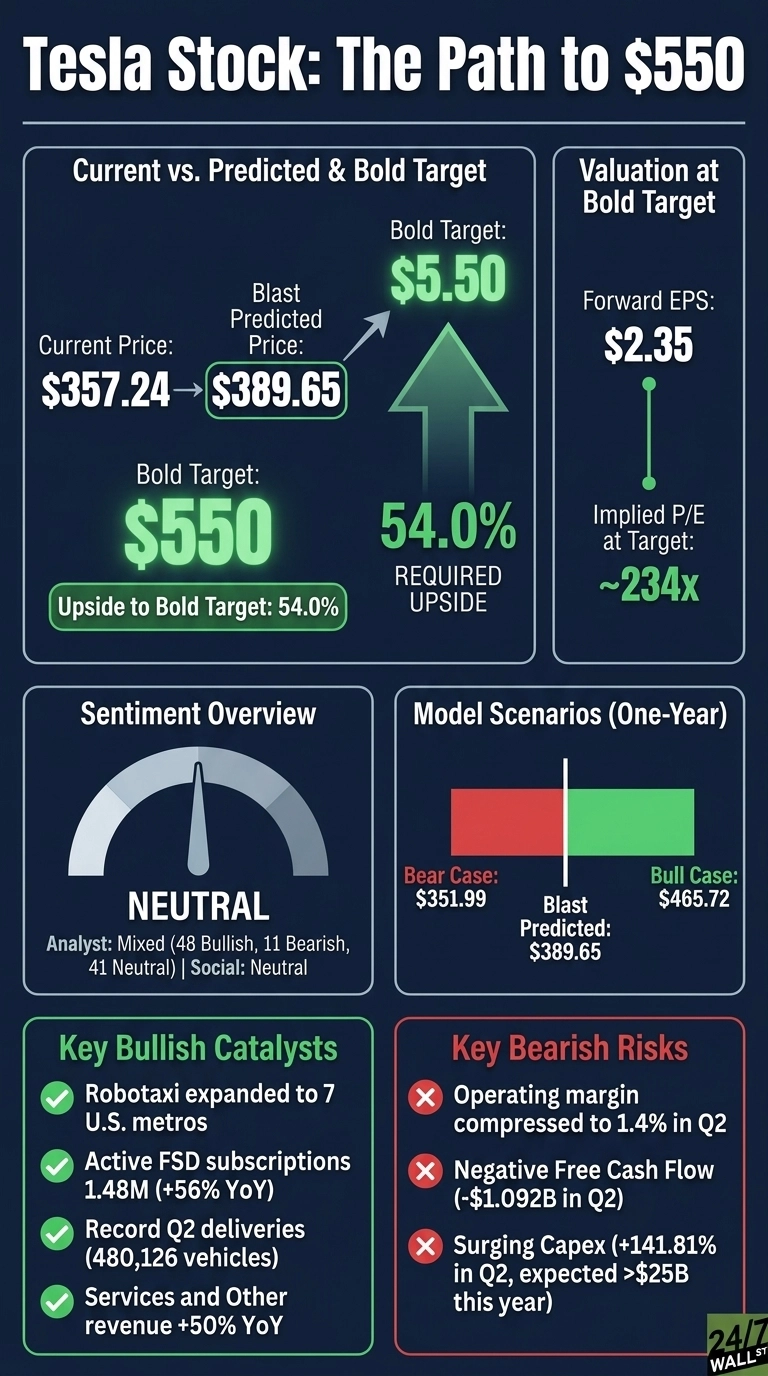
Expensive on paper. But the 247Factor model already applies a 1.05 adjustment driven by a 1.05 sector momentum multiplier in Consumer Cyclical.
The catalysts are specific and stacking: Ashok, Tesla’s VP of AI, said Robotaxi has driven “more than 380,000 miles of unsupervised Robotaxi, now across six cities in two different states” with “zero notable incidents.” Taneja said Tesla exited Q2 with “our largest order backlog since 2023.”
Musk noted Robotaxi miles are growing “more than 10% a week.” Add an Optimus production line at Fremont, Semi commissioning in Nevada, and Megapack 3 for 2026, and forward EPS revisions could inflect.
The primary risk: capex expected to exceed $25 billion this year could suppress earnings longer than bulls expect.

Where Tesla Trades Today vs Its Earnings Power
At $357.24, TSLA trades at roughly 152x forward EPS of $2.35. Rich by any traditional yardstick, but the stock sits well below its 52-week high of $498.83 and above its low of $297.38.
Long-term, TSLA has returned 2,508.85% over the past decade. That history matters: multiple expansion in Tesla has historically preceded earnings inflections tied to a new product category.
Is $550 Realistic? My Verdict
A move to $550 requires a 54% gain and a forward P/E near 234x. That’s a stretch scenario well above our base case.
But it’s within the realm of possibility if three things line up: Robotaxi scales beyond the current seven cities without safety setbacks, FSD attach rates keep climbing past the current 55% of new North American deliveries, and Optimus shows tangible manufacturing progress.
What would derail it: another quarter of margin compression that forces the Street to cut 2027 EPS estimates further. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Tesla could reach $550 in 2027 (the same early-stage traits we cataloged across past 100x tech winners in a free playbook here).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.