Broadcom’s Massive $42 Billion Chip-Buying Deal with Anthropic Raises Circular Financing Worries
Broadcom just agreed to lend billions to the same AI lab it sells chips to, lease equipment to, and may soon own a stake in. That four-way entanglement raises a question shareholders cannot yet answer: whose demand is actually driving…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Broadcom’s $42 Billion Number Makes the Supplier the Lender
Broadcom (NASDAQ:AVGO | AVGO Price Prediction) has agreed to lend Anthropic up to $42 billion, according to the AI lab’s IPO filing, as reported by Reuters on October 1, 2026. The money pays for Anthropic’s infrastructure spending, and much of that spending goes to Broadcom hardware. The debt can also convert into Anthropic shares. Broadcom now plays four roles in this relationship: chip supplier, equipment lessor, lender, and possible future shareholder.

What $42 Billion Shows About Broadcom’s AI Growth
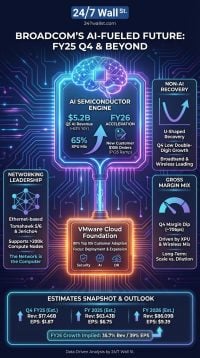
The facility could cover about one-third of Anthropic’s $125.2 billion five-year TPU compute commitment. That commitment supports Broadcom’s AI plan. On the September earnings call, management said it expects Anthropic to become its largest XPU customer in 2027 and to hold that spot in 2028. Broadcom is installing one gigawatt of Ironwood chips for Anthropic in 2026. Anthropic is expected to installing five gigawatts of TPU v8i chips in 2027, and Broadcom says it has “clear line of sight” to an extra 10 gigawatts in 2028.
Those installations support Broadcom’s AI revenue outlook of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. The $42 billion facility tops the $23.975 billion in cash Broadcom held at the end of its third quarter.
The loan adds to earlier financing support. In June, Broadcom set up a financing platform with Apollo Global Management (NYSE:APO) and Blackstone (NYSE:BX). Its first $35 billion tranche closed that month to pay for Anthropic’s one-gigawatt installations. Management said at the time that third parties would insure those assets and that Broadcom would provide no direct financing, though it might offer “modest residual value guarantees.” Broadcom lending directly to Anthropic is a much deeper commitment.
How Broadcom Stock Reacted to the News
Barron’s reported on October 1 that Broadcom stock rose as the two companies became more closely tied. On the next trading day, October 2, shares gained 3.35%, from $343.64 to $355.14. CNBC listed Broadcom among that day’s biggest noon movers.
Over a longer stretch, the stock has gone almost nowhere. Shares changed -0.39% from September 3 through October 2, and they remain well below the 52-week high of $493.28.

Bear Case: Broadcom Is Financing Its Own Demand
Broadcom’s operating results are strong. Third-quarter revenue reached $29.59 billion, up 85.5% from a year earlier, and free cash flow was $13.665 billion. The concern is how much of the future revenue depends on Broadcom’s own credit.

- Anthropic’s filing flags the conflict. Anthropic itself warns that Broadcom’s two roles as supplier and lender create “potential conflicts of interest” involving pricing and hardware decisions.
- Default terms work against both sides. Anthropic put cash into a restricted account for Broadcom’s benefit in April 2026 and may have to add more. If Anthropic misses payments or other obligations, much of what it owes on its leases could come due at once, and its access to the loan could be limited at the same time.
- Exposure is hard to measure. On the call, management would not give a maximum figure for future guarantees. It said future deals would have “unique features” tailored to each lab. An analyst noted the first tranche carried maximum exposure of about $29 billion.
- The customer list is short. Broadcom has only six XPU customers, and its filings list customer concentration and “significant indebtedness” as risks. Gross fixed-rate debt stands at $59.6 billion.
Reuters described the deal as part of a broader industry pattern, comparing it with NVIDIA (NASDAQ:NVDA) using its balance sheet to support chip sales. Shareholders end up carrying credit risk tied to a single AI lab, while the stock still trades at 45x trailing earnings.
Bottom Line: Anthropic’s IPO Is the Key Test
The $42 billion figure shows how much of Broadcom’s path to $230 billion in fiscal 2028 AI revenue depends on one customer that Broadcom is also helping to pay for. The next major event is Anthropic’s IPO. Management said the listing could change Anthropic’s credit profile, and it would also show what Broadcom’s possible equity stake is worth. Before that, Broadcom has guided fourth-quarter revenue to about $34.80 billion and AI semiconductor revenue to $21.70 billion. Long-term holders will need to judge whether that growth comes from customers’ own spending or from Broadcom’s lending.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.