Broadcom Just Made a Move That Further Solidifies My Decision to Buy on Repeat
Broadcom's latest earnings dropped a set of forward projections so aggressive that ignoring them starts to feel like a mistake. Here is why one investor keeps adding shares on every single paycheck.

I keep buying Broadcom (NASDAQ:AVGO | AVGO Price Prediction) and the September 2 earnings report gave me another reason. Management unveiled VMware Private AI Cloud alongside numbers that read like a company pulling away from the rest of the AI infrastructure field.
Why I Keep Buying on Every Paycheck
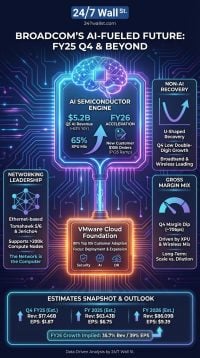
Broadcom sells the picks and shovels of frontier AI: custom XPUs for the six labs that train the largest models, plus the networking silicon that stitches those chips into gigawatt-scale clusters. That combination generated $16.7 billion in AI semiconductor revenue in Q3 FY2026, up 221% year over year and 54% quarter over quarter. Guidance calls for $21.7 billion in Q4, up 236% year over year. CEO Hock Tan said Broadcom has “secured the supply to gain double AI revenue” to roughly $115 billion in fiscal 2027, with line of sight to another doubling to $230 billion in fiscal 2028. Tan targets “very much on target to exceed $30 in earnings per share in fiscal 2028”.
Three Numbers That Keep the Order Standing
Q3 free cash flow hit $13.67 billion, or 46% of revenue, and cash on the balance sheet climbed to $23.98 billion, up 123.69% year over year. A new $10 billion repurchase program was authorized in March 2026.
Broadcom raised the dividend 10% in December 2025, the 15th consecutive annual increase since fiscal 2011, to $0.65 per share quarterly. Management paid down $5.6 billion of long-term debt in the quarter and another $1.5 billion of senior notes after quarter-end, with weighted-average coupon at 4%.
Tan said Broadcom expects to ship “$350 billion of AI semiconductors to these customers in the next two years”. Anthropic is on track to become Broadcom’s largest XPU customer in 2027 and sustain that in 2028, with 1 gigawatt of Ironwood deploying in 2026, 5 gigawatts of TPU v8i in 2027, and a further 10 incremental gigawatts in 2028.
Why Not the Obvious GPU Name
The reflex trade in AI silicon is NVIDIA (NASDAQ:NVDA). I own some. I keep adding Broadcom because OpenAI’s Jalapeno accelerator “outperforms Grace Blackwell GPU for inference workloads” at “half the cost of a GPU”. When hyperscalers co-design silicon that beats the general-purpose part on their own workload at half the cost, the custom vendor collects the design win (we studied what the early signals of the biggest tech winners looked like and put them in a free playbook here). The stock has returned 2,711.1% over the past ten years.
Risk I Will Not Wave Away
Customer concentration is real. Broadcom has six XPU customers, and a slip at Anthropic, OpenAI, Google, or Meta would pressure revenue. Tan flagged it: “Land power and shell… is a big concern”. What keeps the thesis intact is the AI XPV financing platform with Apollo and Blackstone, whose first $35 billion tranche closed in June for Anthropic’s one gigawatt deployment, which is already underway.
What Keeps the Buy Button Warm
VMware Private AI Cloud extends the moat into enterprise private AI, on top of infrastructure software growing 29% year over year with 15% ARR growth. Rising dividend, falling debt, custom silicon that undercuts GPUs on cost, and a two-year shipment book measured in hundreds of billions of dollars. I will keep buying until one of those four things breaks.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.