Prediction: The AI Spending Boom Could Be Just Getting Started for This Company
Broadcom's AI revenue is tripling while its stock sits nearly 30% below its peak, creating a gap that either signals a buying opportunity or a warning sign worth understanding before December's earnings report.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
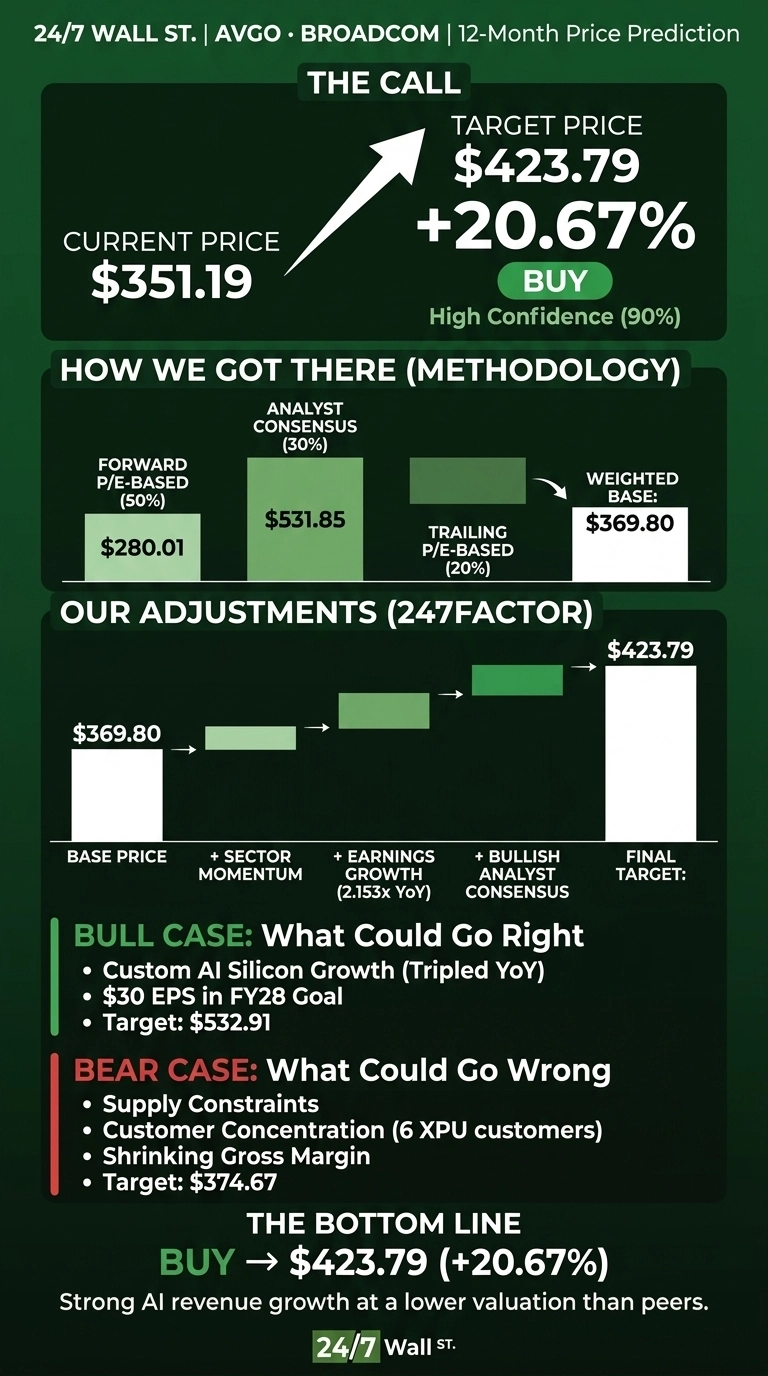
Broadcom (NASDAQ:AVGO | AVGO Price Prediction) trades at $351.19. Our 24/7 Wall St. price target is $423.79 over the next 12 months. That means 20.67% upside, and our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $351.19 |
| 24/7 Wall St. Price Target | $423.79 |
| Upside/Downside | 20.67% |
| Recommendation | BUY |
| Confidence Level | 90% |

Management’s guidance supports the thesis. On the most recent earnings call, CEO Hock Tan said “Q3 demand was simply hot and we’re just getting started.” Broadcom expects AI revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
AI Revenue Tripled While Shares Slipped From Their Highs
The stock is down 6.07% over the past month and up just 0.88% year to date. It sits 28.8% below its 52-week high of $493.28 and 21.5% off its low of $288.95.
In fiscal Q3, revenue came in at $29.591B, up 85.5% and ahead of the $29.44B estimate. Non-GAAP EPS of $3.32 also beat expectations of $3.2382. AI semiconductor revenue rose 221% to $16.70B. Today’s headlines point to Broadcom and Anthropic becoming more closely tied, which supports the custom-silicon story (Barron’s).

Why Bulls See $532 and Beyond
The bull case reaches $532.91, close to consensus. Analysts include 8 Strong Buys, 37 Buys and zero Sells. Management expects to “exceed $30 in earnings per share in fiscal 2028,” which is about 12x that figure at today’s price.
Broadcom plans to deliver “multi-tens of billions of dollars of TPUs annually” to Google, and it is scaling up custom chips for OpenAI and Meta. It also taped out Tomahawk 7, the first 200 terabit Ethernet switch.

Supply Limits and Customer Concentration Could Slow the Ramp
The bear case of $374.67 still sits above today’s price. AI revenue depends on six XPU customers. Supply of wafers, substrates, HBM, and data center power limits revenue growth speed. Gross margin is shrinking as XPUs gain mix share.
Q4 operating margin guidance of about 66% shows operating leverage holding. Residual value guarantees on the XPV financing platform add contingent liabilities. Broadcom paid down $5.6 billion of long-term debt in Q3.
Broadcom Trades Cheaper Than NVIDIA, AMD and Marvell
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Broadcom | 19x | 85.5% |
| NVIDIA | 25x | 105.9% |
| AMD | 40x | 50.1% |
| Marvell | 62x | 36.5% |
NVIDIA (NASDAQ:NVDA) is the GPU leader that Broadcom’s custom chips compete against. It grows faster but trades at a higher multiple.
Advanced Micro Devices (NASDAQ:AMD) is the alternative merchant GPU vendor. It trades at 40x forward earnings while growing more slowly than Broadcom.
Marvell Technology (NASDAQ:MRVL) is the closest ASIC and networking peer, and it costs more than three times as much per dollar of forward earnings. At our target, Broadcom would trade near 23x forward EPS, still below NVIDIA. Against this peer group, the 24/7 Wall St. price target looks conservative.
Broadcom Earns a Buy Rating From Our Model
The 24/7 Wall St. price target of $423.79 has a buy rating and 90% confidence. Broadcom trades at the lowest forward multiple in its peer group while growing AI revenue at triple-digit rates.
Watch for Q4 AI revenue at the $21.70B guidance when Broadcom reports on December 9. Supply constraints pushing 2027 deployments back would be the main risk. Today, the risk-reward favors the bulls.

Broadcom Price Prediction 2026-2030
Looking further ahead, here is where our model projects Broadcom could trade, assuming current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $354.86 |
| 2027 | $423.79 |
| 2028 | $466.51 |
| 2029 | $513.54 |
| 2030 | $565.30 |
The projections rest on Broadcom continuing to execute on its custom-silicon roadmap. Significant upside could follow if supply expands faster than planned, while delays in hyperscaler deployments are the main downside risk. For investors hunting the next monster AI chip run, we reverse-engineered the signs past winners showed early in a free playbook you can grab here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.