Amazon at $250: $1 billion “Built Together” Data Center Push Is Already Backfiring
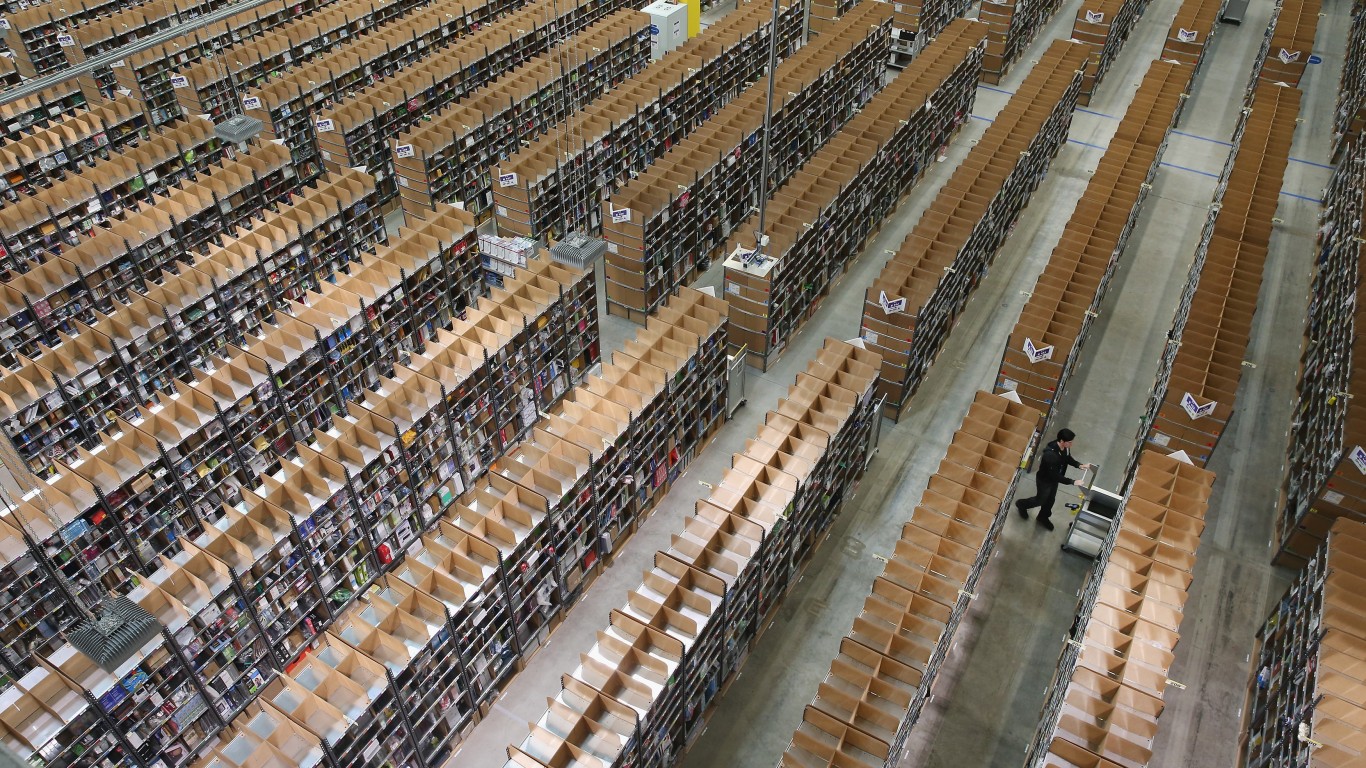
Amazon is spending $200 billion in a single year to dominate cloud infrastructure, but its free cash flow just turned negative and its stock has slipped 8% from its post-earnings peak. The data centers being built today will not produce…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
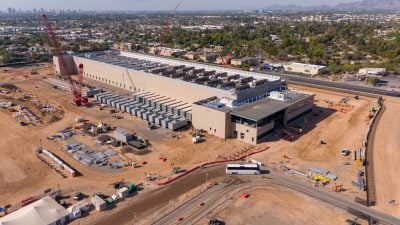
Amazon (NASDAQ:AMZN | AMZN Price Prediction) trades at $251.40. The stock has given back part of its post-earnings rally even though AWS is growing at its fastest pace in 18 quarters.
Amazon runs the world’s largest e-commerce operation and the leading cloud platform, and it is spending at a record pace to stay on top. Management plans roughly $200 billion in capex this year. Alongside that expansion came the “Built Together” push: a $1 billion investment in AWS Forward Deployed Engineering, with early customers including the NFL, NBA and Southwest Airlines (NYSE:LUV). Shares rose to $274.48 a week after the report, then slid back.
AWS Acceleration Gives Bulls a Record Backlog to Point To
AWS revenue rose 36.7% to $42.2 billion, with a 39.4% operating margin. Backlog hit $496 billion. The AI and chips businesses each run above $25 billion annually with triple-digit growth. OpenAI committed about 2 GW of Trainium capacity, and Anthropic will secure up to 5 GW.
Demand is already locked in. The CEO said the lion’s share of 2027 capacity is reserved, and servers break even in a little under three years on contracts of at least five years. Analysts back it: 58 rate it Buy.
Negative Free Cash Flow Shows Where the Push Is Straining
The spending has exceeded the cash. Trailing free cash flow turned negative at -$7.6 billion after quarterly capex of $54.21 billion, up 68.4%. The company’s long-term debt reached $119.1 billion, up from $65.6 billion. The free cash flow yield is a thin 0.28%.
Earnings quality is unclear too. GAAP EPS of $5.75 leaned on a $53.4 billion Anthropic gain, while comparable EPS was $1.88. Management never mentioned Forward Deployed Engineering on the earnings call, and memory, hard drive and SSD inflation is pressuring costs. Sentiment has slid 6.21 points in 30 days.
Capacity Timing Decides Who Wins This Argument
The CEO admitted data center capital goes out two years before servers start making. That leaves a gap between spending and revenue. Profits are still growing: operating income rose 43.2%, so the bear case has limits. Negative cash flow caps the upside too.
It would take three things to settle this: Q3 operating income against guidance of $22.5 billion to $26.5 billion, steady AWS margins, and early revenue from Forward Deployed Engineering customers.
Shares Lag the Market Since Their Post-Earnings Peak Despite a 31% Target Gap
The average analyst target of $330.59 implies 31.5% upside. That target comes from 60 rated analysts, and targets carry no guarantee:
- Buy: 58
- Hold: 2
The stock trades at about 35 times earnings and is up 8.92% year to date. Since the Q2 report, it has gained 9.3% while the S&P 500 rose 3.7%. Since its post-earnings peak, though, Amazon has fallen 8.4% while the S&P 500 added 0.2%.
Data Center Cash Flow Is the Test Investors Cannot Ignore
At $251.40, Amazon’s case depends on cash flow.
The business is strong and the cash flow is weak. The upside improves if Q3 operating income lands near the top of guidance and AWS margins hold near 39% despite component inflation. The downside improves if capex goes well beyond $200 billion while AWS growth stalls. Market-implied probability of 2026 capex topping $210 billion stands at 71%.
Each quarter, compare capex with operating cash flow, which was $45.39 billion last quarter. Track how Amazon reports the backlog, and look for any revenue tied to Forward Deployed Engineering. The market has already reduced much of the post-earnings premium. The current price assumes capacity due online through 2027 will be fully used (a free report on seven AI infrastructure names covers the power, cooling, and networking suppliers feeding that expansion, here).
Watch whether the data centers Amazon is paying for start producing cash.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.