This Wall Street Firm Just Put a $3,000 Price Target on Micron Stock
One Wall Street firm just slapped a price target on Micron so far above the Street consensus that it demands either serious examination or serious skepticism, and the argument behind it could change how you think about memory stocks entirely.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
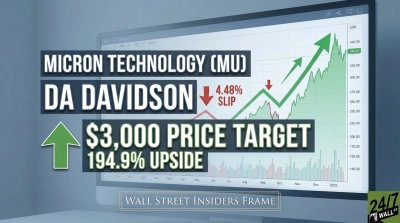
DA Davidson raised its price target on Micron Technology (NASDAQ:MU | MU Price Prediction) to $3,000, according to DA Davidson from $2,100, according to DA Davidson and kept its Buy rating. That is an aggressive target. Against the current share price of $1,017.37, DA Davidson’s target means 194.9% upside. The call comes as Micron stock has slipped 4.48% over the past week and 2.7% in premarket trading, after a 256.68% gain so far this year.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| MU | Micron Technology | DA Davidson | Price target raised | Buy | Buy | $2,100 | $3,000 |
A price target is one analyst’s estimate of where a stock could trade, usually over about the next 12 months. It is an opinion, and it guarantees nothing. The Street’s average target is $1,535.57, so DA Davidson stands well apart from the consensus.

Why DA Davidson Says Micron Trades on the Wrong Multiple
DA Davidson argues that “investors are early in their journey of understanding Micron’s value, and that journey will lead them to assigning a far higher multiple.”
A multiple is the price investors pay for each dollar of earnings. Memory manufacturers have historically traded at low multiples because their profits swing hard with each pricing cycle. Micron trades at a trailing P/E of 14 and about 7x forward earnings. DA Davidson’s view is that AI has made memory a durable growth business, and durable growth businesses earn higher multiples.
What Has to Go Right for $3,000, according to DA Davidson
The case needs several years of strong growth to play out. Micron has signed 26 Strategic Customer Agreements, which it expects to cover over 35% of revenue through 2030, leaving about $150 billion in outstanding contract commitments. The CFO said “even at floor prices, we expect margins meaningfully above any prior cycle peak margins.”
Three things to track:
- Revenue growth in every quarter of fiscal 2027, starting from guidance of $61.5B ± $1.5B
- Gross margin holding above the fiscal Q1 floor of about 86.25%
- Agreement coverage moving toward management’s target of about 50% of revenue
Bear Case Investors Cannot Ignore
Memory has gone through severe downturns in the past, and supply is on the way. Micron expects first-half fiscal 2027 capex of about $25 billion, with new fabs coming online between mid-calendar 2027 and calendar 2030. If rivals add capacity at the same time, pricing could reverse quickly. Barron’s says the stock needs a memory price test. Reuters reports that a Micron union in Taiwan has approval to strike.

The call comes after a 433.3% one-year gain, in a stock with a beta of 2.226. That beta means the stock has historically moved more than twice as much as the broader market.
Credible Call or a Stretch?
The multiple argument is credible. Multi-year contracts, cash down payments and sold-out capacity give Micron more visibility than it has had in any earlier cycle. The $3,000 number is a stretch on a 12-month horizon, though, according to DA Davidson. Getting there requires a repricing the rest of the Street has not yet accepted. For retirement-focused investors, this call is a reason to research Micron more closely, with attention to the stock’s history of sharp swings (we studied the traits early-stage AI winners shared before their monster runs in a free playbook here: The Next Nvidia Playbook).
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.