Cisco Could Be Entering a New Growth Phase. Here’s My Price Target.
Cisco just posted its fifth straight earnings beat while AI infrastructure orders piled up, but the real question is whether the valuation still leaves room to run or whether this rally has already priced in the upside.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
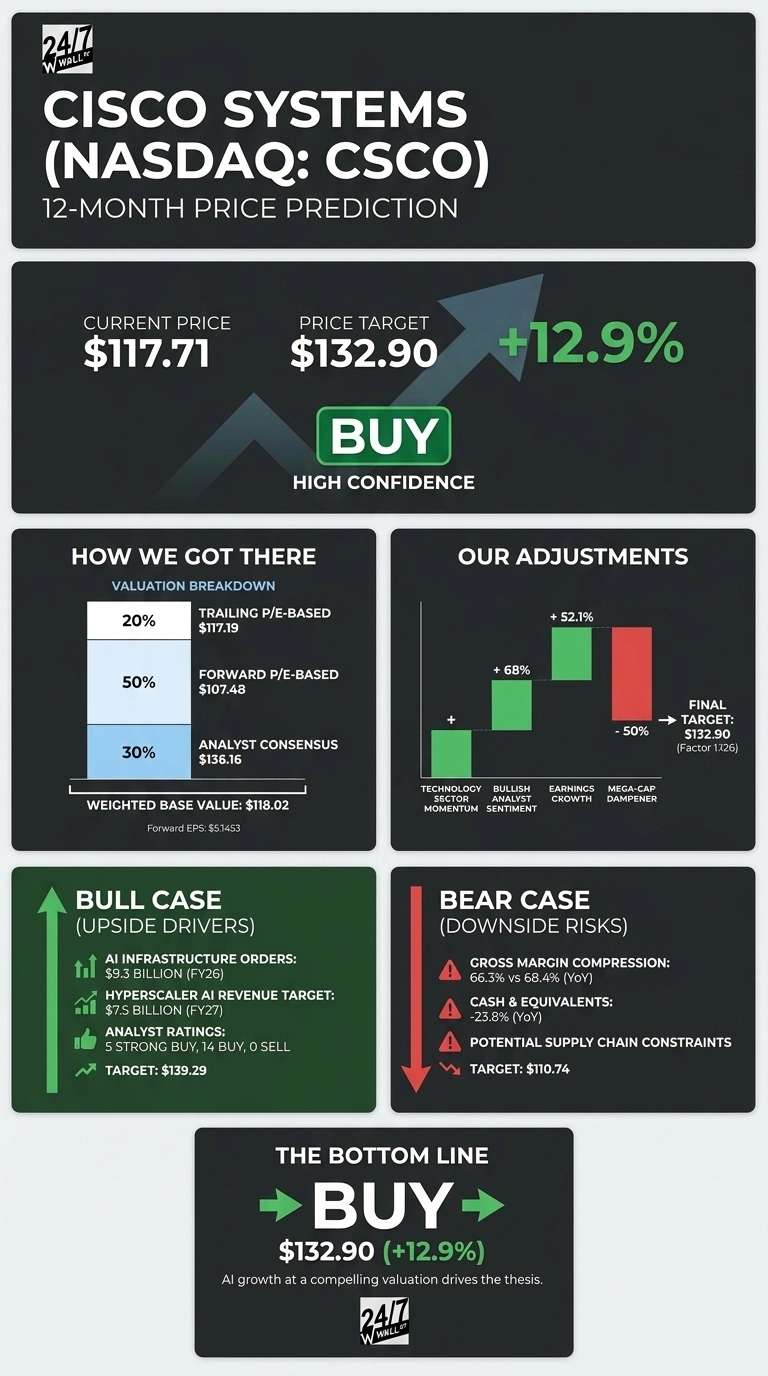
The 24/7 Wall St. price target for Cisco Systems (NASDAQ:CSCO | CSCO Price Prediction) is $132.90 over the next 12 months. Shares trade at $117.71 this morning, so the target means 12.9% upside. The model gives Cisco a buy rating with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $117.71 |
| Price Target from 24/7 Wall St. | $132.90 |
| Upside | 12.9% |
| Recommendation | BUY |
| Confidence Level | 90% |
Cisco has changed from a slow-growth dividend payer into one of the cleaner ways to own AI networking. Our target sits a bit below the consensus analyst target of $136.16 because the model reduces mega-cap upside on purpose. Even so, it points higher from here.

AI Orders Fueled a 55.6% Rally This Year
Cisco is up 10.48% over the past week, 8.2% over the past month and 55.6% year to date. Shares sit 9% below the 52-week high of $129.38 and 79.4% above the low of $65.60.
Fiscal Q4 revenue came in at $17.25 billion, up 17.6% and ahead of the $16.83 billion estimate. Non-GAAP EPS of $1.22 exceeded the $1.17 consensus, Cisco’s fifth straight beat. AI infrastructure orders reached $9.3 billion for fiscal 2026. Management forecast fiscal 2027 revenue to $72.2 billion to $73.4 billion and EPS to $5.05 to $5.11.

Why Bulls See $139 and Beyond
Our bull case reaches $139.29. Hyperscaler AI revenue is expected to hit $7.5 billion in fiscal 2027. Cisco also holds three P200 scale-across design wins, and Wi-Fi 7 now makes up more than 50% of wireless orders.
CEO Chuck Robbins said, “We believe we’re only at the beginning of this super cycle.” Analysts agree: 5 rate Cisco a Strong Buy, 14 a Buy and 9 a Hold, and none rate it a Sell.

Margin Pressure Is the Risk to Watch
Our bear case comes to at $110.74. Non-GAAP gross margin slid to 66.3% from 68.4%, and the CFO warned of “a slight gross margin headwind” through fiscal 2027.
Price increases added about five points to Q4 growth, which flatters volume. To be fair, operating margin still rose to 35.9% from 34.3%. Cash fell 23.8%, but that reflects $12.7 billion returned to shareholders.
Cisco Looks Cheap Next to Arista and HPE
Arista Networks (NYSE:ANET) is Cisco’s most direct AI data-center rival. Arista increased revenue 37.69% last quarter but trades at 77x earnings. Cisco trades at an implied 27x trailing and 23x forward earnings.
Hewlett Packard Enterprise (NYSE:HPE) is now a larger enterprise networking rival after buying Juniper Networks. Its networking revenue increased 74.9%, a figure raised by the deal, while its non-GAAP operating margin was 16.2%. The 24/7 Wall St. price target looks conservative against both peers.
| Company | P/E | Latest Qtr Revenue Growth | Non-GAAP Op. Margin |
|---|---|---|---|
| Cisco | 27 | 17.6% | 35.9% |
| Arista | 77 | 37.69% | 49.9% |
| HPE | 1,643 | 32.72% | 16.2% |
Cisco Price Prediction 2026-2030
The 24/7 Wall St. price target of $132.90 comes with a buy rating and 90% confidence. What tips the scale for me is AI growth at a valuation far below Arista’s (we rounded up seven companies driving the AI data-center expansion, from power to networking, which you can find here).
The setup strengthens if hyperscaler AI revenue tracks toward $7.5 billion while operating margin holds near 35%. It weakens if gross margin compression speeds up or hyperscaler orders stall. On the current data, Cisco’s new growth phase looks real.
The 24/7 Wall St. price target model projects where Cisco could trade, assuming current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $121.63 |
| 2027 | $133.14 |
| 2028 | $146.53 |
| 2029 | $160.22 |
| 2030 | $171.46 |
The projections assume Cisco keeps executing on Silicon One, optics and security. Big moves either way could come from changes in hyperscaler capital spending or tariff policy.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.