HPE Is the Quiet AI Winner Trading Near Its 52-Week High
HPE just shattered its 52-week high on a single session surge, yet its forward multiple still sits far below every major competitor building the same AI infrastructure boom. Something in the valuation math does not add up.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
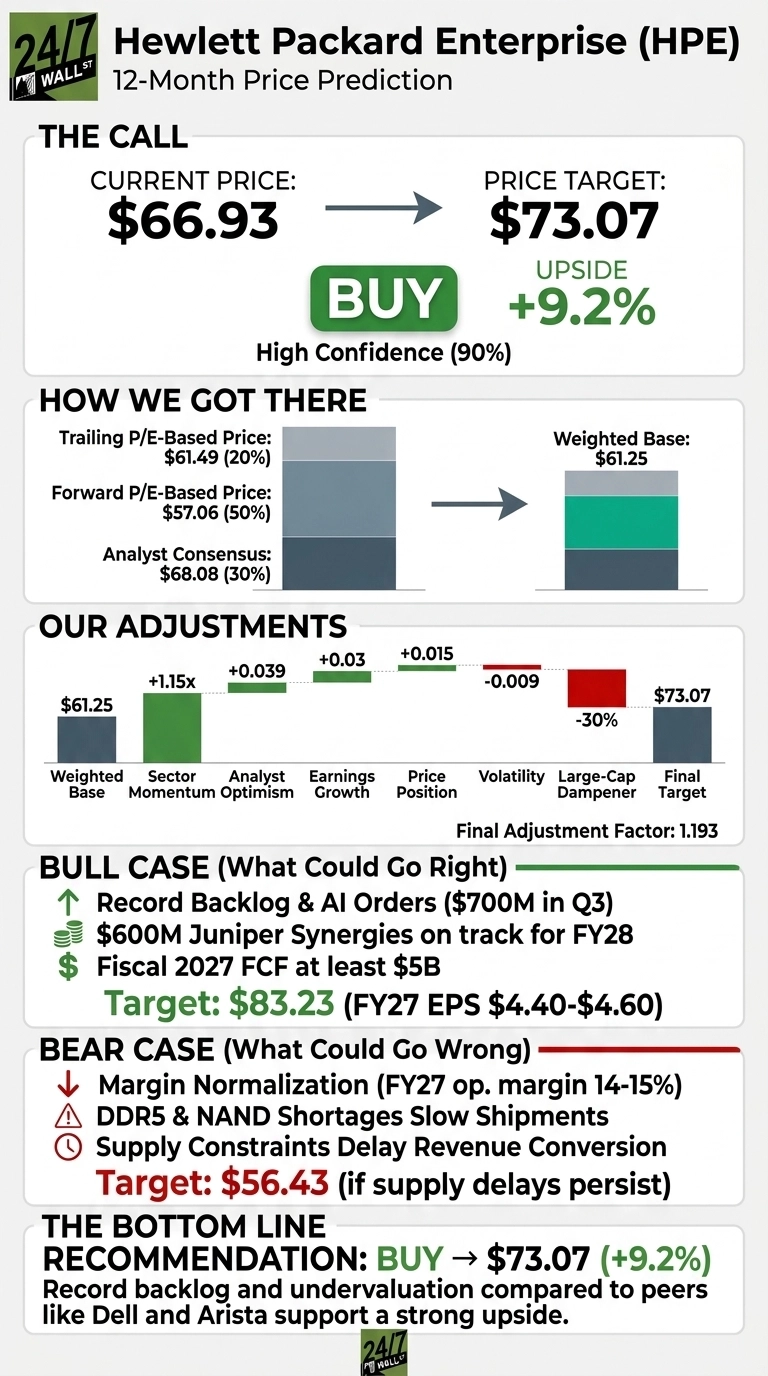
Hewlett Packard Enterprise (NYSE:HPE | HPE Price Prediction) trades at $66.93 this morning. That is up 8.85% on the session as AI demand keeps raising its networking business. Our 24/7 Wall St. price target for HPE is $73.07 over the next 12 months. The model rates it a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $66.93 |
| Price Target from 24/7 Wall St. | $73.07 |
| Upside | 9.2% |
| Recommendation | BUY |
| Confidence Level | 90% |

We ran the model off Tuesday’s close of $61.49, showing to 18.84% upside. Today’s jump cuts the remaining gap to 9.2%. Our confidence rests on five straight EPS beats, guidance raised through fiscal 2027, and zero Sell ratings on the Street.

Record Q3 Results Pushed HPE Past Its Prior 52-Week High
HPE is up 9.67% over the past week, 28.25% over the past month and 181.79% year to date. Today’s price sits above its prior 52-week high of $65.65 and far above the $19.57 low.
Fiscal Q3 revenue hit $12.21B, up 32.7%, exceeding the $11.91B consensus. Non-GAAP EPS of $1.11 cleared the $0.93 estimate. Networking revenue rose 74.9% to $2.89B, and routing went up 270%. HPE announced a $3.5 billion inferencing server deal with a hyperscaler and expanded work with Oracle (NYSE:ORCL) on gigawatt-scale AI networking.
The AI expansion keeps pulling in suppliers well beyond the chipmakers, and networking gear like HPE’s is a big part of the plumbing (we covered seven of these non-chip AI infrastructure names in a free report available here: 7 Stocks Powering the AI Boom).
Why Bulls See $83 and Beyond
In the model’s bull case, HPE reaches $83.23. Management’s fiscal 2027 framework calls for EPS of $4.40 to $4.60 and free cash flow of at least $5 billion. That framework leaves out the AMD (NASDAQ:AMD) Helios opportunity, which the CEO sized at “tens of billions of dollars” across the market.
Networks for AI orders reached $700 million in the quarter. Juniper synergies are on track for $600 million in annual run-rate savings by FY28.
The Street is supportive, with 5 Strong Buy ratings, 10 Buys and 8 Holds. The stock already trades above the $68.08 consensus target, so analysts may raise their numbers.

Margin Normalization Is the Risk Worth Watching
Under a downside scenario, HPE slips to $56.43. Management expects gross margin to normalize as AI systems grow. Operating margin guidance of 14-15% for FY27 trails Q3’s 16.2%. Stripping out Juniper, networking grew just 10%.
DDR5 and NAND shortages slow shipments. Orders outpace revenue: networking orders rose 36% with record backlog, suggesting supply delays revenue rather than kills demand.
HPE Trades at a Steep Discount to Dell and Arista
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| HPE | 14x | 33.7% |
| Dell | 21x | 57.7% |
| Arista | 39x | 37.7% |
Dell Technologies (NYSE:DELL) competes directly for AI server spending. Dell grows faster, earning a higher forward multiple. HPE’s larger networking mix yields higher margins that its 14x forward P/E does not reflect.
Arista Networks (NYSE:ANET) competes head-on in data center switching. Arista’s operating margin is 45.4% versus 12.6% for HPE, explaining most of its premium. HPE’s networking margin is guided to the mid to high 20% range, so part of that gap should close. Our target of about 15x forward earnings looks conservative.
HPE’s Backlog Tips the Scale Toward Upside
Our $73.07 target carries a buy rating with 90% confidence. A record backlog priced at a valuation well below peers tips the scale toward upside.
The case strengthens if supply eases and backlog turns to revenue in Q4. It weakens if gross margins contract faster than networking growth can offset. HPE’s valuation still falls behind its fundamentals.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $63.11 |
| 2027 | $77.21 |
| 2028 | $85.24 |
| 2029 | $93.56 |
| 2030 | $102.38 |
These projections assume HPE keeps executing on its networking-led strategy. A strong Helios ramp could drove results higher, while long-running memory shortages could hold them back.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.