Lock In Growing Quarterly Dividends With These 3 Industrial Suppliers Customers Refuse to Leave
Switching suppliers sounds simple until you realize a vendor's hardware is bolted to your shop floor, its software runs your purchasing, and its staff restocks your bins. Three industrial distributors have built that kind of grip, and their dividends keep…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
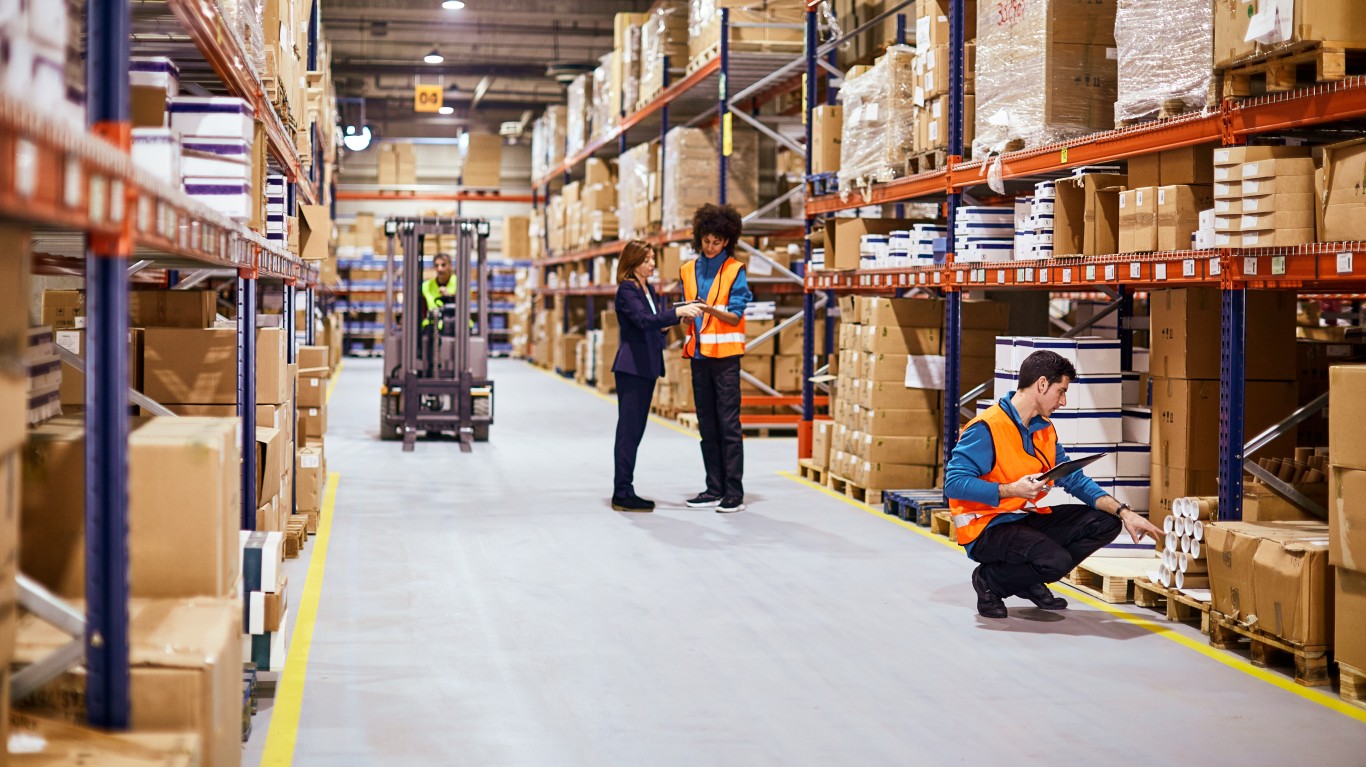
Anyone can buy a box of bolts. What a factory has trouble to replace is the supplier whose vending machines sit on its shop floor, whose staff restock its bins, and whose software runs its purchasing. That embedded position is the common thread between W.W. Grainger (NYSE:GWW | GWW Price Prediction), Fastenal (NASDAQ:FAST) and MSC Industrial Direct (NYSE:MSM). All three are dividend growers, and the case rests on payouts that keep rising because customers find these suppliers too costly to leave. Fastenal alone ended its latest quarter with 140,789 weighted FASTBin/FASTVend installations inside customer facilities.
How Industrial Distribution Locks In Customers
Industrial distributors sell the commonplace supplies that keep plants running: fasteners, cutting tools, gloves, safety glasses, janitorial goods and replacement parts. Their customers are manufacturers, contractors, government facilities and warehouses. The products are commodities. The moat comes from four things: products being in stock when a line goes down, a catalog broad enough to cover thousands of part numbers, inventory the distributor handles inside the customer’s own building, and the work it would take to rip that setup out.
A vending machine on the plant floor hands out drill bits and gloves to badge-scanned workers, tracks use by department, and triggers its own reorders. If the plant switches suppliers, someone has to pull the hardware, remap thousands of SKUs into the purchasing system, retrain the floor, and accept the risk of stockouts during the transition. For a box of gloves, few plant managers want that headache. That inertia is what lies behind these dividends.
W.W. Grainger: A Decade of Raises Backed by a Light Payout
Grainger offers the smallest yield of the three, at about 0.78% on its annualized forward dividend of $9.96. The compensation is safety and growth. Trailing dividends of $9.27 per share equal roughly 23.6% of trailing earnings of $39.21. The forward dividend works out to about 21.9% of the low end of management’s adjusted EPS guidance of $45.50-$47.25. There is ample room to keep raising.
The record supports it. The quarterly dividend moved from $1.22 in early 2017 to $2.49 now, with a raise every year in between. The latest increase came to 10.2%. The payment history also shows the quarterly amount climbing steadily from $0.15 in 1999. Cash flow supports the habit: free cash flow came in at $333M last quarter, up 64.85%, while Grainger paid $108M in cash dividends in the first quarter. Full-year operating cash flow guidance is $2.25B-$2.4B.
Its customers stay because its High-Touch Solutions segment works inside large national accounts through on-site KeepStock inventory programs. Management put it plainly: “We’re helping them manage inventory in ways that fit their specific needs, and that is contributing to strong year-over-year growth at these locations.” That segment posted a 17.3% operating margin.
Bull case: Second-quarter diluted EPS of $12.01 beat the $11.30 estimate, and management raised its outlook, citing “the continued momentum we are seeing across the demand environment.” The stock trades at roughly 25 times forward earnings, per consensus data.
Risk: Management noted rising freight and product costs tied to the conflict in the Middle East, along with ongoing tariff changes. Pricing actions have to keep pace to protect High-Touch margins.
Fastenal: Vending Machines Bolted Into Customer Plants
Fastenal yields about 2.07% on its annualized forward dividend of $1.04. The quarterly payout went from $0.22 to $0.24 and then to $0.26 over its last three announcements, about 18.2% in total. Dividend records go back to 1999.
Coverage is lower than Grainger’s. Trailing dividends of $0.92 equal about 78.6% of trailing EPS of $1.17, and last year’s dividends came to 79.8% of net income. Free cash flow of $1,050.6 million last year covered $1,004.2 million in dividends. In the latest quarter, free cash flow of about $201.6 million fell short of $275.4M in dividends, as receivables grew on June sales growth of 20%. That is easily absorbed: $1.2247B in total liabilities against $4.0688B in equity.
Fastenal is hard to replace because its devices sit inside customer plants. Contract customers now make up 75.8% of revenue, and customer sites spending $50,000 or more a month grew 16 and a half percent. Jeff Watts, President and Chief Sales Officer at the time of the July call, called the devices “deposits into next quarter’s sales, into next year’s retention.”
Bull case: Daily sales grew 14.7% in the quarter on share gains, and the delivery network gives Fastenal a cost edge. As Dan Florness said on what was his final call as CEO, “our costs are at a discount to any other option that’s out there.”
Risk: Gross margin contracted roughly 75 basis points as larger, lower-margin accounts grew faster. With the stock at about 37 times forward earnings, per consensus data, the valuation leaves little room for more margin decline.
MSC Industrial Direct: Bigger Yield, Thinner Cushion
MSC pays the most current income of the group, about 2.66% on a forward dividend of $3.48. Regular quarterly payments go back to 2003, and the payout has stepped up from $0.75 to $0.79, $0.83, $0.85 and now $0.87. The raises are getting smaller, though. The latest was only 2.4%.
The payout leaves less buffer. Dividends equal about 84.1% of trailing EPS of $4.14. Last fiscal year, free cash flow of $240.877 million covered roughly $189.7 million in dividends. Net debt sits around $433 million, or about one times EBITDA, and management targets free cash flow conversion of ~95%.
MSC holds on to customers through about 30,800 installed vending machines and 426 in-plant programs. Vending accounts for about 20% of net sales, and customers with in-plant programs account for about 21%. Daily sales through vending rose 15%.
Bull case: Fiscal third-quarter adjusted EPS of $1.43 beat the $1.26 estimate, and GAAP operating margin expanded to 10.2%. Management is targeting a mid-teens operating margin, which would give the dividend more room to grow.
Risk: Growth still leans on price. Pricing contributed 720 basis points of growth versus 50 basis points from volume, and the company will soon lap stronger pricing benefits.
One Risk All Three Share
These businesses rise and fall with factory output, so they offer no shelter in a recession. Heavy manufacturing makes up 44% of Fastenal’s sales, and MSC’s chief executive says “We’re still a short cycle business.” An industrial slowdown would hit all three at once. Switching costs protect market share. They do nothing to protect volume when customers’ own plants slow down.
Why These Three Belong Together
Grainger has the deepest coverage and the longest verified run of raises. Fastenal has the most hardware inside customer plants. MSC pays the most today but carries the smallest payout buffer. Customer lock-in supports all three dividends, and industrial demand will decide how fast each one grows. For readers building around names that keep paying without forcing a sale, we laid out a full dividend ladder in a free guide here.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.