Market Concentration Is Spooking Wall Street—I’m Buying Kenvue

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
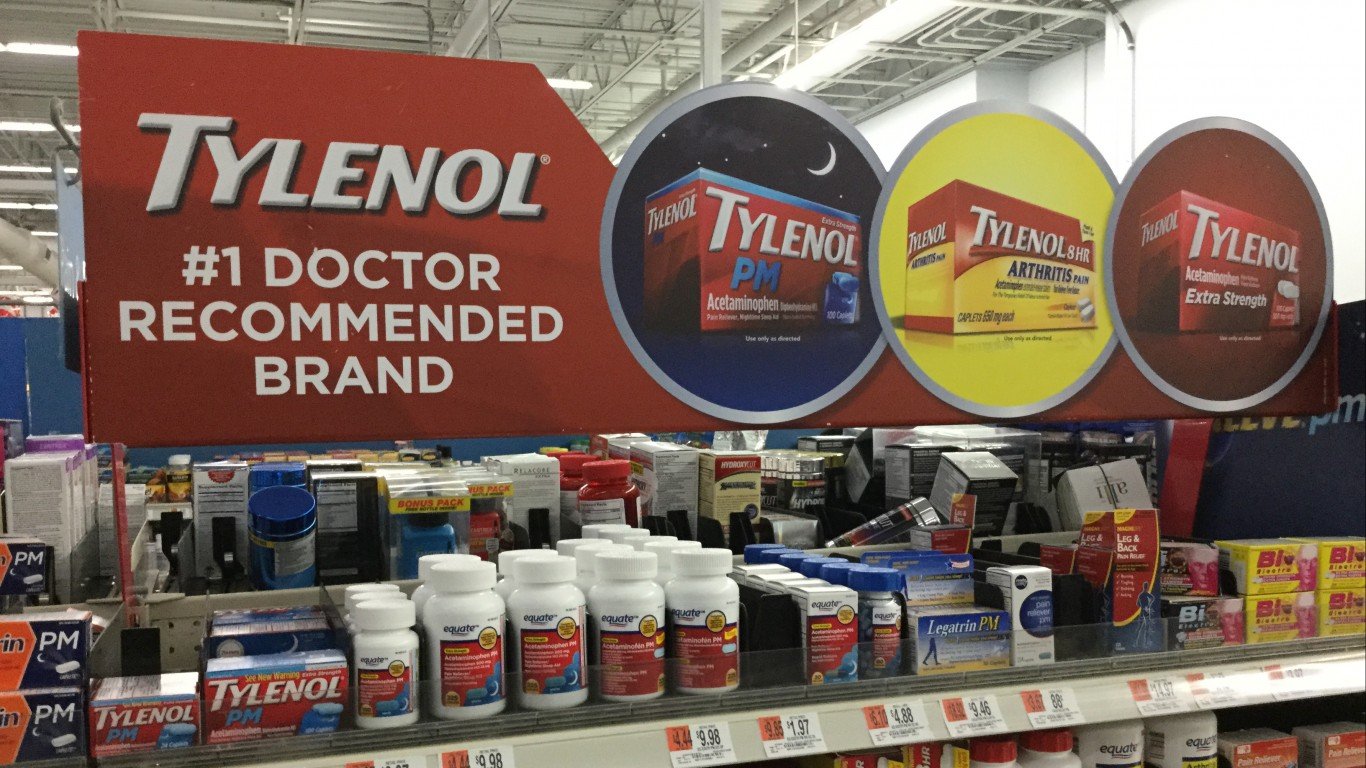
I regularly add to Kenvue (NYSE:KVUE | KVUE Price Prediction) every time fresh cash lands in my account. Wall Street worries that too much of the market rests on a handful of tech giants. Meanwhile, I keep moving money into Tylenol, Listerine, Band-Aid and Neutrogena. People restock those products in good times and bad ones, and I want that durability as I get closer to living off my portfolio.
Why My Buy Button Stays Warm
My view is simple. Kenvue owns brands that families repurchase without a second thought. Kimberly-Clark (NASDAQ:KMB) agreed to buy Kenvue in a $48.7 billion deal that offers $3.50 cash + 0.14625 KMB shares per KVUE share. The deal has passed HSR review and won shareholder approval, with closing expected in Q4 2026 once foreign regulators sign off.
Three Reasons I Keep Adding
Income comes first. Kenvue pays $0.21 per quarter, for an annualized forward dividend of $0.84. At $17.54, that yields roughly 4.8%. Since 2023, the quarterly payout has rose from $0.20 to $0.21.
Second, the business turned. In its second quarter, Kenvue delivered “our third consecutive quarter of net and organic sales growth.” Revenue rose 3.0% to $3.955 billion, and Skin Health & Beauty grew 5.1%. Full-year 2025 free cash flow rose 27.34% to $1.7 billion.
Third, the price looks reasonable. At $17.54, Kenvue trades at about 16 times its FY2025 EPS of $1.08. With Kimberly-Clark at $96.48, the deal terms mean about $17.61 per Kenvue share. That sets my purchase price at roughly what the deal offers.
Why My Money Skips Procter & Gamble
Procter & Gamble (NYSE:PG) is the reflexive staples pick. At $147.82, it trades near 21 times fiscal 2026 core EPS of $6.89. Its $1.0885 quarterly dividend yields about 2.9%. Organic sales came in flat in its latest quarter, and management guided fiscal 2027 core EPS anywhere from in-line to up 3%. I’d rather collect 4.8% at 16 times earnings.
Kimberly-Clark pays $1.28 per quarter, about 5.3%, and has raised its dividend for 54 consecutive years, putting it in the rare Dividend Kings club (we ranked ten of them by valuation in a free report here). I prefer coming in through Kenvue. Each share delivers $3.50 in cash at closing, plus about $0.75 a year in Kimberly-Clark dividends at today’s rate.
Risks That Could Break This Position
Foreign regulators could block or delay the deal. If that happens, Kenvue trades on its own with $8.7 billion in debt and no forward guidance. Its adjusted gross margin fell 70 bps to 60.2% on inflation and tariffs. Second-quarter adjusted EPS of $0.31 missed the $0.319 consensus. Tylenol misinformation and UK talc litigation remain open. With the 10-year Treasury yielding 5.27%, bonds compete hard for income dollars.
That does not change my view. Even without the deal, I would own a stock yielding 4.8% at 16 times earnings, with sales growing and free cash flow rising.
What Keeps Me Buying From Here
Kenvue shares are up 14.63% over the past year but down 5.29% over the past month. Perry said “Our transformation is firmly on track.” The numbers back him up. While the market argues over a handful of tech names, I’ll keep collecting dividends from the brands in America’s medicine cabinet.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.