Market Concentration Is Spooking Wall Street—I’m Buying Kenvue
While nervous investors obsess over a handful of tech giants propping up the whole market, one portfolio manager keeps funneling fresh cash into the brands sitting in every American medicine cabinet, and the reasoning might make you rethink your own…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
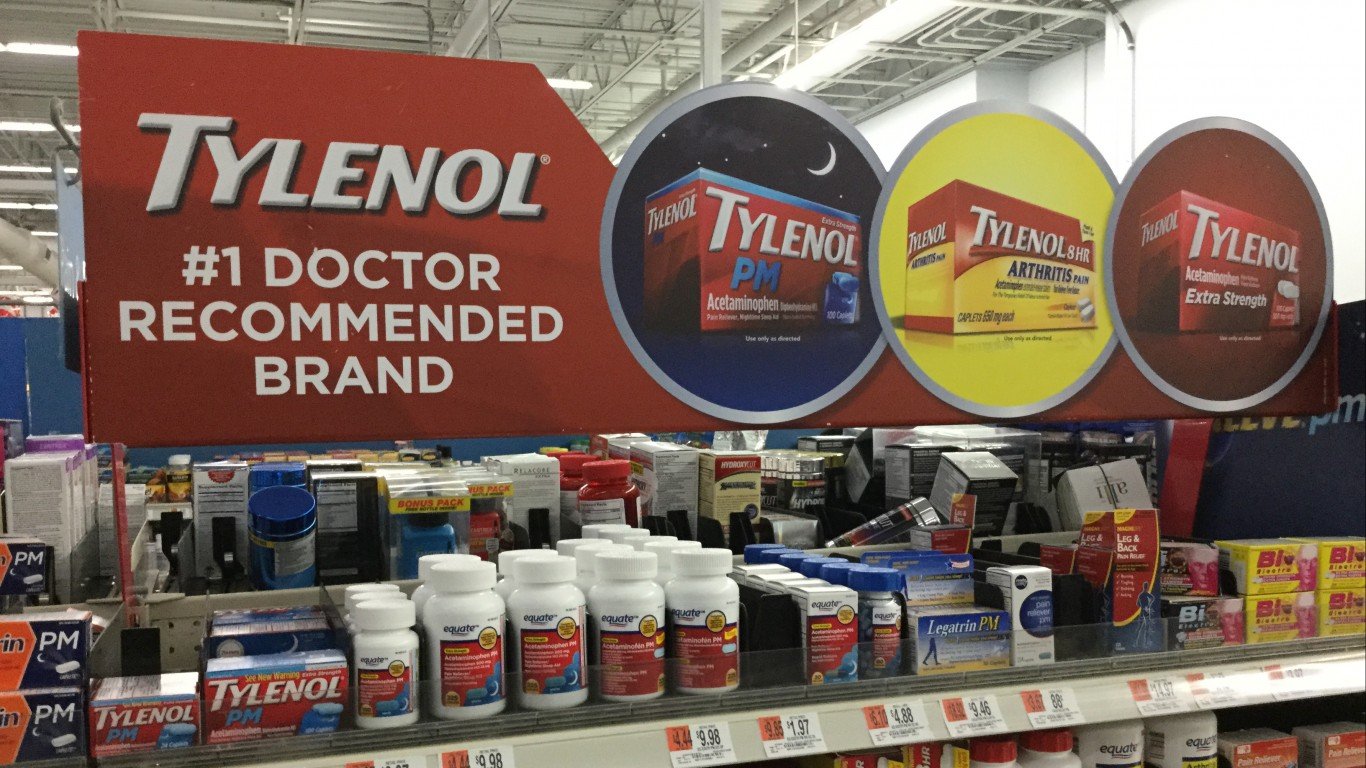
I regularly add to Kenvue (NYSE:KVUE | KVUE Price Prediction) every time fresh cash lands in my account. Wall Street worries that too much of the market rests on a handful of tech giants. Meanwhile, I keep moving money into Tylenol, Listerine, Band-Aid and Neutrogena. People restock those products in good times and bad ones, and I want that durability as I get closer to living off my portfolio.
Why My Buy Button Stays Warm
My view is simple. Kenvue owns brands that families repurchase without a second thought. Kimberly-Clark (NASDAQ:KMB) agreed to buy Kenvue in a $48.7 billion deal that offers $3.50 cash + 0.14625 KMB shares per KVUE share. The deal has passed HSR review and won shareholder approval, with closing expected in Q4 2026 once foreign regulators sign off.
Three Reasons I Keep Adding
Income comes first. Kenvue pays $0.21 per quarter, for an annualized forward dividend of $0.84. At $17.54, that yields roughly 4.8%. Since 2023, the quarterly payout has rose from $0.20 to $0.21.
Second, the business turned. In its second quarter, Kenvue delivered “our third consecutive quarter of net and organic sales growth.” Revenue rose 3.0% to $3.955 billion, and Skin Health & Beauty grew 5.1%. Full-year 2025 free cash flow rose 27.34% to $1.7 billion.
Third, the price looks reasonable. At $17.54, Kenvue trades at about 16 times its FY2025 EPS of $1.08. With Kimberly-Clark at $96.48, the deal terms mean about $17.61 per Kenvue share. That sets my purchase price at roughly what the deal offers.
Why My Money Skips Procter & Gamble
Procter & Gamble (NYSE:PG) is the reflexive staples pick. At $147.82, it trades near 21 times fiscal 2026 core EPS of $6.89. Its $1.0885 quarterly dividend yields about 2.9%. Organic sales came in flat in its latest quarter, and management guided fiscal 2027 core EPS anywhere from in-line to up 3%. I’d rather collect 4.8% at 16 times earnings.
Kimberly-Clark pays $1.28 per quarter, about 5.3%, and has raised its dividend for 54 consecutive years, putting it in the rare Dividend Kings club (we ranked ten of them by valuation in a free report here). I prefer coming in through Kenvue. Each share delivers $3.50 in cash at closing, plus about $0.75 a year in Kimberly-Clark dividends at today’s rate.
Risks That Could Break This Position
Foreign regulators could block or delay the deal. If that happens, Kenvue trades on its own with $8.7 billion in debt and no forward guidance. Its adjusted gross margin fell 70 bps to 60.2% on inflation and tariffs. Second-quarter adjusted EPS of $0.31 missed the $0.319 consensus. Tylenol misinformation and UK talc litigation remain open. With the 10-year Treasury yielding 5.27%, bonds compete hard for income dollars.
That does not change my view. Even without the deal, I would own a stock yielding 4.8% at 16 times earnings, with sales growing and free cash flow rising.
What Keeps Me Buying From Here
Kenvue shares are up 14.63% over the past year but down 5.29% over the past month. Perry said “Our transformation is firmly on track.” The numbers back him up. While the market argues over a handful of tech names, I’ll keep collecting dividends from the brands in America’s medicine cabinet.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.