Broadcom Is Building an AI Business Unlike Nvidia’s. Here’s My Price Prediction
Broadcom competes with Nvidia without selling a single GPU to the general market, and that unusual strategy has locked in hyperscaler contracts stretching years into the future. Whether the stock has already priced in that advantage is the question worth…

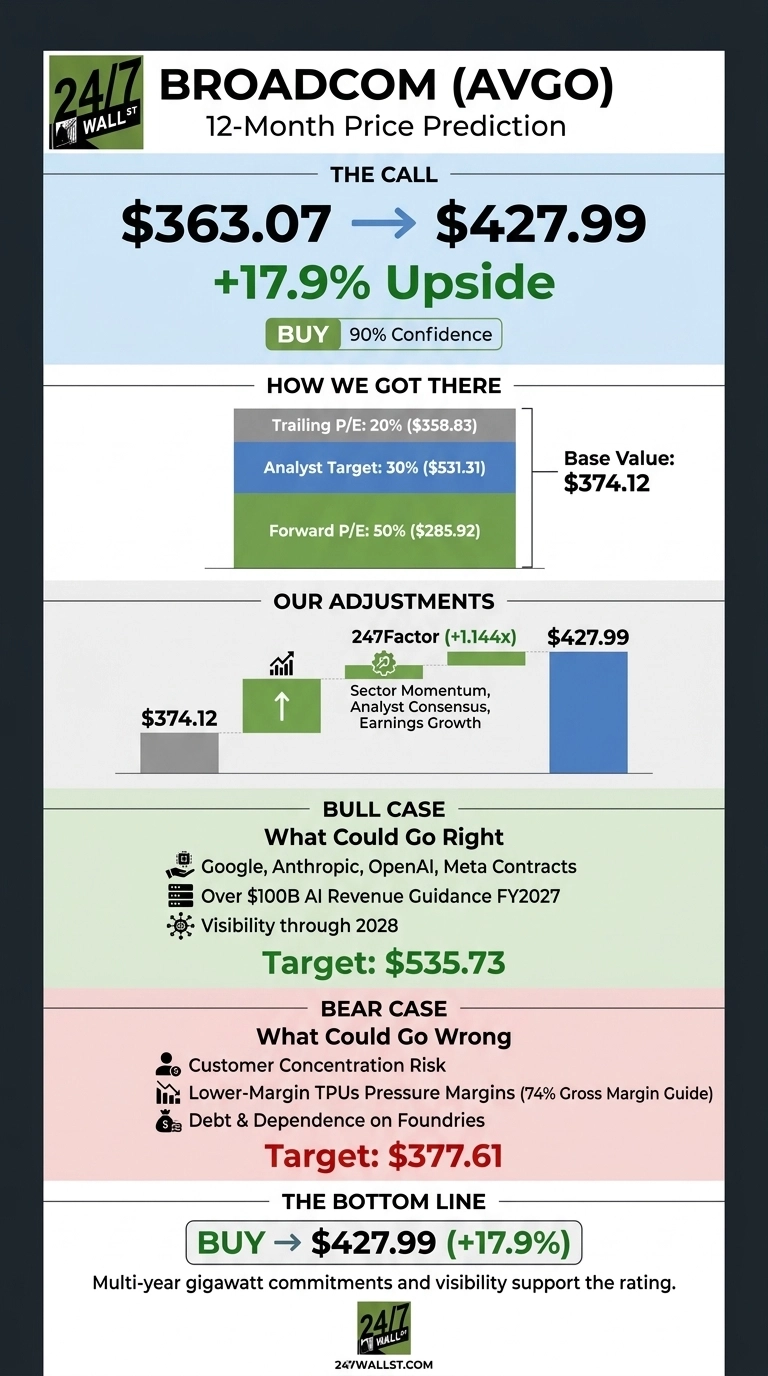
The 24/7 Wall St. price target for Broadcom (NASDAQ:AVGO | AVGO Price Prediction) is $427.99 over the next 12 months. With the stock at $363.07, that works out to 17.9% upside. I rate it a buy, and my confidence is high.
| Metric | Value |
|---|---|
| Current Price | $363.07 |
| Price Target from 24/7 Wall St. | $427.99 |
| Upside | 17.9% |
| Recommendation | BUY |
| Confidence Level | 90% |

Broadcom’s AI business runs on a different model from Nvidia (NASDAQ:NVDA). Nvidia sells merchant GPUs to everyone.
Broadcom co-designs custom accelerators (XPUs) and the Ethernet networking that connects them for a small group of hyperscalers and frontier labs, under multi-generation contracts. That model trades breadth for visibility, and the visibility now runs well into 2028.
Record AI Revenue, but Shares Sit 26% Below the High
The stock gained 5.65% over the past week and is up 5.48% year to date. It sits 26.4% below its 52-week high of $493.28 and 25.7% off its low of $288.95.
The fundamentals have outrun the stock. Fiscal third-quarter revenue rose 85.5% to $29.59 billion, ahead of the $29.44 billion consensus. Non-GAAP EPS of $3.32 exceeded the $3.24 estimate.
AI semiconductor revenue rose 221% to $16.70 billion, and fourth-quarter guidance calls for $21.7 billion in AI sales on total revenue of about $34.8 billion.
Why Bulls See $535 Within Reach
Management has repeated fiscal 2027 AI revenue guidance of in excess of $100 billion, and second-quarter AI bookings exceeded $30 billion. The customer roster keeps growing.
It includes a long-term Google (NASDAQ:GOOGL) TPU agreement, 5 gigawatts of computing power for Anthropic beginning in 2027, an OpenAI program targeting 10 gigawatts by 2029, and 3 gigawatts for Meta Platforms (NASDAQ:META) through 2028.
On the June earnings call, Hock Tan said “Demand for XPUs and networking is simply insatiable.” Wall Street’s consensus target stands at $531.31, with 40 Buy and 7 Strong Buy ratings. The bull case is $535.73.

Concentration and Margin Mix Are the Risks Worth Watching
A handful of customers drive the AI business, and Tan acknowledged that Google expects “some diversity of sources.” Gross margin was 77.1% in the second quarter, and management guided it toward roughly 74% as lower-margin TPUs ramp.
Management described this as product mix rather than a structural decline, while semiconductor operating margin expanded to 62%. Debt and dependence on outside foundries also add risk. The bear case is $377.61.

Broadcom Trades Cheaper Than Nvidia and AMD
Nvidia is the merchant GPU leader that Broadcom’s custom chips compete with directly. Shares trade at about 25x forward earnings, against roughly 19x for Broadcom.
AMD (NASDAQ:AMD), the other merchant accelerator supplier, trades near 40x while growing revenue more slowly than Broadcom.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Broadcom | 19x | 85.5% |
| Nvidia | 25x | 105.9% |
| AMD | 40x | 50.1% |
Broadcom carries the lowest multiple of the three. Next to these peers, the 24/7 Wall St. price target looks conservative.
Broadcom Price Prediction 2026-2030
The 24/7 Wall St. price target of $427.99 carries 90% confidence. Multi-year gigawatt commitments priced at a discount to peers support the rating. The outlook improves if the OpenAI and Meta ramps stay on schedule into 2027. Risks grow if Google moves meaningful TPU volume to other suppliers.
Here is where our model projects Broadcom could trade if current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $379.32 |
| 2027 | $427.99 |
| 2028 | $477.17 |
| 2029 | $531.99 |
| 2030 | $593.12 |
The projections rely on Broadcom continuing to execute its custom silicon strategy.
Faster gigawatt deployments could push results higher, while hyperscaler capex cuts could pull them lower. All of that gigawatt expansion still has to be powered, cooled, and networked by someone, and we highlighted seven suppliers riding that wave in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.