I’m Making a Contrarian Bet on Oracle at What Seems Like The Worst Moment Possible
Oracle shares have shed half their value while the company quietly signed a backlog so large it dwarfs what most investors think the business is worth. Here is why the selloff looks less like a warning and more like a…

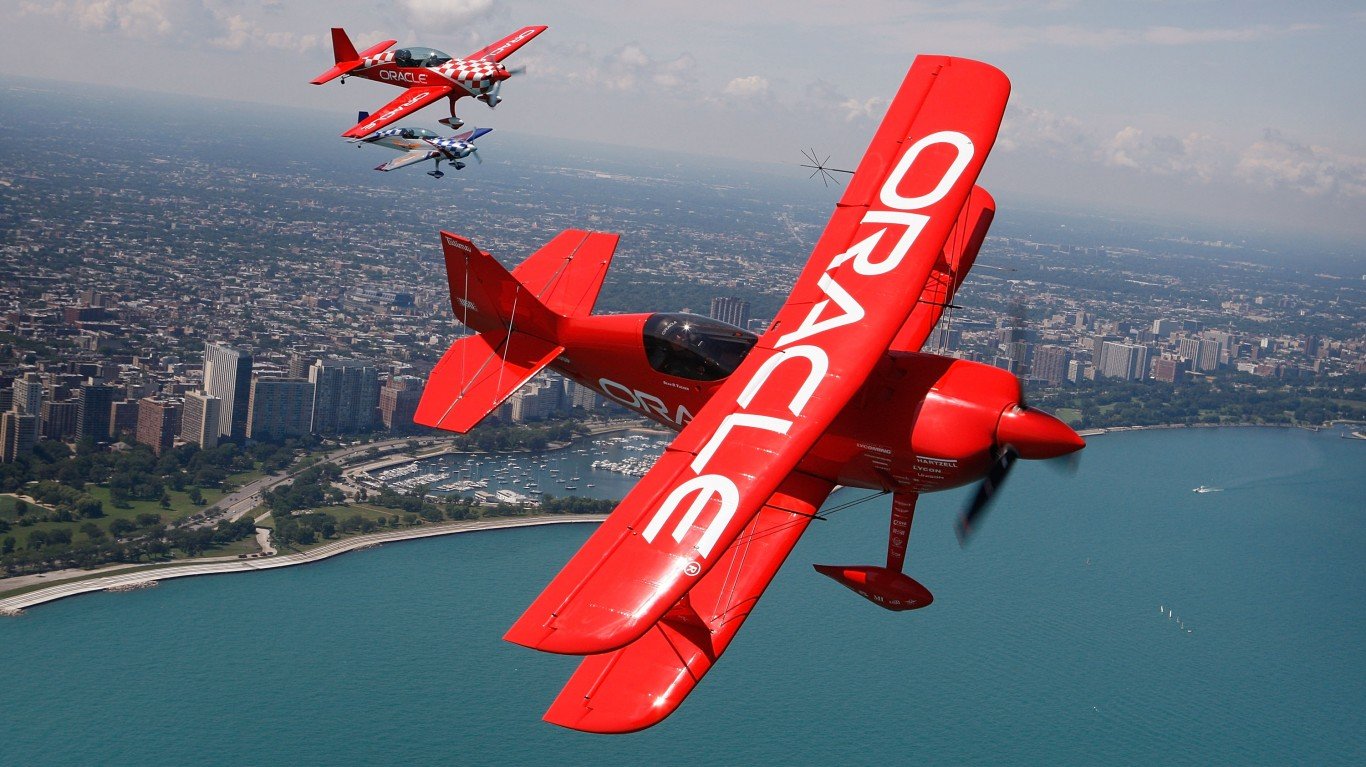
I bought more Oracle (NYSE:ORCL | ORCL Price Prediction) again this month, and every new wave of selling makes me want to buy more. Shares closed at $141.40 on October 9, down 51.75% over the past year and 26.49% year to date. A report on OpenAI’s revenue sent AI stocks lower, and observers now describe an AI credit scare hitting Oracle. When I look past the headlines, I see a growing order book priced below the hyperscalers most investors buy first.
A $664 Billion Backlog Wall Street Keeps Discounting
My conviction comes down to one thing: Oracle has already signed the customers. Remaining performance obligations reached $664 billion, up $209 billion year over year. Oracle booked more than $30 billion in new AI contracts in Q1 alone. Management expects around half of that RPO to convert into sales over the next 36 months.
That conversion has started. Cloud infrastructure revenue rose 121% to $7.39 billion, and cloud now makes up 60% of revenue, up from 48% a year ago. GPU utilization hit 97.9%, and GPUs up for renewal, most of them four years or older, renewed or resold at a 20% premium. That answers my biggest worry about AI hardware losing value fast.
Faster Growth at a Lower Multiple Than Microsoft or Amazon
Oracle grew revenue 29.6% last quarter and carries a forward P/E of 18. Microsoft (NASDAQ:MSFT) is valued at a forward P/E of 25 with quarterly revenue growth of 17.7%. Amazon (NASDAQ:AMZN) trades at a forward P/E of 24, grew revenue 19.6%, and pays no dividend. Oracle gives me more growth per dollar of earnings, plus income.
Oracle pays $0.50 per quarter, a 1.48% yield, versus 0.7% at Microsoft. The record shows quarterly payments since 2009, starting at $0.05. Q1 adjusted EPS of $1.92 beat the $1.74 consensus. Management guides fiscal 2027 to at least $90 billion in revenue and $8.10 in non-GAAP EPS.
Negative Free Cash Flow Is the Risk I Watch Closely
Free cash flow came in at -$5.40 billion as capex rose 235.2% to $28.50 billion. Management expects $90 billion to $95 billion in capex this fiscal year. The company’s interest expense rose 55% to $1.4 billion, and a completed $20 billion equity issuance diluted my stake. On 24/7 Wall St.’s The AI Investor Podcast, the hosts warned that “debt is leverage and leverage causes volatility.” A one-year drawdown past 50% shows it.
My thesis holds because operating cash flow rose 183.82% to $23.10 billion, and cash capex net of customer prepayments was $18 billion. Most new contracts use prepayment or bring-your-own-hardware structures requiring no additional Oracle capital. Oracle’s Hilary Maxson said scaled projects deliver “a free cash flow conversion ratio of something like 100% to post-tax EBITDA.”. Cash stands at $36.37 billion.
Why My Buy Button Stays Active
Q2 guidance calls for cloud revenue growth of 65%-71%. Multicloud database revenue grew 353% across 70 regions, turning rival clouds into distribution partners. Barron’s also reported that an Oracle insider bought stock amid the OpenAI swings. The backlog is signed and the GPUs are full, so the dividend should keep coming as that $664 billion turns into revenue.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.