The Bloom Energy Bull Case Just Got a Lot More Interesting
Bloom Energy shares have already surged over 200% this year, yet Wall Street's consensus target barely budges. A closer look at the numbers reveals why one specific price could still be achievable by 2027.

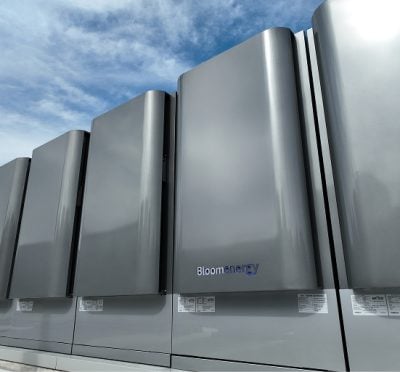
Bloom Energy (NYSE:BE) makes solid-oxide fuel cell “Energy Servers” that generate electricity onsite without burning. AI data centers have made that technology a default choice.
Here is how CEO KR Sridhar put it on the second-quarter call: “Today, all the major US hyperscalers and over a dozen US neoclouds, AI labs, and colocation data center operators have validated and approved our power solutions for their AI factories. Bloom is now a standard for AI onsite power.”
The market has noticed. Shares trade at $273.45, up 214.71% year-to-date and 1327.94% over five years. Here is what Bloom needs to do to hit $450 per share in 2027.
Wall Street’s Target Lags Its Own Rising Estimates
The consensus price target of $283.78 implies just 3.8% upside. Ratings are split, with 12 holds against 15 buy or strong buy ratings. The estimates themselves are more bullish.
Analysts now expect $4.9421 in 2027 EPS, compared with $4.4009 90 days ago, a 12.3% increase. The 2027 revenue consensus of $6.79 billion sits 65% above the 2026 estimate, and EPS is forecast to grow 82.6%.
Bloom also exceeded estimates in five straight quarters, so forecasts have tended to come in too low. In the second quarter, non-GAAP EPS of $0.78 topped the $0.41 estimate, and revenue rose 165.5% to $1.07 billion.

Here’s What It Takes for Bloom to Reach $450
Today Bloom trades at 55x 2027 earnings. At $450, that multiple rises to 91x. Using the high 2027 estimate of $7.01, it falls to 64x. It’s a premium valuation, but it comes with earnings growth above 80%.
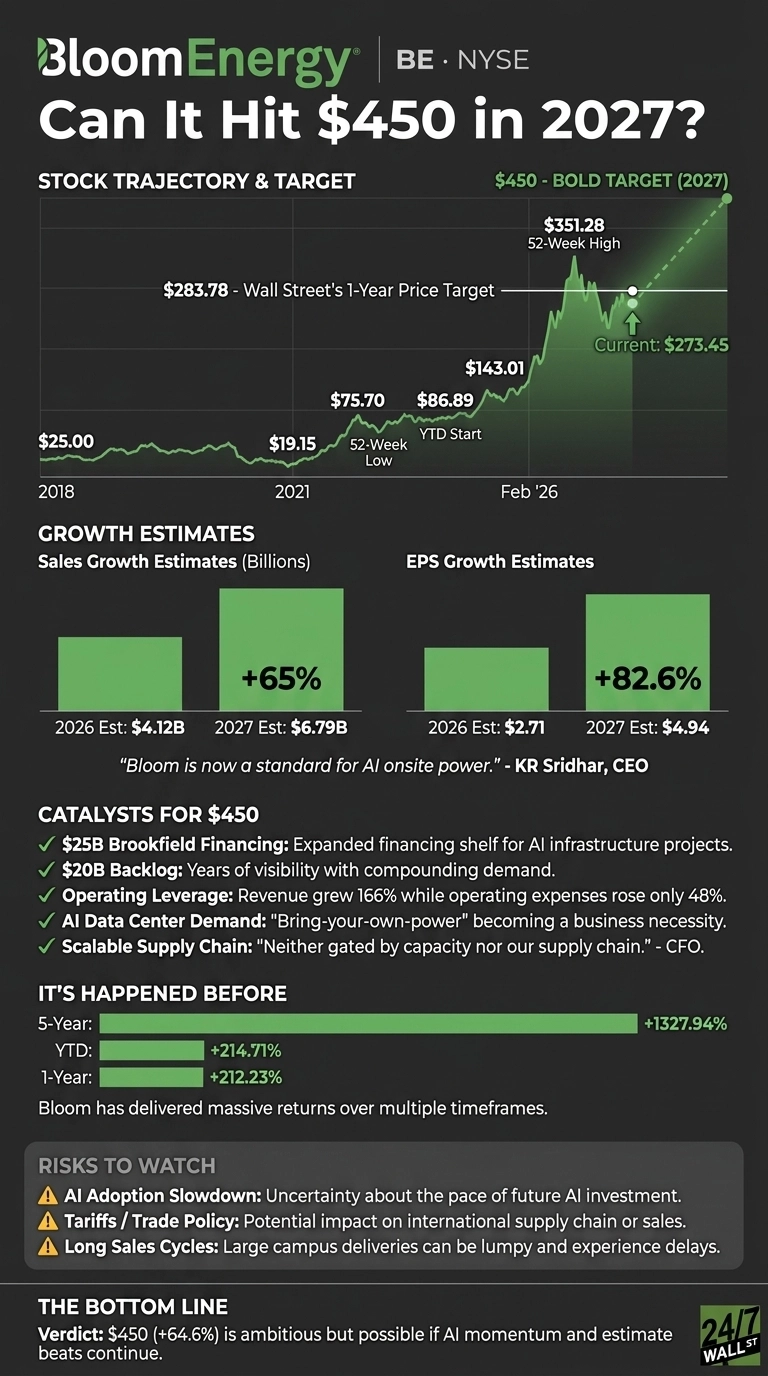
- Guidance raises: The 2026 non-GAAP operating income outlook now stands at $800 to $900 million, up from $425 to $450 million at the start of the year.
- Financing capacity: Brookfield expanded its framework from $5 billion to $25 billion in June 2026.
- Backlog: Total backlog of roughly $20 billion gives Bloom years of visibility.
- Operating leverage: Revenue grew 166% while operating expenses rose 48%, which raised operating margin to 22.5%.
- Scalable supply: CFO Simon Edwards said Bloom is “neither gated by capacity nor our supply chain.”
- Inference demand: Sridhar expects inference to need distributed power close to users, saying “You cannot put a gas turbine in the middle of Manhattan.”
Bloom’s Recent Run Shows $450 Is Within Reach
Reaching $450 would take a 64.6% gain. It’s a large move, and Bloom has already beaten it by a wide margin this year.
Shares are up 212.23% over the past year and have traded as high as $351.28 in the last 52 weeks. After the second-quarter earnings report, the stock rose 43.1% in a single week. With a beta of 3.776, Bloom moves fast in both directions. The 52-week low was $75.70.
$450 Is a Stretch, but Here’s Why It’s Possible
Hitting $450 would require Bloom to gain about 65% in 2027. Several things support that path: 2027 estimates keep rising, Bloom keeps beating them, management keeps raising guidance, and a $25 billion financing shelf supports more installations.
The hurdles are real. A slowdown in AI spending, uneven large-campus deliveries, and tariffs could each halt the rally. Still, if hyperscalers keep choosing onsite power and estimates move toward the high end, $450 is within reach. Returns at this level shouldn’t be expected every year, but we’ve outlined the plan for how Bloom could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.