Lumentum Vs. Coherent: Backlog Quality Leaves Investors Spoiled for Choice
Lumentum and Coherent both reported blockbuster quarters fueled by AI datacenter demand, with order books stretching years into the future. But a closer look at their backlogs reveals a meaningful gap in quality, and one valuation that may not account…

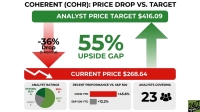
Lumentum (NASDAQ:LITE | LITE Price Prediction) and Coherent (NYSE:COHR) both reported fiscal 2026 results in August with order books that reach into 2027 and beyond. Lumentum’s quarterly revenue more than doubled to $1.006 billion. Coherent’s grew 33.74% to $2.0455 billion. Both sell into the copper-to-optical shift inside AI datacenters, so the useful question is which backlog has better terms.
Lumentum Runs Short of Lasers While Coherent Books Out 2027
Lumentum’s quarter came down to scarcity. Management said it is “way behind our shipments” on high-power lasers because demand sped up faster than the production ramp. OCS shipments doubled from fiscal Q3, and non-GAAP operating margin reached 36.6%, up 2,160 bps YoY. That kind of margin jump usually means customers are paying up for parts they can’t get anywhere else.
Coherent’s story is variety. Datacenter and Communications brought in $1.615 billion, or 79% of revenue. Management described fiscal 2027 as “basically completely booked out,” with orders reaching into calendar 2028. Industrial revenue of $430.5 million stayed roughly flat, and that drag is one the pure-play rival doesn’t has.
| Backlog Driver | Lumentum | Coherent |
|---|---|---|
| Visibility | OCS backlog above $400M (as of fiscal Q3), plus a multi-hundred-million CPO order | Orders into 2028, LTAs through end of decade |
| Contract Terms | Three-year pump laser deals, mostly take-or-pay | Volume plus locked pricing |
| Main Constraint | High-power lasers and EMLs | Indium phosphide ramp |
| Q1 FY2027 Revenue Guide | $1.225B to $1.275B | $2.2B to $2.4B |
Focused Firepower Meets Portfolio Scale
Lumentum’s demand comes from a small group of buyers: tier-one hyperscalers, a lead CPO customer, and an OCS customer that keeps an internal supply source. Lumentum CEO Michael Hurlston still expects the company to become the “number one supplier” of OCS in early 2027. He said Lumentum repriced its backlog “a little bit,” so more pricing increases could still come through.
Coherent is spending heavily. Quarterly capex rose to $556 million from $131 million a year earlier, much of it for 6-inch indium phosphide lines that deliver four times the output of a 3-inch wafer at half the cost. Its LTAs lock in pricing for the full term. That protects volume, but it could cap the upside if laser prices keep climbing.
CPO Timing Will Show Whose Backlog Holds Up Better
Coherent expects CPO revenue to start in fiscal Q2. Lumentum projects ultra-high-power laser demand ramping in the second half of calendar 2027. The focus will be on whether Coherent’s PhotonLink platform wins full-solution designs, and whether Lumentum’s Greensboro fab signs customer funding before first revenue in early 2028. Monday’s drop, with LITE down 9.78% and COHR down 7.88%, shows how quickly sentiment can turn. Both names sit firmly in the AI infrastructure trade that goes beyond the chipmakers, the same group we profiled in a free report on seven suppliers powering the data-center buildout.
Why Lumentum’s Backlog Looks Stronger, With a Valuation Caveat
To me, Lumentum’s backlog looks like the higher-quality one. Its products are scarcer, its margins are growing faster, and it forecast to a 39.5% to 40.5% operating margin. That quality comes at a price: roughly 43x forward earnings, compared with 30x for Coherent. Coherent offers more scale, U.S. manufacturing and contracted pricing. That view would change if Lumentum’s OCS customer moves more supply in-house sooner than expected.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.