Coherent Has Massively Diappointed Investors for 6 Months: A Respected Analyst Predicts It Will Double Moving Forward
Coherent keeps beating earnings estimates while its stock slides further from a 52-week high, and now Wall Street's most bullish analyst has a target that implies shares could nearly double from here.


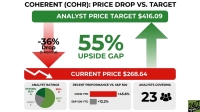
Coherent (NYSE:COHR | COHR Price Prediction) is priced at $263.23, while the average analyst price target sits at $412.52. The difference points to about 56.7% upside.
Coherent makes lasers, optical transceivers and photonic components. Its Datacenter & Communications division now brings in 79% of revenue. With funding from NVIDIA (NASDAQ:NVDA), which invested $2B, Coherent also joined the S&P 500 during fiscal 2026.
The gap matters because the business keeps speeding up while the stock goes the other way. With implied upside above 40%, Wall Street is saying the market has mispriced one of the main suppliers of AI connectivity.
Record Quarters and Falling Shares Open a Six-Month Disconnect
Most of the decline came in a single week. Coherent fell 21.32% over the past week, including a 9.22% drop in the latest session. That session came right after a hot inflation report drove the 30-year Treasury yield as high as 5.63%. AI infrastructure names fell, a cloud provider falling 16% and a server maker 11%. Rising rates hit capital-hungry suppliers hardest. Coherent spent $1.103B on capex in fiscal 2026 but generated only $79.5M in operating cash flow.
Over six months, shares are down 15.98%, and the stock trades about 40% below its 52-week high of $440. Optics stocks fell on profit taking with no company news behind it. Earlier, a fiber maker’s $2B at-the-market equity offering dragged Coherent 11% lower in sympathy.
Coherent’s own results stayed strong. Coherent has beaten EPS estimates 4 consecutive times. Its latest quarter delivered non-GAAP EPS of $1.74 versus $1.6171 expected, on revenue up 33.7%.
Rosenblatt’s $500 Target Calls for Shares to Nearly Double
Mike Genovese at Rosenblatt Securities holds the highest target on Wall Street at $500.00 with a Buy rating. That target means 89.9% upside. His thesis rests on three things: an AI transceiver super-cycle, production that is sold out well in advance, and margins that expand as manufacturing scale catches up with demand.
Management’s own comments support that view. “Fiscal 27 is basically completely booked out,” the CEO said. Customer orders reach into calendar 28, and long-term agreements run through the end of the decade. Coherent expects its first quarter above $3 billion in revenue by the end of fiscal 2027. Current-quarter guidance calls for revenue of $2.20B to $2.40B and EPS of $1.85 to $2.05.
Analysts are watching specific catalysts. Indium phosphide output is set to double this quarter, one quarter ahead of plan. Co-packaged optics revenue begins ramping in fiscal Q2. Optical circuit switching targets more than $4 billion of addressable market. Management also keeps its gross margin target above 42%.
Of 24 analysts, 4 have it at Strong Buy, 15 at Buy and 5 at Hold, with zero Sells. Bernstein recently started coverage at Outperform (247 Wall St.). Still, targets are estimates and carry no guarantee. The trailing P/E of 68x against a forward P/E of 30x shows how much of the thesis depends on earnings that have yet to arrive.
Fabrinet Carries the Optics Group’s Deepest Discount
The whole peer group sold off together. Coherent’s decline is a sector event.
Lumentum (NASDAQ:LITE) fell 19.33% over the past week but remains up 143.18% year to date. At $896.33 against a $1177.34 target, implied upside is 31.4%, which is smaller than Coherent’s. Coverage is heavily bullish, with 5 Strong Buys, 18 Buys and 4 Holds.
Fabrinet (NYSE:FN) dropped 21.09% for the week and is down 13.69% year to date. At $392.93 against a $734.11 target, it shows 86.8% implied upside. Coverage is lighter, with 3 Strong Buys, 4 Buys and 2 Holds among 9 analysts.
Fabrinet carries the largest consensus upside in the group. Coherent sits in the middle, offering a bigger discount than Lumentum with wider coverage than Fabrinet.
Coherent Still Beats the S&P 500 Despite the Slide
At $263.23, Coherent trades well below the $412.52 consensus target, leaving 56.7% implied upside across 24 covering analysts.
The six-month decline of 15.98% hides a strong year. Shares are up 42.62% year to date, while the S&P 500 has gained 12.86%. Over one year, Coherent is up 140.68%.
Coherent’s Booked Backlog Outweighs the Rate Risk
The bullish case improves if Coherent keeps converting its sold-out backlog into revenue on schedule and gross margin keeps climbing toward 42%. The outlook weakens if long-term rates keep rising, the heavy capex keeps burning cash, or hyperscaler spending cools off before co-packaged optics and optical circuit switching reach scale.
A $3 billion quarter and margin expansion would make the consensus target look conservative. On the risk side, Coherent carries about $3.2B of long-term debt and a beta of 2.113, so every move in rates gets amplified.
Contracted demand into calendar 2028 suggests this selloff reflects a rate and sentiment reset. The stock’s high beta points to continued volatility.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.