Wealth, Assets and Custody: What to Watch When Morgan Stanley, BlackRock and State Street Report
Morgan Stanley, BlackRock, and State Street all report before the open Wednesday, and Jim Cramer says they are priced for disappointment. Whether that sets up a surprise rally or confirms that rising rates control everything depends on one number above…

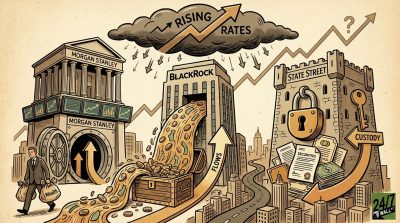
Three financial giants report ahead of the open on Wednesday, October 14. Morgan Stanley (NYSE:MS | MS Price Prediction) shows how trading and wealth management are doing. BlackRock (NYSE:BLK) reveals where investor money is flowing, and State Street (NYSE:STT) shows the economics of custody. Read together, they map the whole market.
Priced for Disappointment With Rates Rising
On October 9, Jim Cramer gave this stretch of bank earnings a thesis that can be tested: “So I think they’re priced for disappointment. You know what, if they don’t actually disappoint, we might actually catch a rally.” The same day, Cramer urged investors to start accepting “a 6%-plus long bond yield.” On October 1, he called “the impact of higher interest rates on the stock market” his big fear.
Over the past month, Morgan Stanley shares fell 8.0% and State Street retreated 7.0%, while BlackRock gained 1.7%.
All three beat estimates last quarter. Morgan Stanley posted record EPS of $3.46 against $2.89 expected. BlackRock earned $13.91 adjusted versus $12.67. State Street’s $3.65 topped $3.30, and the company raised its 2026 fee revenue growth outlook to 12% to 13%. Rates connect all three because they shape trading activity, asset values, and net interest income.
Consensus Sets the Bar
| Company | Q3 EPS Est. | YoY | Q3 Revenue Est. | YoY | FY26 EPS Est. | FY26 Revenue Est. |
|---|---|---|---|---|---|---|
| Morgan Stanley | $2.92 | 4.1% | $20.1B | 10.3% | $12.70 | $81.9B |
| BlackRock | $14.24 | 21.3% | $7.5B | 14.5% | $56.24 | $28.3B |
| State Street | $3.68 | 32.2% | $4.0B | 14.0% | $13.76 | $15.0B |
The year-on-year columns compare current consensus estimates with reported third-quarter 2024 results.
Deals, Flows, and Custody Margins Decide the Morning
Morgan Stanley: Banking and Wealth Drive the Quarter
Morgan Stanley underwrites deals, trades securities and advises wealthy clients. It releases results around 7:30 a.m. ET and holds its call at 9:30 a.m. ET. Last quarter, investment banking revenue rose 58% to $2.44 billion, and Wealth Management brought in a record $148 billion in net new assets. If deal and IPO activity picks up, it shows here first. The risk is cooler trading after equity trading revenue surged 69%. The Q3 EPS consensus has slipped to $2.92 from $3.16 over the past month.

BlackRock: Flows Set Future Revenue
BlackRock manages money for clients and charges fees on those assets, which reached a record $15.34 trillion. Q2 net inflows totaled $192 billion, and organic base fee growth hit 10% over 12 months, ahead of its 5% target. Assets gathered now set the fee base for the next several quarters, so investors will be watching flows and fee rate more than EPS. The risks include integrating acquisitions HPS and GIP while BlackRock’s own strategists are turning cautious on U.S. stocks, as Reuters reported.

State Street: First Test of New Targets
State Street holds and manages securities for big institutions. Those holdings are tracked as AUC/A (assets under custody and/or administration), which hit a record $57.9 trillion. In its second-quarter 2026 earnings release, the company said it was “entering our next phase of growth, defined by new medium-term financial targets,” including a 35% pre-tax margin. It posted 34.3% last quarter. The risk is that changing rates squeeze net interest income, which rose 18% to $860 million.
Flows Will Test the Low-Expectations Thesis
BlackRock’s net inflows are the number to watch. Money flowing into markets fuels both Morgan Stanley’s trading desks and State Street’s custody fees. Strong flows plus a firm banking pipeline would back Cramer’s rally case. If all three beat and the stocks still fall, rates control the story and the low-expectations thesis breaks.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.