Palantir’s AI Opportunity Could Be Bigger Than Investors Think
Palantir just posted revenue growth that left Wall Street estimates in the dust, yet the valuation debate raging around the stock suggests the real story is only beginning to take shape.

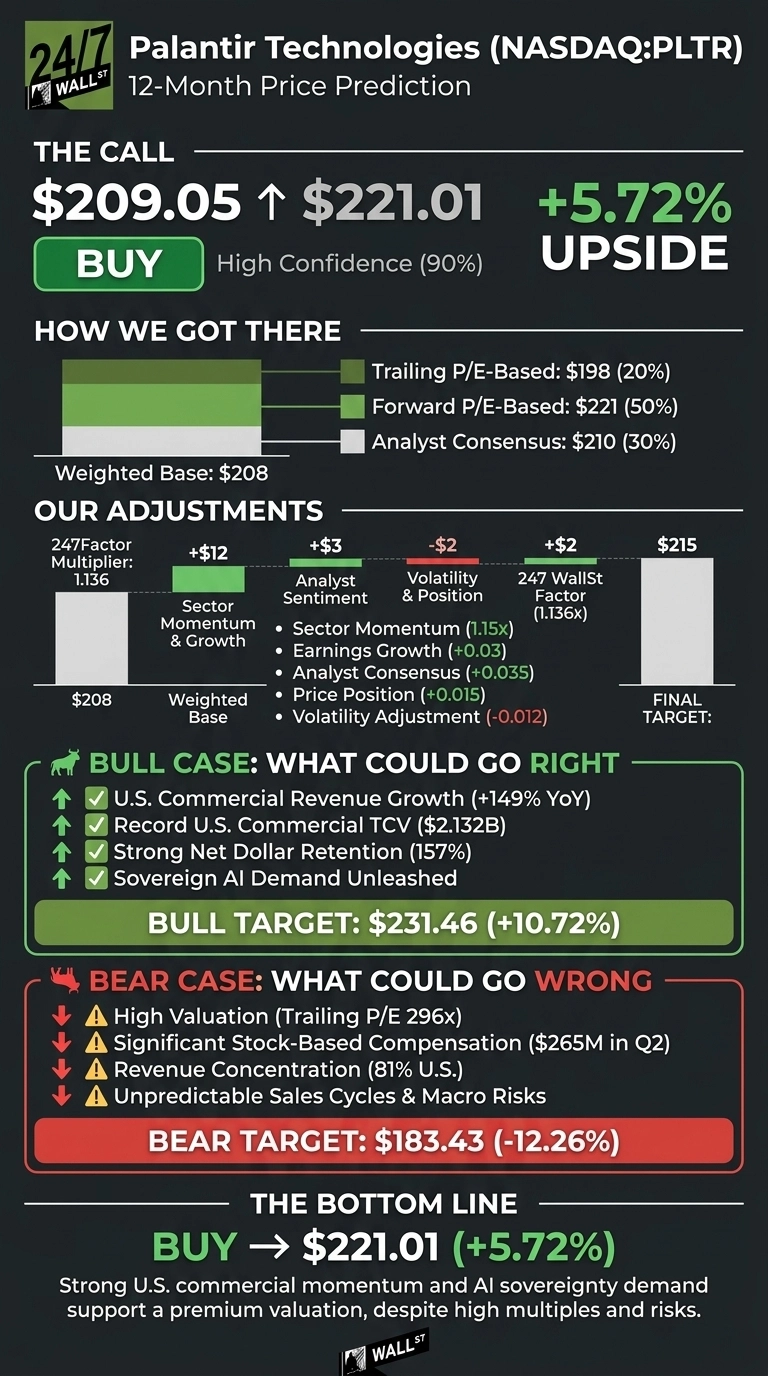
The 24/7 Wall St. price target for Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) is $221.01 over the next 12 months. That means 5.72% upside from the $209.05 close. Our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $209.05 |
| Price Target from 24/7 Wall St. | $221.01 |
| Upside/Downside | 5.72% |
| Recommendation | BUY |
| Confidence Level | 90% |
The upside looks modest because shares sit within 3% of their $209.58 52-week high. The rating remains positive because revenue growth has sped up for four straight quarters, and management keeps raising guidance. The AI sovereignty opportunity Palantir describes may still be underpriced.
Record Growth Pushes Shares Toward a 52-Week High
Palantir gained 9.43% over the past week and 21.83% over the past month, which brings the year-to-date gain to 16.2%. The stock sits far above its $106.37 52-week low. Last week, Barron’s reported that Goldman Sachs (NYSE:GS) sees Palantir holding a secret weapon in the AI boom (Barron’s).
The Q2 earnings report fueled the run. EPS of $0.41 beat the $0.28 estimate, making a 9th consecutive beat. Revenue rose 92.8% to $1.935B. U.S. commercial revenue jumped 149% to $764M, and full-year revenue guidance rose to $8.150-$8.158B, or 82% growth.

Why Bulls See $231 and Beyond
Our bull case lands at $231.46, a 10.72% return. Recent bookings make that scenario look realistic. U.S. commercial TCV rose 153% to $2.132 billion, net dollar retention reached 157%, and total remaining deal value hit $13.1 billion.
CEO Alex Karp said: “I am driving the business to grow at a rate equal to or above what we have in U.S. commercial for the next 18 months.”

Government demand adds another boost. The FY2027 Department of War request totals $1.45 trillion, including $20.5 billion for cyberspace activities. Wall Street leans positive: 19 analysts rate the stock Buy and 1 rates it Strong Buy.
Palantir is one way to play the AI expansion, though the power, cooling, and networking suppliers behind the data centers get far less attention (we covered seven of them in a free report).

Risks That Come With a 296x Trailing P/E
The bear case sits at $183.43, a 12.26% decline. The stock trades at 296 times trailing earnings and 229x free cash flow. Stock-based compensation hit $265M in Q2. Contracts can include termination-for-convenience clauses, and the U.S. generates over 81% of revenue.
On the other side, Palantir is GAAP profitable, with a 36.3% net margin. It is also guiding to $4.5-$4.7B in adjusted free cash flow this year, which gives it room to absorb dilution.

Palantir Commands a Premium Over Snowflake and Salesforce
Snowflake (NYSE:SNOW) belongs here because it competes for the same enterprise AI data budgets. Its revenue grew 35.09% last quarter, though it still runs a GAAP operating margin of -30.6%.
Salesforce (NYSE:CRM) is the value contrast in agentic AI. Agentforce ARR tops $1.5 billion, and the stock trades at 25 times earnings.
| Company | Latest Quarterly Revenue Growth | Price/Free Cash Flow |
|---|---|---|
| Palantir | 92.8% | 229x |
| Snowflake | 35.09% | 116x |
| Salesforce | 10.83% | 13x |
Palantir carries the highest multiple in this group, but it also grows the fastest. Against these peers, the 24/7 Wall St. price target looks reasonable.
Palantir Earns a Buy Rating, With a Valuation Caveat
The 24/7 Wall St. price target of $221.01 comes with a buy rating and 90% confidence. Sped up U.S. commercial demand is what tips the balance.
The bull thesis strengthens if Q3 revenue lands within the $2.160-$2.164B guidance range or above it. It weakens if U.S. commercial growth slows sharply. For now, the fundamentals support the premium.
Over a longer horizon, our model projects the following path, assuming current growth trends and market conditions hold:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $217.46 |
| 2027 | $224.15 |
| 2028 | $234.66 |
| 2029 | $241.24 |
| 2030 | $255.30 |
The model assumes Palantir keeps executing its AIP strategy. Enterprise adoption of sovereign AI and shifts in defense spending could drove the results well above or below this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.