Palantir’s Earnings Gamble: Nine Straight Beats Set High Bar for Q3 Results
Palantir has beaten earnings estimates nine times running, and its stock has surged 24% in a single month, but that kind of momentum cuts both ways when the next report lands on November 2.

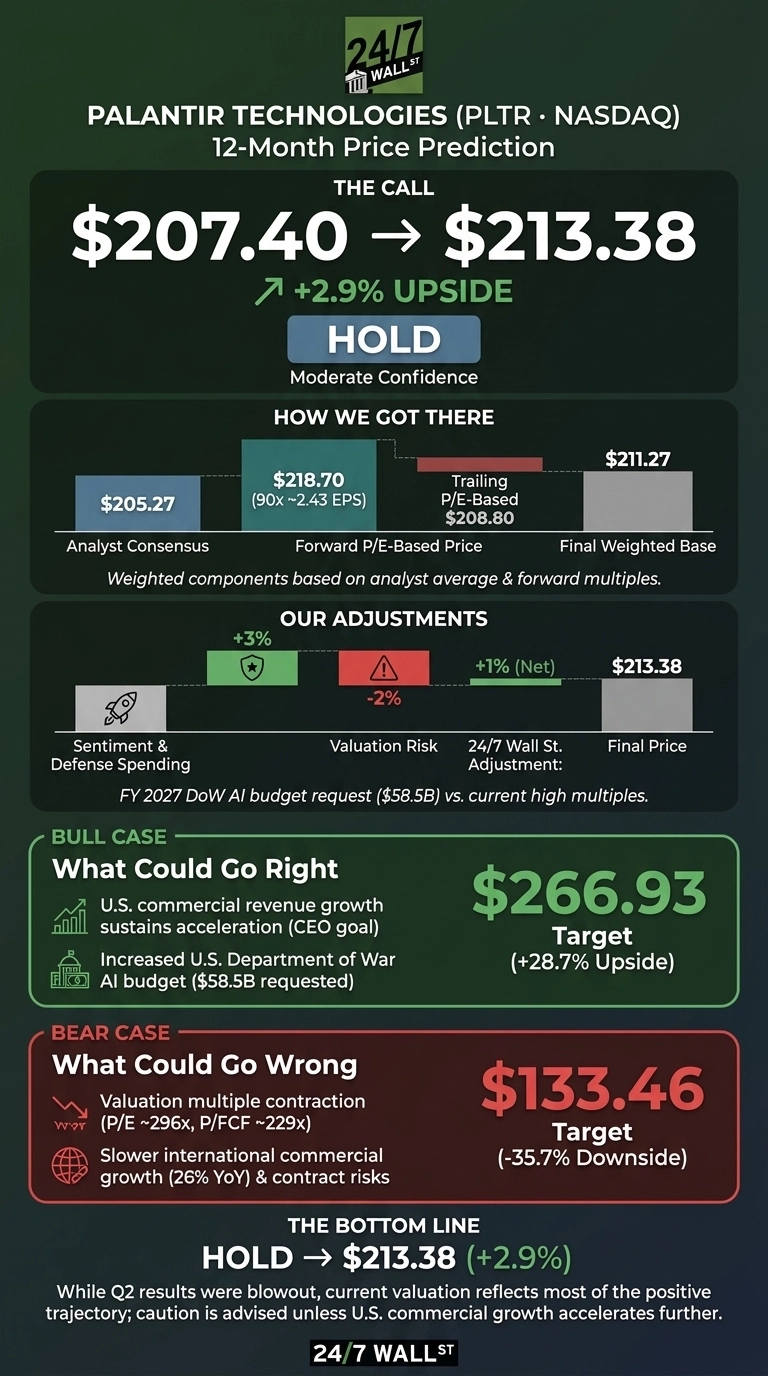
Our 24/7 Wall St. price target for Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) is $213.38. That means 2.9% upside from the current price of $207.40. We rate the stock a hold, and our confidence is moderate.
| Metric | Value |
|---|---|
| Current Price | $207.40 |
| Price Target from 24/7 Wall St. | $213.38 |
| Upside/Downside | 2.9% |
| Recommendation | HOLD |
| Confidence Level | Moderate |

Palantir is expected to report third-quarter results on November 2, 2026, a date the company has yet to confirm. Management guided Q3 revenue to $2.160 billion to $2.164 billion. The stock has climbed 24.02% over the past month, which gives little room for disappointment heading into the report.
Nine Straight Beats Pushed Palantir Back Toward Its High
Over the past week Palantir gained 9.5%. It is up 16.68% year to date. Shares now sit 2.6% below the 52-week high of $212.94 and 95% higher than the low of $106.37.
In Q2, EPS of $0.41 beat the $0.28 estimate, and revenue rose 92.83% to $1.935 billion. U.S. commercial revenue jumped 149%, net dollar retention reached 157%, and full-year guidance rose to $8.150 billion to $8.158 billion. The stock gained 29.45% on earnings day. In Q1, though, it fell 6.93% despite an 18.07% beat.

Why Bulls See $267 Ahead
CEO Alex Karp said on the Q2 call that he is “driving the business to grow at a rate equal or above to what we have in U.S. commercial for the next 18 months.” The backlog backs that goal.
Remaining deal value hit $13.1 billion, and Department of War revenue is still “less than 25 basis points of the Pentagon’s budget.” Among analysts, 19 rate Palantir a Buy and 1 a Strong Buy. If the stock trades at 110x forward EPS, our bull case points to $266.93, or 28.7% upside.

Valuation Risk Could Send Shares to $133
Palantir trades at 81.59 times sales and 228.91 times free cash flow. Stock-based compensation reached $265 million in Q2. International commercial revenue grew just 26%, and government contracts can be ended for convenience. At 55x forward EPS, our bear case falls to $133.46, a 35.7% decline.
One counterpoint on dilution: GAAP net income of $1.062 billion and a 63% free cash flow margin show that share-based pay sits on top of real profits.
Is Palantir Pricier Than Snowflake and Microsoft?
Snowflake (NYSE:SNOW) competes for the same enterprise data budgets. At 169x forward earnings, it is growing revenue 35.1% with negative margins. On a forward basis, Palantir actually costs less.
Microsoft (NASDAQ:MSFT) is the large-cap benchmark for AI infrastructure software. At 25x, it has a similar operating margin. Taken together, the two peers make our target look reasonable.
| Company | Forward P/E | Revenue Growth (YoY) | Operating Margin |
|---|---|---|---|
| Palantir | 85x | 92.8% | 47.1% |
| Snowflake | 169x | 35.1% | -17% |
| Microsoft | 25x | 17.7% | 45.1% |
Hold for Now Ahead of November 2
A hold with moderate confidence is supported by our 24/7 Wall St. price target of $213.38. Valuation tips the scale: Palantir’s performance is great, but the current price already reflects most of it.
I would turn more constructive if Q3 beats the top end of guidance and U.S. commercial growth speeds up again. I would stay cautious if growth slows and the stock’s premium multiple shrinks.

Palantir Price Prediction 2026-2030
Annual gains of 18%, 16%, 14%, and 12% support these projections, reflecting slower growth and a shrinking multiple over time.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $213.38 |
| 2027 | $251.79 |
| 2028 | $292.07 |
| 2029 | $332.96 |
| 2030 | $372.92 |
These figures assume Palantir keeps its current strategy. Defense AI budgets or a decline in enterprise AI spending could move the stock well above or below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.