I’m Simply Not Worried About Broadcom’s Multi-Segment Drag
Broadcom just delivered its best quarter ever, yet the stock sits nearly flat on the year as critics hammer its slower segments. Here is why one investor sees the same drag as his reason to keep buying.

I have added to my Broadcom (NASDAQ:AVGO | AVGO Price Prediction) position again and again this year, and last week’s slide gave me one more reason to buy. Shares fell 8.04% in a week to $346.25 as chip stocks wobbled. That leaves the stock up just 0.59% year to date, even though the business just reported the best quarter in its history.
Here is what draws me back. Broadcom co-designs the custom chips that the biggest AI developers build their data centers around. It pairs that with a software franchise that throws off cash. Critics call the slower segments a drag. I see them as ballast (we featured seven companies driving this same expansion, from power to cooling to networking, in a free report you can grab here).
Software Growth Looks Slow Only When You Stand It Next to AI
In fiscal Q3, Semiconductor Solutions revenue rose 127% while Infrastructure Software grew 29%. Non-AI chip revenue grew just 5% to $4.2 billion. That gap is the whole drag argument. Now look at what the software side makes: a 94% gross margin and an operating margin near 84%, up 650 basis points from a year earlier. Annual recurring revenue (ARR) grew 15%. A segment with those margins helps pay my dividend while the AI business scales.
Three Receipts Behind My Conviction
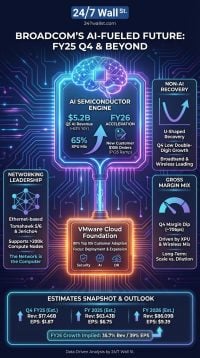
First, the AI engine is still speeding up. AI semiconductor revenue reached $16.70B, up 221%, and management guided Q4 to $21.70B, up 236%. It outlined roughly $115 billion of AI revenue in fiscal 2027 and $230 billion in fiscal 2028, and said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”
The business also turns that growth into cash. Free cash flow came to $13.665B, or 46% of revenue, and the quarter ended with $24 billion in cash.
Third, I get paid while I wait. The $0.65 quarterly dividend comes after Broadcom’s 15th consecutive annual increase. Q3 EPS of $3.32 also beat the $3.2382 estimate, the company’s 9th consecutive EPS beat.
Why My Money Skips NVIDIA and AMD
NVIDIA (NASDAQ:NVDA) is the name most people reach for first. It trades at roughly 45 times earnings and 55 times free cash flow. It carries guarantee obligations of up to $108.5 billion plus $279 billion in supply obligations. Advanced Micro Devices (NASDAQ:AMD) trades near 215 times earnings and reports no dividend. Its Q2 free cash flow fell 9.89% to $1.558 billion. Broadcom’s rose 94.55%. Its CEO also says that custom chips run advanced workloads “at half the cost of a GPU.”
Concentration Risk I Track Every Quarter
Here is what could hurt me. Broadcom has six XPU customers. Gross fixed-rate debt totals $59.6 billion. On the call, an analyst put the maximum exposure from the first tranche of its AI financing platform at about $29 billion, and management gave no updated figure. Gross margin is also heading to 73%, down from 78% a year ago.
None of that has broken my thesis. The debt carries a 4% average coupon with 7.4 years to due date, and Broadcom repaid $5.6 billion during the quarter, then another $1.5 billion after it ended. Management still guides operating margin to roughly 66% of revenue. On the outlook, the CEO said “we try to be conservative.”
What Keeps My Buy Button Active Through Fiscal 2028
Next, I am looking at the December 9, 2026 earnings report. I want to see Q4 AI revenue land near guidance and software hold close to $8.7 billion. If both happen, the so-called drag is really a cash buffer under one of the fastest-growing profit engines I own, and I will keep buying.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.