Broadcom’s Quiet 8% November Move Could Ramp Up Very Quickly in This Volatile Climate and I’m Buying

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I keep buying Broadcom (NASDAQ:AVGO | AVGO Price Prediction), and the past two weeks gave me one more reason to add. The stock rose 7.69% from November 2 through November 13 and closed at $347.01. Over the same stretch the VIX swung from 28.18[1] on November 5 to 18.70 on November 12. Swings like that scare people out of quality names. I use them to add more shares.
Custom Silicon Is the Shift I Refuse to Miss
My thesis is simple: the largest AI builders want chips designed around their own models, and Broadcom builds those chips. Google parent Alphabet (NASDAQ:GOOGL), Anthropic, OpenAI and Meta Platforms (NASDAQ:META) all work with Broadcom on custom accelerators. CEO Hock Tan made the case directly on the September call: “when you co-develop a chip that is optimized for your particular large language model workloads, you will outperform any GPU.”[2]
Three Reasons I Keep Adding Before the Next Leg
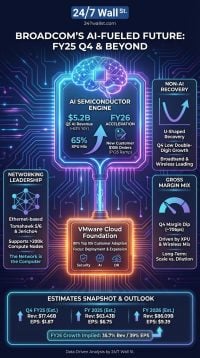
First, growth. Fiscal third-quarter revenue reached $29.591 billion[3], up 85.5% year over year. AI semiconductor revenue came in at $16.7 billion[3], up 221%. Management guided fourth-quarter AI revenue to $21.7 billion[3] and sees AI revenue of roughly $115 billion[2] in fiscal 2027 and $230 billion in fiscal 2028.
Second, cash. Free cash flow hit $13.665 billion[3], or 46% of revenue, on capex of just $532 million. That cash funds a $0.65[3] quarterly dividend, which got its 15th consecutive annual increase[4] in December 2025. It also paid down $5.6 billion[2] of long-term debt last quarter. For a retirement portfolio, I rarely find hypergrowth and a rising payout in the same stock.
Third, valuation and consistency. Broadcom trades near 19 times forward earnings and has beaten EPS estimates for 9 consecutive quarters. Management says it is on target to exceed $30 in earnings per share in fiscal 2028[2].
Why My Money Skips NVIDIA and AMD
NVIDIA (NASDAQ:NVDA) is the obvious alternative, and its growth is real. Its outlook carries more uncertainty than I want, though. It excludes China data center compute revenue entirely, supply obligations climbed to $279 billion, and days sales outstanding stretched to 60 days from 45 days on extended payment terms.
Advanced Micro Devices (NASDAQ:AMD) trades at roughly 202 times earnings, and its third-quarter free cash flow fell 70.86% to $554 million. I want cash compounding in my hands, so I pass.
Risk That Could Hurt This Position
Concentration worries me most. Broadcom depends on a small group of hyperscale customers, and Hock Tan raised the timing question himself: “even as we ship the chips, will they be deployed on a timely basis?”[2] Land, power and memory shortages could all push revenue out. Gross margin is guided to about 73%[2] versus 78% a year ago as memory content rises, and the company carries $59.6 billion of fixed-rate debt.
My thesis still holds because guided operating margin sits near 66%[2], the debt carries a 4% weighted coupon, and management says it has secured supply for its fiscal 2028 outlook. Google signed a long-term TPU agreement, and Broadcom expects Anthropic to become its largest XPU customer in 2027[2].
What Keeps My Buy Button Active Into December
Broadcom reports fourth-quarter results on December 9, 2026[2], and I will keep an eye on the stock. Over five years shares gained 573.06%, yet the stock is up only 0.81% year to date while AI revenue more than tripled. Spending on AI keeps moving toward custom silicon, and I plan to keep adding shares of the company that designs it.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.