Seagate Could Have a Long Runway as Data Storage Demand Explodes
Seagate just shed more than 14% in a month after a rival made a move that rattled the entire hard-drive sector, yet the company's own numbers tell a completely different story about where demand is heading.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
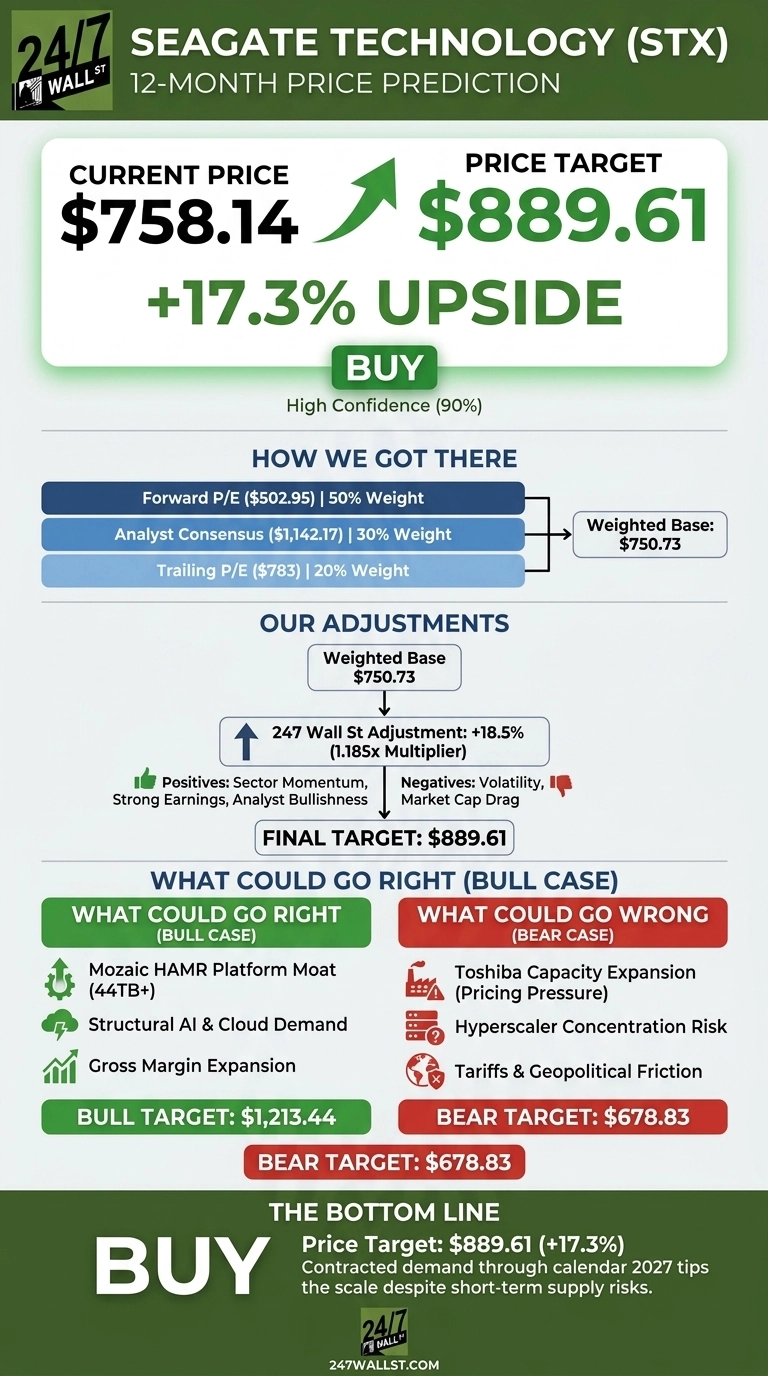
Seagate Technology (NASDAQ:STX | STX Price Prediction) has pulled back hard in October, widening the gap to our model’s target. The 24/7 Wall St. price target for Seagate is $889.61 over the next 12 months. That means 17.3% upside from the current $758.14. Our model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $758.14 |
| Price Target from 24/7 Wall St. | $889.61 |
| Upside | 17.3% |
| Recommendation | BUY |
| Confidence Level | 90% |

Mass-capacity hard drives have become core AI infrastructure. Seagate’s nearline capacity is “almost fully allocated through calendar 2027,” and fiscal Q1 2027 guidance calls for revenue of $4.1 billion and non-GAAP EPS of $7.30. I believe the fundamentals can absorb the competitive threat that caused last week’s selloff.

Toshiba Headlines Knock Seagate Off Its Highs
Seagate shares fell 10.7% over the past week and 14.35% over the month, including a 3.17% drop this morning. The trigger was a report that Toshiba plans to expand hard-drive capacity, which hit rival Western Digital (NASDAQ:WDC) too and pulled down both Seagate and Western Digital. The stock is still up 176.22% year to date. Its 52-week range is $207.78 to $1,143.27.
The business keeps accelerating. Fiscal Q4 2026 non-GAAP EPS of $5.71 exceeded the $5.0932 consensus, Seagate’s fourth straight beat. Revenue of $3.629 billion rose 48.49% year over year, and full-year free cash flow reached a record $3.105 billion.
Why Bulls See $1,213.44 Within Reach
Mozaic, Seagate’s HAMR drive platform, is the moat. Mozaic 4 delivers up to 44 terabytes per drive with minimal bill-of-materials change, and Mozaic 5 targets 50 terabytes. Packing more data onto each drive raises margins: non-GAAP gross margin reached 52.7% from 37.9%.
Management now targets revenue growth of “a minimum of 20% over the next few years.” Analysts agree, with 4 of them rating it a Buy or higher and 18 at Buy (firm-level targets were unavailable). Our bull case reaches $1,213.44.

What Could Derail the Storage Upcycle
Toshiba’s expansion threatens the tight supply behind Seagate’s pricing power. Dependence on a few hyperscale customers means visibility can fade quickly if they slow spending (we covered seven companies driving that same data-center buildout, from power to cooling to storage, in a free AI infrastructure report).
Tariffs, the Middle East conflict, BIS settlement payments and dilution from Exchangeable Senior Notes due 2028 add friction. The bear case is $678.83. Margin gains stem from areal density economics and product mix, and Seagate retired $1.40 billion of debt in fiscal 2026.
How Seagate Compares to Western Digital and Micron
Western Digital is the direct comp, now a pure-play HDD company. It posted 54.4% non-GAAP gross margin on 43.84% revenue growth. These comparable economics support the 24/7 Wall St. price target.
Micron Technology (NASDAQ:MU) represents the memory and flash side of AI storage. Its revenue grew 379.27% at an 87% non-GAAP gross margin. Memory runs faster but swings harder. Seagate’s build-to-order contracts offer firmer visibility, making our target look reasonable.
| Company | Latest Non-GAAP Gross Margin | Latest Quarter Revenue Growth | Market Cap |
|---|---|---|---|
| Seagate | 52.7% | 48.49% | $172.4B |
| Western Digital | 54.4% | 43.84% | $145.1B |
| Micron | 87.0% | 379.27% | $1.11T |
Seagate Price Prediction 2026-2030
The 24/7 Wall St. price target of $889.61 carries a buy rating at 90% confidence. Contracted demand through calendar 2027 tips the scale. The outlook improves if Mozaic 4 ramps on schedule and pricing holds. It weakens if Toshiba’s added supply erodes pricing. On balance, the selloff appears larger than the fundamental risk.
This is where our model projects Seagate could trade, assuming current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $829.27 |
| 2027 | $891.86 |
| 2028 | $976.18 |
| 2029 | $1,055.37 |
| 2030 | $1,101.73 |
Seagate’s continued execution on its HAMR roadmap supports these projections. A faster AI storage buildout or a supply glut could move results sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.