Waste Management vs. Republic Services: Which Hauler Pays Income Investors Better
Both trash giants raised dividends in 2026 and beat cost inflation with pricing power, but the income math between them tells a very different story for retirees who need checks they can live on without ever selling a share.


Waste Management (NYSE:WM | WM Price Prediction) and Republic Services (NYSE:RSG) both raised their dividends in 2026. Both also posted second-quarter results where pricing ran ahead of cost inflation. For a retirement portfolio, the two businesses look almost identical. The income math is where they split.


Price Hikes Carry Both Haulers as Volumes Slip
Trash pickup is a bill people pay no matter what the economy does. Many contracts run for years and include built-in price escalators. Landfill ownership and dense routes add a barrier that a new competitor cannot copy quickly.
WM posted core price of 5.7% while collection and disposal volume fell 1.8%. Part of that drop comes from the prior year’s wildfire cleanup, which inflated the comparison. Free cash flow rose 34.5% to $1.10B, which tells me the Stericycle integration is starting to pay. Healthcare Solutions margin expanded to 19%.
Republic’s adjusted EPS of $1.85 missed the $1.94 estimate, mostly because of a $58M equity-method loss. CEO Jon Vander Ark raised guidance anyway, pointing to “pricing in excess of cost inflation and our disciplined cost management.” I would treat the miss as noise. The bigger concern is Environmental Solutions margin, which fell from 24.4% to 20.2%.
| Income Metric | WM | RSG |
|---|---|---|
| Forward Annual Dividend | $3.78 | $2.68 |
| Forward Yield | 1.75% | 1.19% |
| Latest Dividend Hike | 14.5% | ~7% |
| 2026 Free Cash Flow Guide | $3.75B to $3.85B | $2.540B to $2.575B |
| Net Leverage | 2.96x | ~2.6x |
| Forward P/E | 23 | 26 |


Landfills Versus Deal Flow Splits the Playbooks
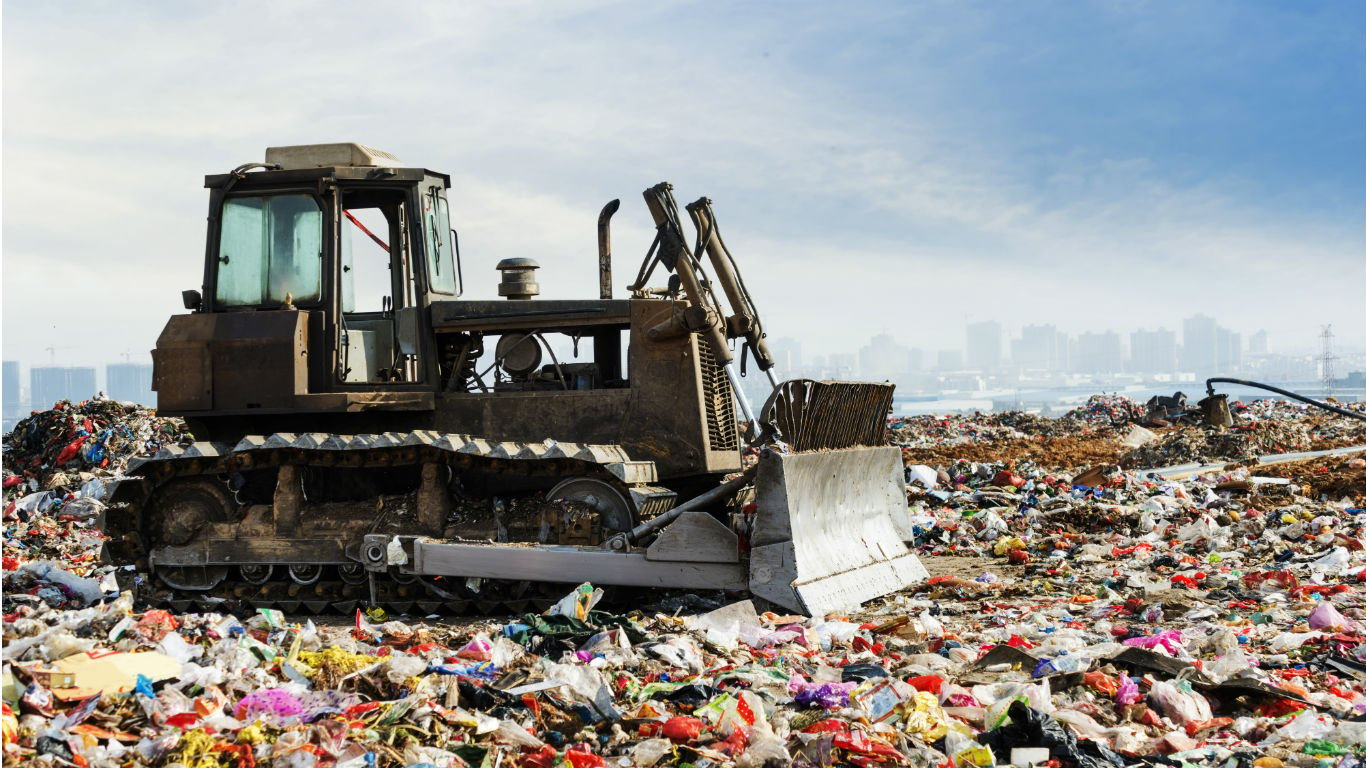
WM generated $1.004B of landfill revenue in the quarter, compared with $517M at Republic. That bigger disposal network is WM’s real advantage. It also bought Florida landfill property and ships volume by rail to a site with more than 100 years of life.
Republic grows mainly through acquisitions. It spent $860M in the first half and expects to invest more than $1.2 billion this year. Every dollar spent on deals is a dollar that cannot go to buybacks.
Recycling prices fell at both companies, to $75/ton at WM and $136 at Republic. On renewable natural gas, WM has already locked in about 90% of its 2026 volume. Republic brought two projects online this year and has two more due by year-end.
Healthcare Synergies Decide What Comes Next
My focus is whether WM delivers more than $300 million of synergies by the end of 2027. I also want to see residential volume flatten out. At Republic, you should keep an eye on Environmental Solutions margins and how smoothly the new acquisitions fold in.
Why Waste Management Leads on Retirement Income Metrics
WM wins for income. It pays the higher yield, delivered the bigger dividend increase and trades at the lower forward multiple. Its plan to return about $3.5B this year includes roughly $1.5B in dividends, which its free cash flow guidance covers easily. The quarterly payout has stepped higher every year since at least 2009, the kind of record that lets a retiree live off the checks without ever selling a share (we laid out how to build that kind of dividend ladder in a free guide here).
Republic fits total-return investors who want lower leverage, a 23rd consecutive dividend increase and growth through acquisitions. Its stock is up 7.16% year to date, compared with -0.64% for WM. I would change my view if the healthcare business starts to slip.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.