Palantir Is Expanding Beyond Government Contracts. Here’s Why Investors Should Care
Palantir just posted its fastest commercial growth ever, but the valuation math raises a question that every investor needs to answer before buying in at current prices.

Palantir (NASDAQ:PLTR | PLTR Price Prediction) now gets its fastest growth from American corporations. U.S. commercial revenue rose 149% year over year last quarter.
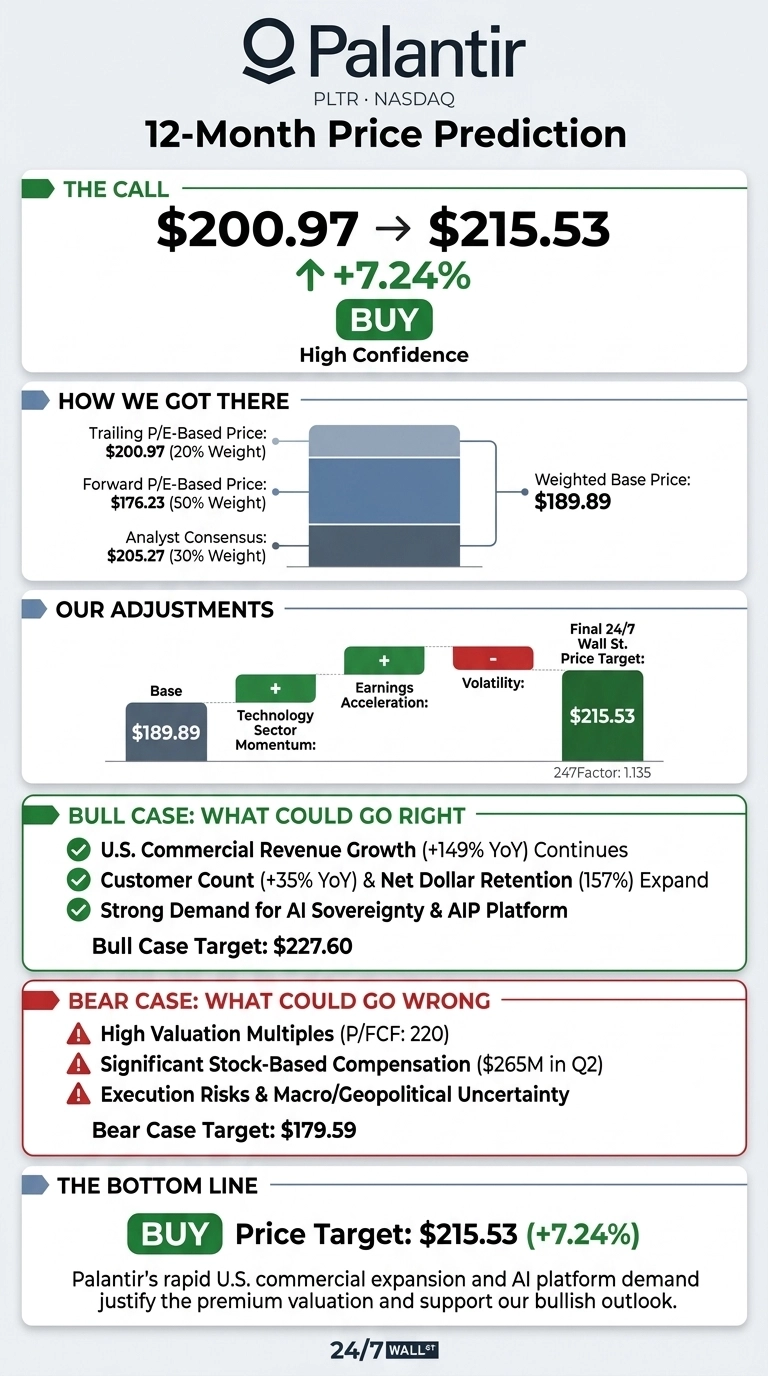
Our 24/7 Wall St. price target for Palantir is $215.53, which means 7.24% upside from $200.97. Our model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $200.97 |
| 24/7 Wall St. Price Target | $215.53 |
| Upside/Downside | 7.24% |
| Recommendation | BUY |
| Confidence Level | 90% |

Our target sits above the analyst consensus of $205.27 and slightly above the 52-week high of $212.94. Upside looks modest because shares have already re-rated on record results.
The revenue mix carries more weight. Palantir is becoming from a defense software vendor into an enterprise AI platform, which broadens its market and reduces its reliance on government budgets.
A Record Quarter Fueled a 50% Rally Since July
From July 15 through October 14, shares gained 50.25%. They are up 14.36% over the past month, 2.1% over the past week and 11.5% year to date. The 52-week low was $106.37.
The rally followed the second-quarter report on August 3. Revenue rose 92.8% to $1.935 billion, and EPS of $0.41 beat the $0.28 estimate.
U.S. commercial revenue came in at $764 million and U.S. government revenue at $809 million, up 90%. Management raised full-year revenue guidance to $8.150 billion to $8.158 billion, which works out to 82% growth.
Commercial Momentum Could Push Shares Toward $227.60
The bull case starts with bookings. U.S. commercial total contract value reached $2.132 billion, up 153%, and U.S. commercial customers grew 35% to 653. Net dollar retention hit 157%, meaning existing customers are spending far more each year.
One multinational technology customer expanded to a three-year, nearly $370 million deal. CEO Alex Karp said, “I am driving the business to grow at a rate equal to or above what we have in U.S. commercial for the next 18 months.” Analyst ratings lean bullish (19 Buy and 1 Strong Buy). Our bull case reaches $227.60.

Valuation Leaves Little Room for a Stumble
Free cash flow multiples sit at 220 for Palantir, and stock-based compensation was $265 million last quarter. Government contracts can be terminated for convenience, and management expects Q3 expenses to rise significantly.
The bear case sits at $179.59. GAAP net income reached $1.062 billion, and Palantir has $9.2 billion in cash and Treasuries. Profits are real and growing quickly.

Palantir Trades Between Snowflake and Salesforce
Snowflake (NYSE:SNOW) competes for the same enterprise data and AI budgets. Revenue grew 35.09% last quarter, and the company still posts GAAP operating losses.
Salesforce (NYSE:CRM) is the value end of commercial AI. Agentforce ARR topped $1.5 billion, yet total revenue grew just 10.83%.
| Company | Forward P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Palantir | 85x | 92.8% |
| Snowflake | 169x | 35.09% |
| Salesforce | 14x | 10.83% |
Palantir grows far faster than Snowflake at half the forward multiple. Our target looks reasonable as a result.
Palantir Price Prediction 2026-2030
Our 24/7 Wall St. price target of $215.53 carries a buy rating and 90% confidence. What tips the scale for me is commercial diversification.
The bull case strengthens if U.S. commercial growth keeps pace with Karp’s 18-month goal. The bear case gains weight if bookings slow while compensation costs rise. For now, the growth justifies the premium.
This is where our model projects Palantir could trade if current trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $215.53 |
| 2027 | $227.88 |
| 2028 | $240.95 |
| 2029 | $254.76 |
| 2030 | $269.36 |
The projections rest on Palantir continuing to execute its commercial expansion. A faster rollout of sovereign AI could drive results higher, while multiple compression could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.