Prediction: Oracle’s Next Chapter Could Be Huge for Shareholders
Oracle's cloud revenue is exploding while its stock sits near yearly lows, and the gap between those two realities may represent one of the more unusual setups in large-cap tech right now.


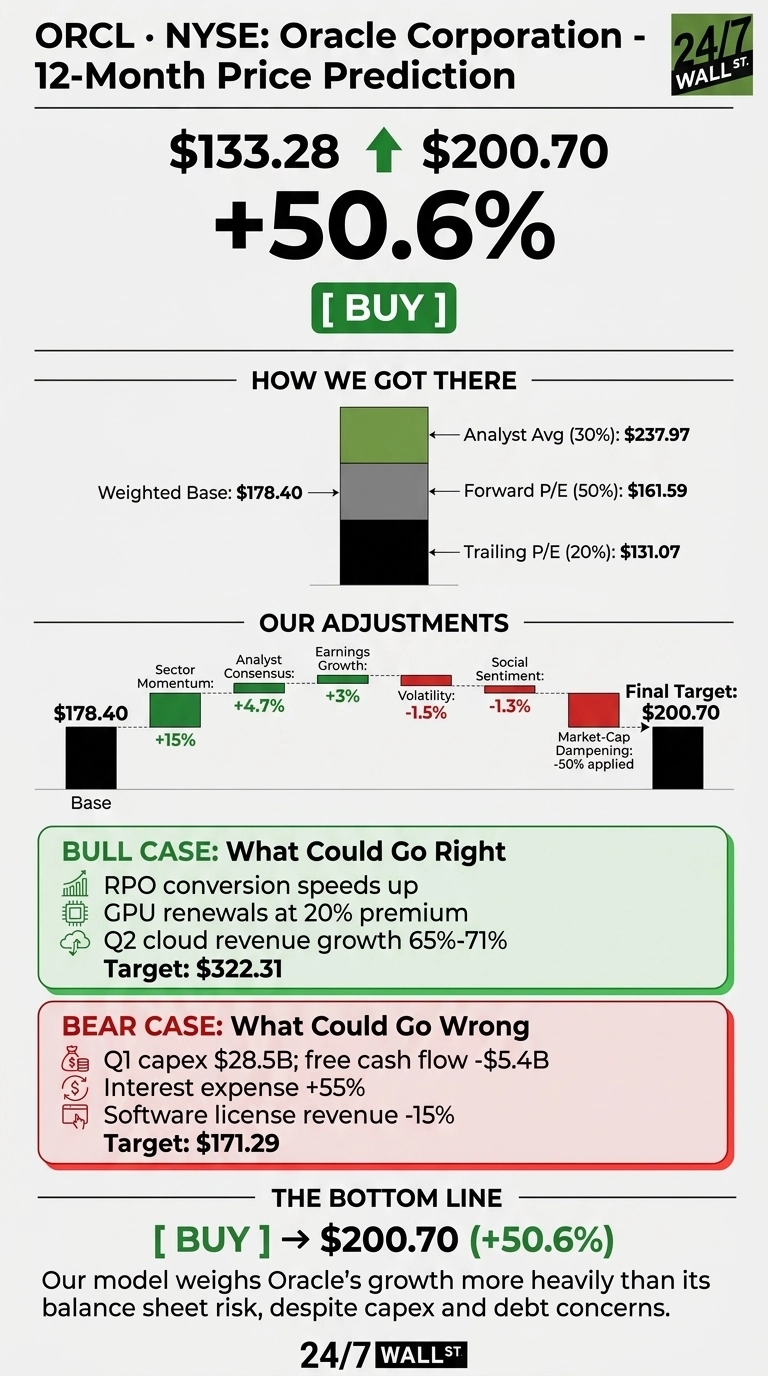
The 24/7 Wall St. price target for Oracle (NYSE:ORCL | ORCL Price Prediction) is $200.70 over the next 12 months. With shares at $133.28 in midday trading, that implies about 50.6% upside. Our model rates Oracle a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $133.28 |
| Price Target from 24/7 Wall St. | $200.70 |
| Upside/Downside | 50.6% |
| Recommendation | BUY |
| Confidence Level | 90% |

Oracle’s fundamentals and its share price have diverged. Cloud infrastructure revenue more than doubled last quarter, while the stock has fallen year to date on fears about debt and capital spending.
Our model looks through the financing noise and focuses on earnings power, and that earnings power points sharply higher.
Record Cloud Growth Meets a 30% Share Slide
Oracle is down 6.83% over the past week, 7.62% over the past month and 30.71% year to date. It sits well below its 52-week high of $318.28 and closer to its low of $114.08. Weak AI sentiment hit CoreWeave (NASDAQ:CRWV): CoreWeave shares tumbled this week as bond yields climbed on concern about AI borrowing.
Operating results stayed strong. Q1 fiscal 2027 revenue reached $19.345 billion, up 29.6% and ahead of the $19.129 billion consensus. Non-GAAP EPS of $1.92 beat the $1.74 estimate. Cloud infrastructure revenue jumped 121%, and remaining performance obligations (RPO, or signed future revenue) hit $664 billion.
Why Bulls See $322 Within Reach
Management guided Q2 cloud revenue growth of 65% to 71% and raised fiscal 2027 targets to at least $90 billion in revenue and $8.10 in non-GAAP EPS. Oracle expects “around half of our RPO to convert into sales over the next 36 months.”
GPU use ran at 97.9%, and renewals were priced at a 20% premium. Of the 43 analysts covering the stock, 7 rate it Strong Buy and 28 rate it Buy. If RPO conversion speeds up, our bull scenario reaches $322.31.

Debt and Capex Are What Could Derail the Rally
Q1 capex hit $28.5 billion, drove free cash flow to -$5.40 billion. Full-year capex is guided at $90 billion to $95 billion. Interest expense rose 55% to $1.4 billion, and Oracle plans to raise about $40 billion in debt and equity this fiscal year. Software license revenue also fell 15%.
Cash generation offsets some of that pressure. Operating cash flow soared 184% to $23.10 billion, and the CFO said scaled projects deliver “a free cash flow conversion ratio of something like 100% to post-tax EBITDA.” Even our bear scenario lands at $171.29.
The expansion behind that capex has to be powered, cooled, and networked by someone, and we rounded up seven suppliers riding the same wave in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
Oracle Trades at a Discount to Microsoft and Amazon
Through Azure, Microsoft (NASDAQ:MSFT) competes directly, and it also hosts Oracle’s multicloud database. It trades at 25x forward earnings while growing revenue 17.7%.
Amazon (NASDAQ:AMZN) competes through AWS for the same AI training workloads, at 24x forward earnings with 19.6% revenue growth. Oracle is growing faster than both at a lower multiple. That gap makes our 24/7 Wall St. price target look conservative.

| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Oracle | 18 | 29.6% |
| Microsoft | 25 | 17.7% |
| Amazon | 24 | 19.6% |
Our Verdict: Growth Outweighs the Balance Sheet Risk
The 24/7 Wall St. price target of $200.70 comes with a buy rating and 90% confidence. The $664 billion backlog sits behind a stock priced below its hyperscaler peers.
The thesis gets stronger if RPO converts on schedule and capex moves toward customer-funded structures. It weakens if borrowing costs keep climbing or datacenter deliveries slip. For now, our model weighs Oracle’s growth more heavily than its balance sheet risk.
Here is where the 24/7 Wall St. price target model projects Oracle could trade further out if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $137.77 |
| 2027 | $201.06 |
| 2028 | $273.30 |
| 2029 | $326.69 |
| 2030 | $388.07 |
Oracle needs to keep executing on its AI infrastructure strategy for these projections to hold. Faster RPO conversion could raised results well past these figures, while financing pressure or AI demand fatigue could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.