Prediction: Oracle Could Become a Much Bigger AI Winner Than Investors Expect
Oracle's stock has cratered 32% this year even as its cloud business posted explosive growth and locked in hundreds of billions in future contracts. Here is why the market may be pricing this AI infrastructure giant at a historic discount.

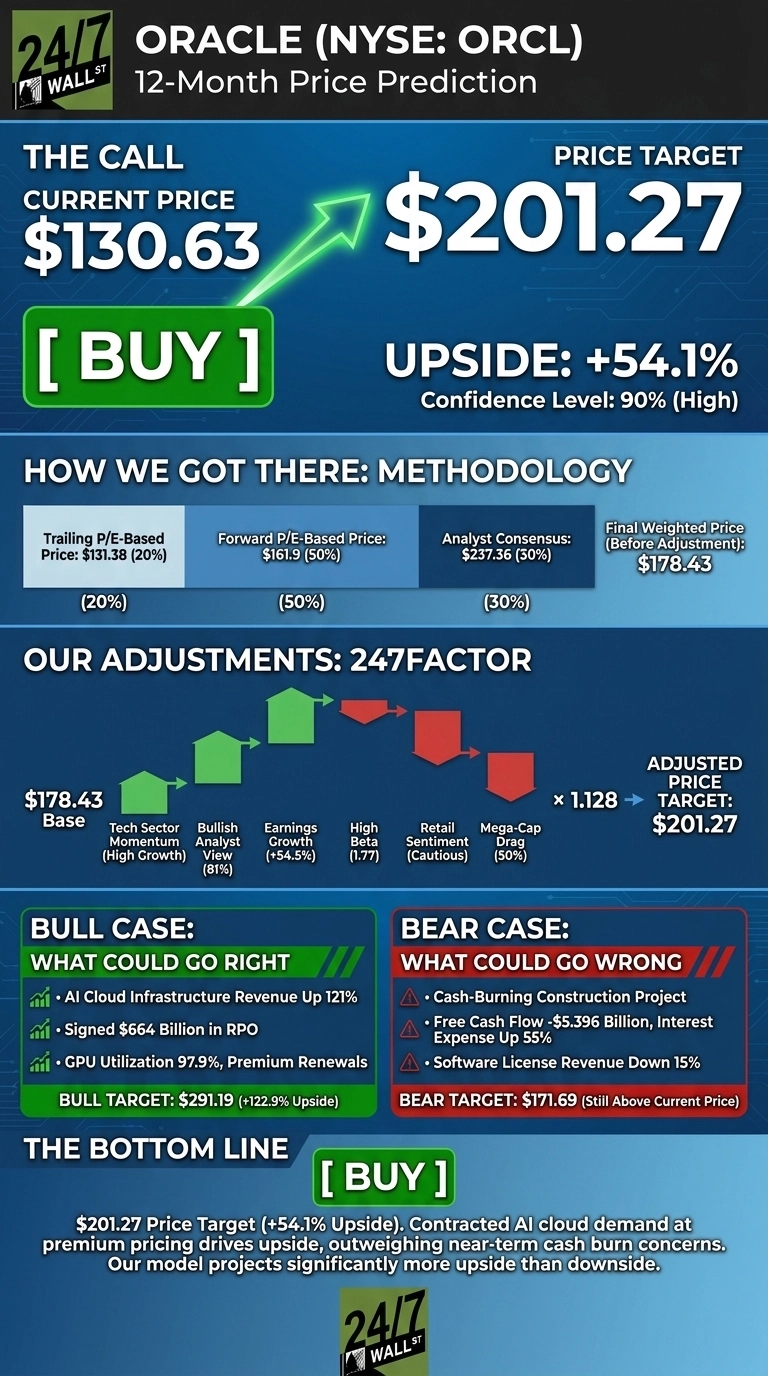
We set a 24/7 Wall St. price target for Oracle (NYSE:ORCL | ORCL Price Prediction) at $201.27 over the next 12 months. With shares at $130.63, that points to about 54.1% upside. Our model gives the stock a buy rating.
| Metric | Value |
|---|---|
| Current Price | $130.63 |
| Price Target from 24/7 Wall St. | $201.27 |
| Upside/Downside | 54.1% |
| Recommendation | BUY |
| Confidence Level | 90% |

Right now the market prices Oracle like a cash-burning construction project. I see a signed AI cloud franchise with $664 billion in remaining performance obligations (RPO) and infrastructure revenue up 121%. That gap between price and fundamentals drives our target.
Shares Down 32% in 2026 Even as Cloud Revenue Jumped 62%
Oracle has fallen 8.78% over the past week, 11.19% over the past month and 32.09% year to date. It now sits about 53.9% below its 52-week high of $283.40 and just 14.5% shy of its low of $114.08.
That selloff is hard to square with the latest results. In fiscal Q1 2027, Oracle posted non-GAAP EPS of $1.92 against a $1.7391 estimate. Revenue came in at $19.345 billion, ahead of expectations.
Cloud revenue reached $11.607 billion, and management raised full-year guidance to at least $90 billion in revenue and $8.10 in non-GAAP EPS.
Why Bulls See $291 on the Horizon
Oracle reaches $291.19 within a year in the bull scenario, about 122.9% upside. Demand data supports that case. GPU utilization was 97.9%, and capacity that came up for renewal was renewed or resold at a 20% premium.
Oracle also signed more than $30 billion in new AI contracts that management says need no extra Oracle capital. Management expects around half of RPO to convert to revenue within 36 months. Multicloud database revenue grew 353%.

Wall Street agrees. The consensus target stands at $237.36, with 7 strong buy and 28 buy ratings. For fiscal 2028, analysts expect EPS of $10.9916.

Cash Burn Is the Risk Worth Watching
The bear case lands at $171.69, which is still above today’s price. The concerns are real. Q1 capex was $28.499 billion, free cash flow was -$5.396 billion and interest expense rose 55% to $1.4 billion. Software license revenue fell 15%, and permitting in New Mexico adds execution risk.
Still, after customer prepayments, net cash capex was $18 billion, and operating cash flow hit a record. The CFO, Hilary Maxson, said new projects deliver “a free cash flow conversion ratio of something like 100% to post-tax EBITDA” once they reach full scale.
Oracle Trades at a Discount to Microsoft and Amazon
Microsoft (NASDAQ:MSFT) is the most direct AI cloud comparison, since Azure competes for the same model-training customers. The stock trades at 25x forward earnings while growing revenue 17.7%. Oracle is growing faster at a lower multiple.
Amazon (NASDAQ:AMZN) earns its place through AWS, which goes head-to-head with Oracle Cloud Infrastructure and also hosts Oracle’s multicloud databases. Amazon trades at 24x forward earnings with a PEG ratio of 1.478.
| Company | Forward P/E | PEG Ratio | Quarterly Revenue Growth |
|---|---|---|---|
| Oracle | 18x | 0.807 | 29.6% |
| Microsoft | 25x | 1.617 | 17.7% |
| Amazon | 24x | 1.478 | 19.6% |
The 24/7 Wall St. price target values Oracle at about 25x fiscal 2027 consensus EPS, which is in line with Microsoft. Given Oracle’s faster growth, that target looks reasonable, and arguably conservative.
Our Verdict: Contracted Demand Drives the Upside Case
Our 24/7 Wall St. price target of $201.27 comes with a buy rating and 90% confidence. What tips the scale is signed demand that is already turning into revenue at premium pricing.
The bull case strengthens if RPO keeps converting and Q2 cloud growth lands within the 65%-71% guidance range. The bear case gains weight if datacenter delays or rising debt costs push profitability further out. At this price, our model projects more upside than downside.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $139.24 |
| 2027 | $201.27 |
| 2028 | $269.16 |
| 2029 | $337.86 |
| 2030 | $377.47 |
Oracle needs to keep executing on its AI infrastructure expansion for these projections to hold. Faster RPO conversion could raised performance well above this path, while funding strains could pull them below it. The power, cooling, and networking suppliers behind that expansion are their own trade, and we covered seven of them in a free report on the AI boom beyond the chipmakers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.