Intel Vs. Micron: Who Is More Exposed By Chinese Rival CXMT’s Progress?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
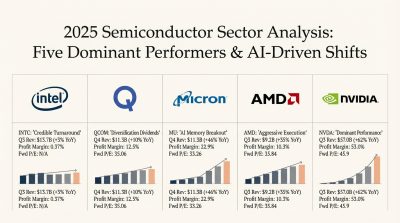
Micron Technology (NASDAQ:MU | MU Price Prediction) and Intel (NASDAQ:INTC) both posted AI-fueled quarters. Now both face the same question from China. CXMT, also known as ChangXin Memory Technologies, says it will launch a new server memory product before the end of 2026 using a denser 4F square design. Micron sells memory. Intel buys it. That one difference shapes who should worry more.
Tight Memory Supply Pays Micron and Pinches Intel’s PCs
Micron’s fiscal Q4 revenue reached $54.23B, up 379.3% YoY, with non-GAAP gross margin of 87.0%. Margins like that only happen when sellers set the price. DRAM brought in $39.8 billion, or 73% of total revenue, and DRAM prices rose in the high teens percentage range. CXMT’s added capacity takes aim at exactly that pricing.
Intel’s Q2 revenue rose 25.4% YoY to $16.13B, powered by Data Center and AI growth of 59%. For Intel, memory is a cost. Management expects PC consumption to fall “low double digits percent for all of 2026, impacted by rising memory prices and constraints.”
| Business Driver | Micron | Intel |
|---|---|---|
| Role in DRAM | Seller | Buyer |
| Main Growth Engine | HBM and data center SSDs | Xeon server CPUs |
| CXMT Overlap | Direct product competition | Indirect, through foundry and China policy |
Micron Leans on Contracts While Intel Could Gain From Cheaper Chips
Micron has signed 26 Strategic Customer Agreements covering over 35% of revenue through 2030, all with take-or-pay volumes. That protects demand, though the remaining quarter of expected SCA revenue still reprices against market rates. HBM4 is in high-volume shipments, and HBM4E on 1-gamma targets calendar 2027 production. CXMT has yet to match those leading-edge products. Still, the earnings call never mentioned CXMT by name, which leaves investors wondering about how management views the threat.
Intel’s exposure runs in the other direction. If CXMT supply grows, cheaper DRAM could lower PC and server costs and help Intel’s client business recover. China’s broader push for domestic chips could limit Intel Foundry’s Chinese customer base, but external foundry revenue was only $293 million last quarter. Intel has little at stake there today.
CXMT’s Server Chip Launch Is Next
Whether CXMT’s 4F square product reaches real server volume will be worth watching. Micron expects industry DRAM bits to grow in the low 20s percentage range in 2027 and 2028, with supply still tight. Faster Chinese output could loosen that market sooner than Micron expects. Keep an eye on Intel’s client results too. Management guided that business to “flattish” revenue while the PC market declines.
Why I See Micron Carrying Far More CXMT Risk
Over the past month, Micron shares fell 10.9% and Intel dropped 15.26%. Both slipped, so I read that as a sector-wide selloff.
The business exposure is easier to call. Every Micron dollar comes from memory, so CXMT’s progress is a direct threat to its pricing. I think HBM leadership and take-or-pay contracts give Micron a real buffer through 2027. If CXMT’s server DRAM wins qualification at major cloud customers, I would reconsider. Intel offers AI compute exposure that could benefit if memory gets cheaper.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.