IonQ Hasn’t Looked More Intriguing in a Long Time
IonQ keeps shattering revenue records while its share price sits near a 52-week low, and that contradiction raises a question worth answering before the next quarterly report forces the market to pick a side.

IonQ (NYSE:IONQ | IONQ Price Prediction) trades at $31.27, well below the level that analysts and the company’s growth rate point to. Shares have fallen 47.83% over the past year while revenue keeps setting records, and that gap is the reason to take a fresh look.
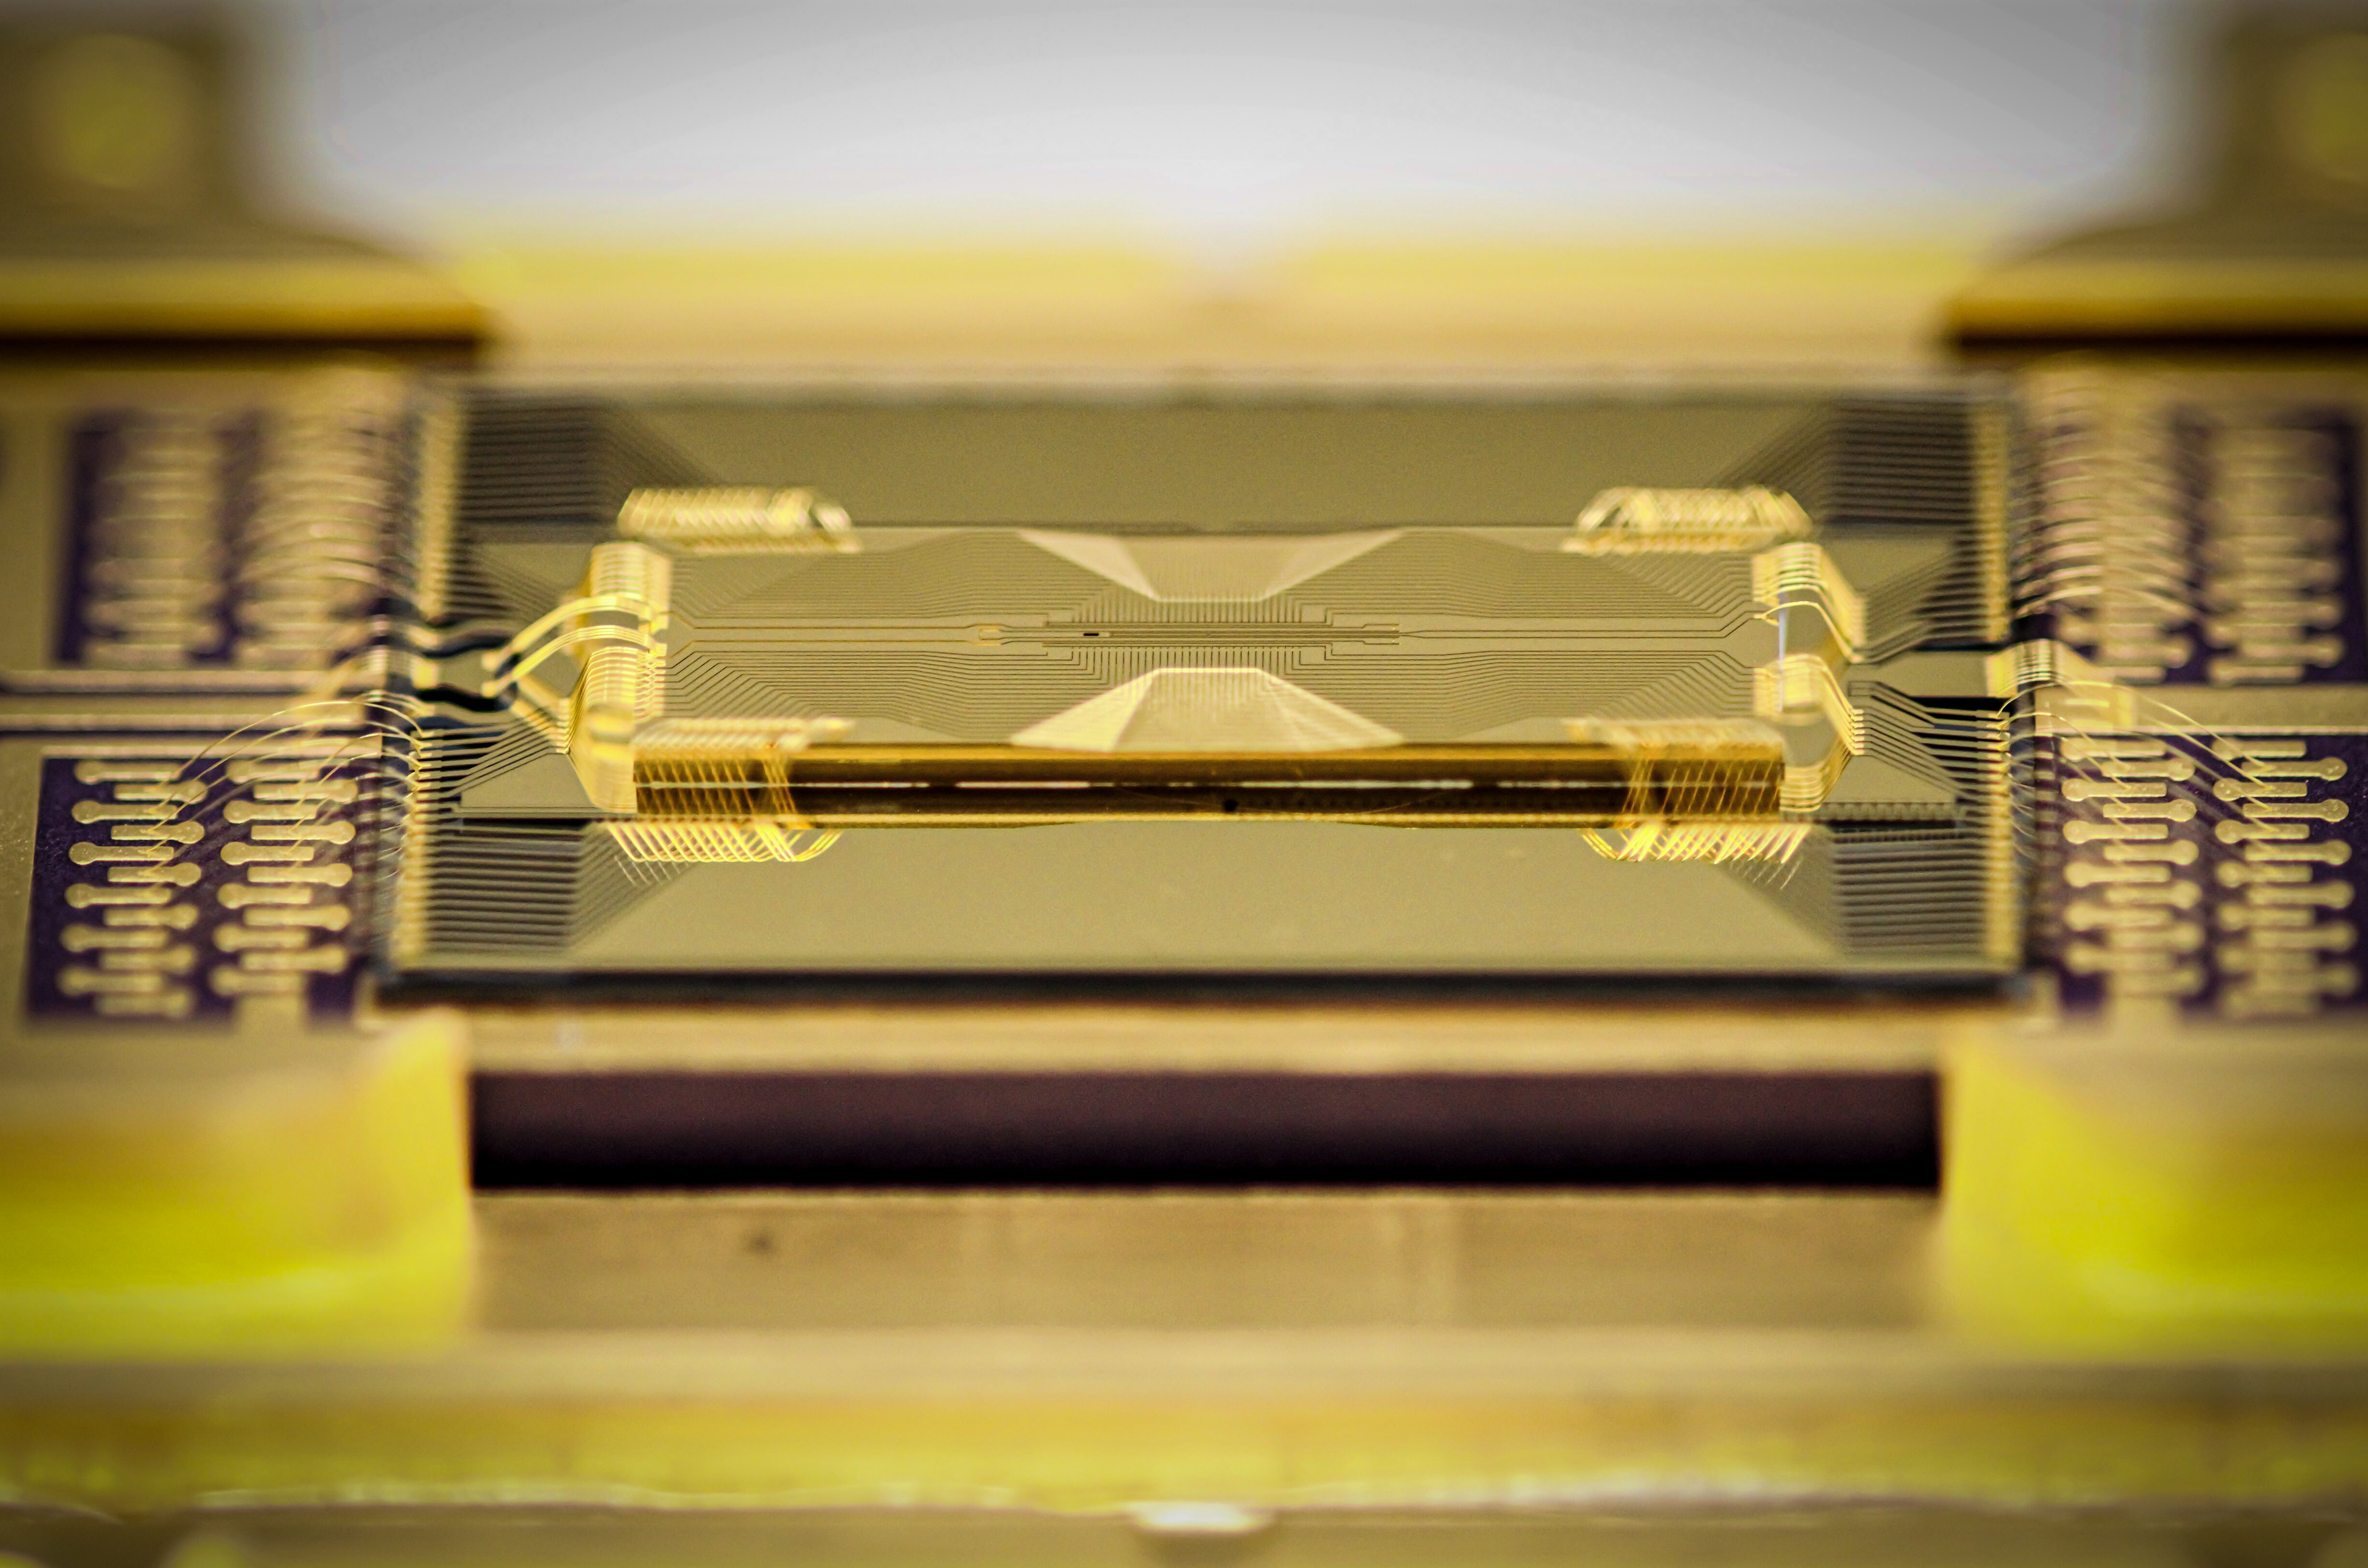
IonQ makes trapped-ion quantum computers. It has also expanded into networking, sensing and security, and into chipmaking through its $1.8 billion SkyWater Technology acquisition. It was the first public quantum company to top $100M in annual GAAP revenue. The stock still slid 20.09% in the past month.
Record Quarters and Raised Guidance Widen the Gap With a $31 Share Price
Second-quarter revenue reached $80.05M, up 286.8% year over year and ahead of the $66.42M consensus. Adjusted EPS of -$0.33 beat the -$0.5987 estimate. IonQ has exceeded revenue estimates in all six reported quarters. It also raised 2026 guidance to $280M-$290M, and that range excludes SkyWater. Remaining performance obligations rose to $485 million from $122 million a year earlier.
Shares rose as much as 13% after IonQ demonstrated what it called the industry’s first end-to-end real-time quantum error decoder. Deployment of its 256-qubit systems remains on track for the first half of 2027. None of the revenue from the Anduril and Sandia relationships is in backlog or guidance yet.
Heavy Losses and Falling Estimates Could Keep Shares Under Pressure
Quarterly operating income came in at -$337.2M, and stock-based compensation alone ran $141.8M. Analysts project a 2026 loss of $4.03 per share. Over the past 30 days, 2027 estimates drew four downward revisions against one upward.
At 50.59 times trailing sales, the valuation leaves little room for error. IonQ is absorbing SkyWater, Nexus Photonics, Oxford Ionics and Vector Atomic at the same time. Last quarter, Point72 and Cerberus exited their positions.
SkyWater’s First Combined Numbers Could Settle the Debate
Management has not yet given combined guidance. About $120 million of intercompany SkyWater spending will be eliminated in consolidation, which makes the next few reports harder to read. Clean combined guidance with steady cash burn would favor buyers. A slip in the 256-qubit timeline would favor sellers. Until then, $1.24B in cash and minimal debt give IonQ room to execute.
Analysts See Roughly 105% Upside as Shares Trail the S&P 500
IonQ trades below its 50-day average of $40.76 and its 200-day average of $42.92. Its 52-week range runs from $25.89 to $73.65, and its beta is 3.361. Analysts’ consensus target stands at $64.06, suggesting 104.86% upside. Targets are one data point, and they carry no guarantee for a stock this volatile. Here is how the 14 covering analysts rate it:
- Strong Buy: 1
- Buy: 11
- Hold: 2
- Sell: 0
Year to date, IonQ is down 30.31% while the S&P 500 is up 12.78%. Over one year, the comparison is -47.83% against 14.56%.
IonQ’s Fundamentals Outrun the Selloff Ahead of Key Tests
At $31.27, IonQ faces near-term tests that could reset the stock.
The first test is the third-quarter report. Consensus calls for revenue of about $141.2 million and a loss of $0.80 per share. Combined guidance that supports SkyWater adds to growth would ease the biggest uncertainty weighing on the stock.
The second test is 256-qubit commissioning in the first half of 2027. Analysts already expect 2027 revenue of about $808 million. Meeting the hardware schedule would back that estimate up with working machines.
The stock now stands closer to its 52-week low than its high, even after a string of record quarters. A guidance cut, a hardware delay or sharply faster cash burn would break the case. For investors trying to spot the next monster run in frontier tech early, we reverse-engineered what the biggest winners looked like years before the headlines in a free playbook here.
At $31.27, the stock trades well below the consensus analyst target while revenue continues to set records.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.