Investors Who Can Hold IonQ for a Year Should Know What to Do
IonQ just posted record revenue and a ballooning backlog, yet the stock sits near its 52-week low after another round of dilution. Whether the SkyWater acquisition changes that math depends on guidance the company has not yet provided.

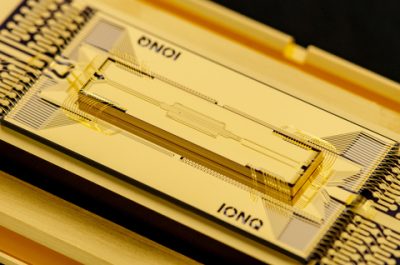
IonQ (NYSE:IONQ | IONQ Price Prediction) trades at $31.42, and the coming year will test a roadmap that leans heavily on acquisitions. The stock fell 9.53% in the latest session after IonQ announced a new equity offering.
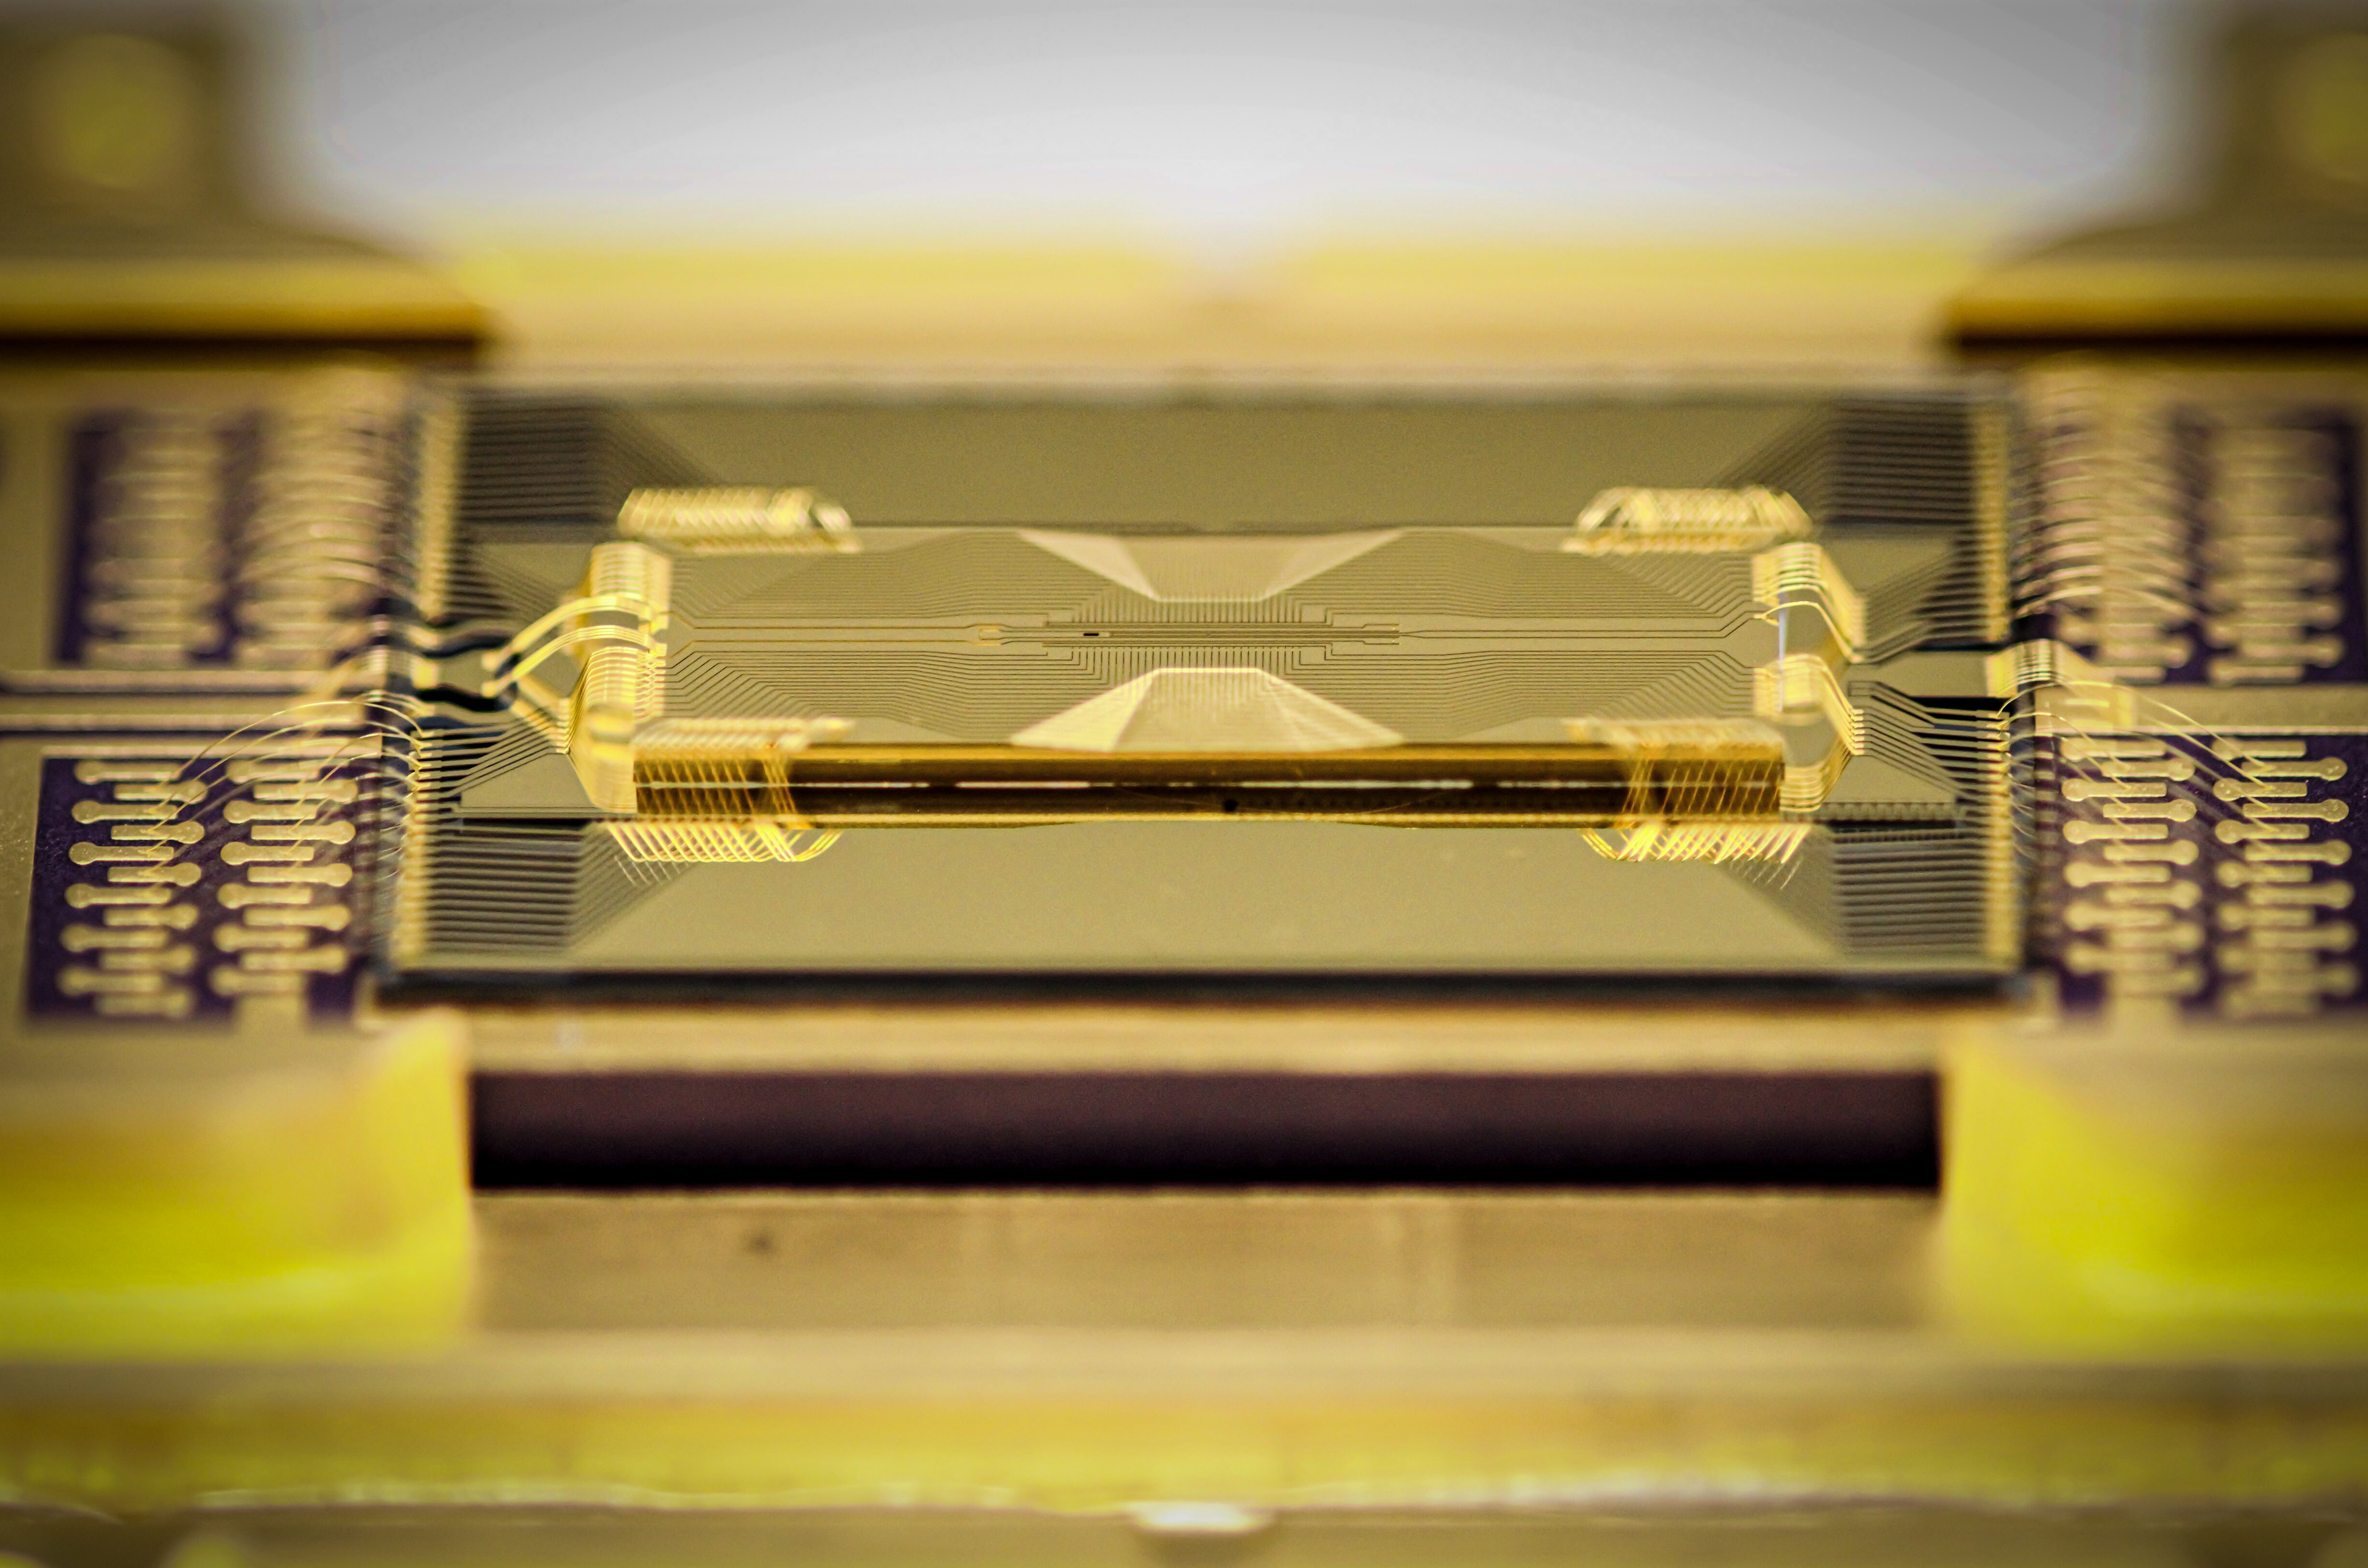
IonQ builds trapped-ion quantum computers and also sells networking, sensing, and security products. Its acquisition of SkyWater Technology closed on July 31, 2026, which gave it its own quantum chip foundry. Still, the stock is down 59.48% over the past year, despite what management called its “fifth consecutive quarter of record results”.
Revenue Is Surging and Backlog Has Nearly Quadrupled
Second-quarter revenue reached $80.05 million, up 286.8% year over year and well ahead of the $66.42 million consensus. Adjusted EPS came in at -$0.33, beating the -$0.60 estimate. Management raised full-year guidance to $280 million to $290 million, and that range does not yet include SkyWater. Remaining performance obligations, a measure of contracted future revenue, rose to $485 million from $122 million a year earlier.
Bulls also point to technical milestones. IonQ showed break-even quantum error correction and plans to begin commissioning 256-qubit systems in the first half of 2027. Wall Street largely sides with the optimists: 12 of the 14 covering analysts rate the stock Buy or Strong Buy.
Dilution and Cash Burn Give Bears Real Ammunition
Each new offering spreads ownership across more shares. Stock-based compensation alone came to $141.8 million in the second quarter. Adjusted EBITDA was negative $120.3 million for the quarter, and full-year guidance calls for a loss of $330 million to $310 million. The stock trades at about 45x the midpoint of revenue guidance, and its beta of 3.361 means it tends to swing much harder than the market (a name this volatile belongs in the speculative segment of a portfolio, with sizing and exit rules, the strategy we spelled out in a free guide here).
Strong quarters have also failed to support the stock. Across five earnings beats, shares averaged a -2.46% move in the week that followed.
SkyWater Guidance Will Shape the Next 12 Months
The core business is performing. IonQ held $1.24 billion in cash before the new raise. What investors still lack is visibility. Management has not issued combined guidance with SkyWater, and the partnerships with Anduril and Sandia are not included in its numbers. Combined guidance showing margin gains would strengthen the bull case. A slip in the 256-qubit timeline would strengthen the bear case.
IonQ Lags the S&P 500 While Analysts Stay Bullish
At $31.42, IonQ sits well below the average analyst target of $66.63, which means about 112% upside. Analyst targets are one data point and offer no guarantee. The 14 analysts break down as follows:
- Strong Buy: 1
- Buy: 11
- Hold: 2
Year to date, the stock is down 29.98%, while the S&P 500 is up 12.87%. Over one year, IonQ has lost 59.48% against the index’s 16.22% gain. Shares trade below their 200-day moving average, which sits at $43.20, and are approaching the 52-week low of $25.89.
Combined SkyWater Guidance Is the Next Key Catalyst
Revenue growth is genuine and the backlog supports it. Still, the newest equity raise shows that the cost of that growth falls partly on shareholders. Over the next two quarters, the key data point is combined IonQ and SkyWater guidance. Investors need to see whether foundry revenue and vertical integration narrow the EBITDA loss.
Each quarter, three things matter: growth in performance obligations, the trend in adjusted EBITDA, and whether management keeps the first half of 2027 target for 256-qubit commissioning. If all three hold up, the stock could re-rate toward analyst targets. Further dilution remains a risk in a stock with a beta above 3.
IonQ’s growth deserves attention, and the combined guidance that will clarify its path is still a few months away.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.