The AI Server Stock With a Massive Opportunity Ahead
Supermicro just lost nearly a quarter of its value in a single week while sitting on a record-breaking order book, and that contradiction is exactly what makes this stock so hard to ignore right now.

The 24/7 Wall St. price target for Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) sits at $40.15. The stock trades at $31.63, so the target means 26.93% upside. The shares carry a buy rating with high confidence.
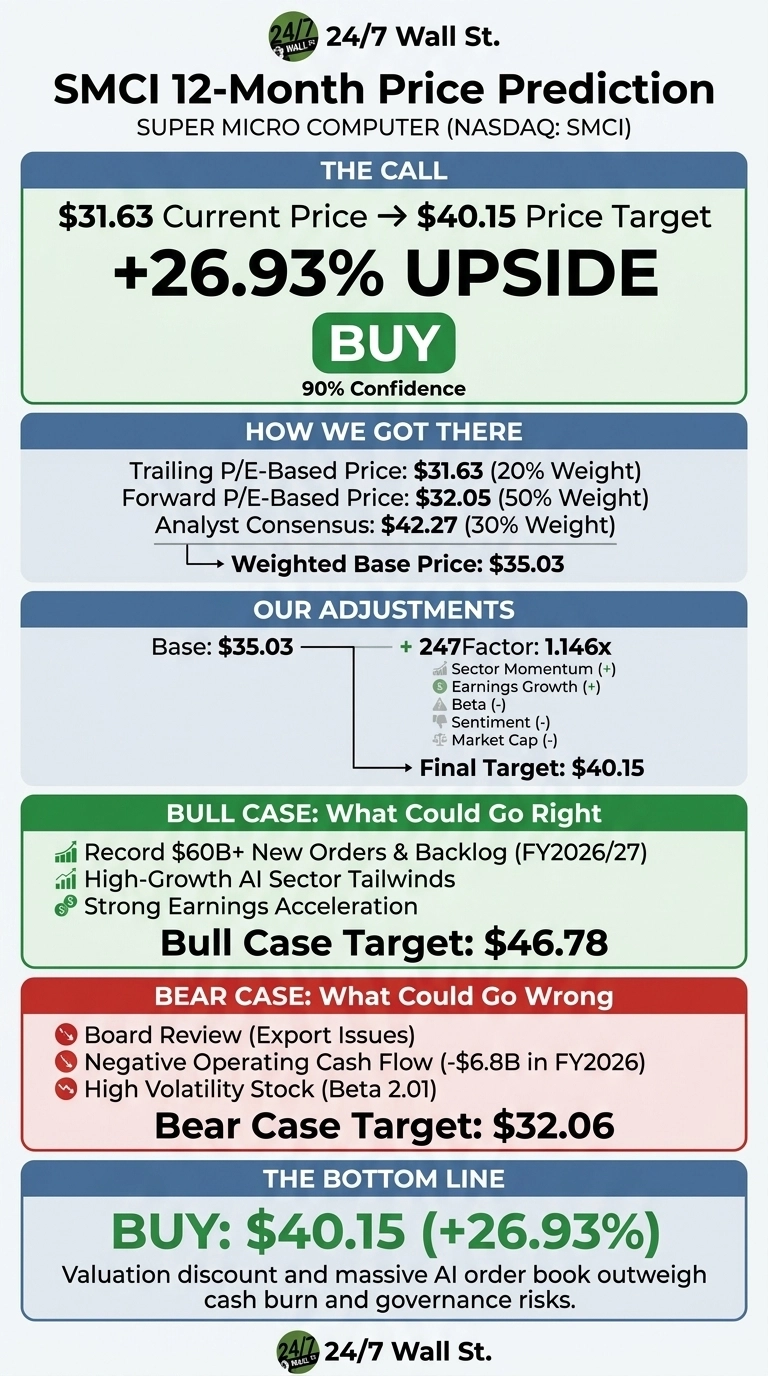
| Metric | Value |
|---|---|
| Current Price | $31.63 |
| Price Target from 24/7 Wall St. | $40.15 |
| Upside/Downside | 26.93% |
| Recommendation | BUY |
| Confidence Level | 90% |

Two things stand out together right now. The stock fell 24.43% in a single week, and management is still guiding fiscal 2027 revenue to $65B-$72B, up from $39.06B in fiscal 2026.
At a forward P/E of 7, the market is valuing Supermicro like a commodity hardware vendor. That discount looks too large for a company that booked over $60 billion in new orders last year.
AI Hardware Selloff Knocks Supermicro Back to Value Territory
Shares fell 9.86% on October 16 as AI hardware stocks came under renewed pressure over concerns about how the AI buildout will be financed. Supermicro’s own headlines also covered a new CFO appointment and heavy cash burn.
The stock is down 14.17% over the past month and 41.25% over the past year, though it is still up 8.06% year to date. It sits about 44% below its 52-week high of $56.60 and roughly 62% above its low of $19.48.
In the fiscal fourth quarter, revenue rose 93.2% to $11.12B, missing the $11.56B consensus. Non-GAAP EPS of $1.70 came in well ahead of the $0.96 estimate. Since that report, Supermicro has started shipping NVIDIA Vera Rubin NVL72 racks and has expanded its Open Compute Project portfolio.

Why Bulls See $46.78 Within Reach
Our bull case is $46.78. The biggest driver is the shift to full data center solutions. Chief executive Charles Liang said on the earnings call that “DCPBS will be our long-term much better profit margin product line.” Manufacturing capacity is on track to exceed 6,000 racks per month.
Supermicro had nine customers above $1 billion in revenue in fiscal 2026, up from four the year before. Enterprise and channel revenue jumped 172%. Large funds were adding during the June quarter.
Renaissance Technologies raised its stake 113%, and Balyasny opened a new position. The consensus analyst target of $42.27 sits above our base case.

Cash Burn and Governance Risks Could Cap Gains
Our bear case is $32.06. Operating cash flow was negative $6.8 billion in fiscal 2026. The cash conversion cycle (the number of days cash is linked up in operations) extended to 149 days.
The board is still reviewing transactions tied to export-control issues. One customer made up for 28% of revenue. Non-GAAP gross margin guidance for the current quarter is 10.4% to 10.8%, down from 17.6%.
Each of these risks has a partial offset. Supermicro generated $722 million of free cash flow in the fourth quarter. A $5.6 billion equity raise cut net debt to $1.2 billion from $7.5 billion. Management also said that contracts pushed into later quarters caused part of the margin spike.
Supermicro Trades at a Deep Discount to Dell and Arista
Dell Technologies (NYSE:DELL) is the most direct AI server rival. Last quarter it booked $60.9 billion in AI server orders and ended with a $95 billion backlog, yet it trades at roughly 24 times earnings.
Arista Networks (NYSE:ANET) sells into the same AI data center expansion on the networking side. Its premium margins support a P/E near 64.
| Company | Trailing P/E | Gross Margin |
|---|---|---|
| Super Micro Computer | 9 | 10.82% |
| Dell Technologies | 24 | 20.0% |
| Arista Networks | 64 | 64.1% |
Supermicro’s lower margins explain some of this gap. Even so, the 24/7 Wall St. price target looks conservative next to those two peers.
The same data center expansion driving Supermicro’s order book is raises a wider set of power, cooling, and networking suppliers that we profiled in a free AI infrastructure report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
Upside Outweighs the Risks at This Price
The 24/7 Wall St. price target of $40.15 carries a buy rating with 90% confidence. What tips the scale is valuation: the stock trades at single-digit multiples while orders sit at record levels.
The case gets stronger if Supermicro reports revenue within its $14.5B-$15.5B guidance range for the September quarter and the board review closes smoothly. It damps if cash burn returns or one large customer slows its orders.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $32.50 |
| 2027 | $39.78 |
| 2028 | $45.58 |
| 2029 | $55.27 |
| 2030 | $61.06 |
These projections assume Supermicro keeps executing on its data center solutions strategy. Results could land well above or below this path depending on how fast liquid cooling is adopted and how the export-control review is resolved.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.